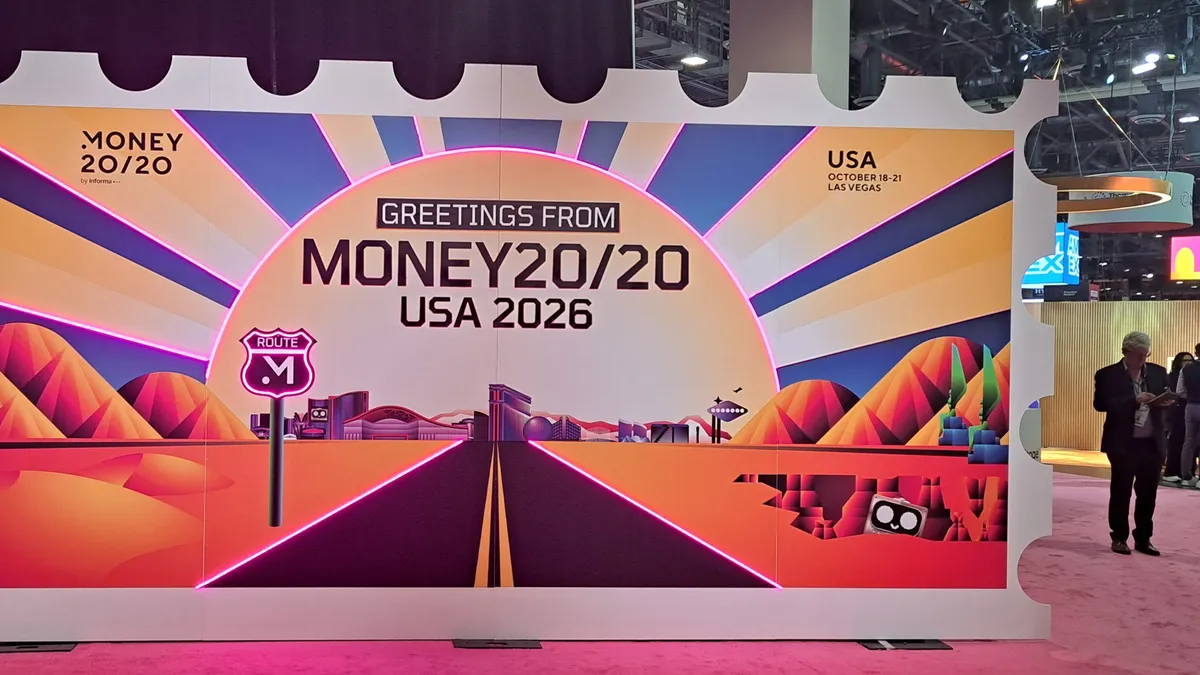
Global payments are moving faster, but local settlement remains a pain point for many companies, according to speakers on a Money20/20 panel.
Cross-border payments totaled about $190 trillion last year, generating about $290 billion in revenue for the payments industry, according to an August report from the consulting firm McKinsey.
Three-quarters of Swift-enabled payments reach the recipient’s beneficiary bank within 10 minutes, Amaro said. At that point, however, local rules, operating hours and other challenges slow the settlement process, regardless of whether a payment was sent via stablecoin, tokenized deposit or a traditional rail, she said.
Meanwhile, regulators in many countries are pushing for more price transparency with respect to the services, while compliance complexity has increased due to newer fintech entrants into the cross-border arena, the McKinsey report noted.
Some of the costs and complexities of cross-border payments are slowly decreasing, threatening to commoditize the field, said Jonathan Zell, a McKinsey partner in the consulting firm’s payments practice, who moderated the session.
Kush Saxena, CEO of Banking Circle Group, a Luxembourg-based fintech that specializes in cross-border payments, challenged that contention, drawing a distinction between cash and data transfers.
“I wouldn’t say moving money is a commodity. I think moving data is becoming easier,” Saxena said, noting “a ton of interoperability” the industry has created above the fiat level.
Source link