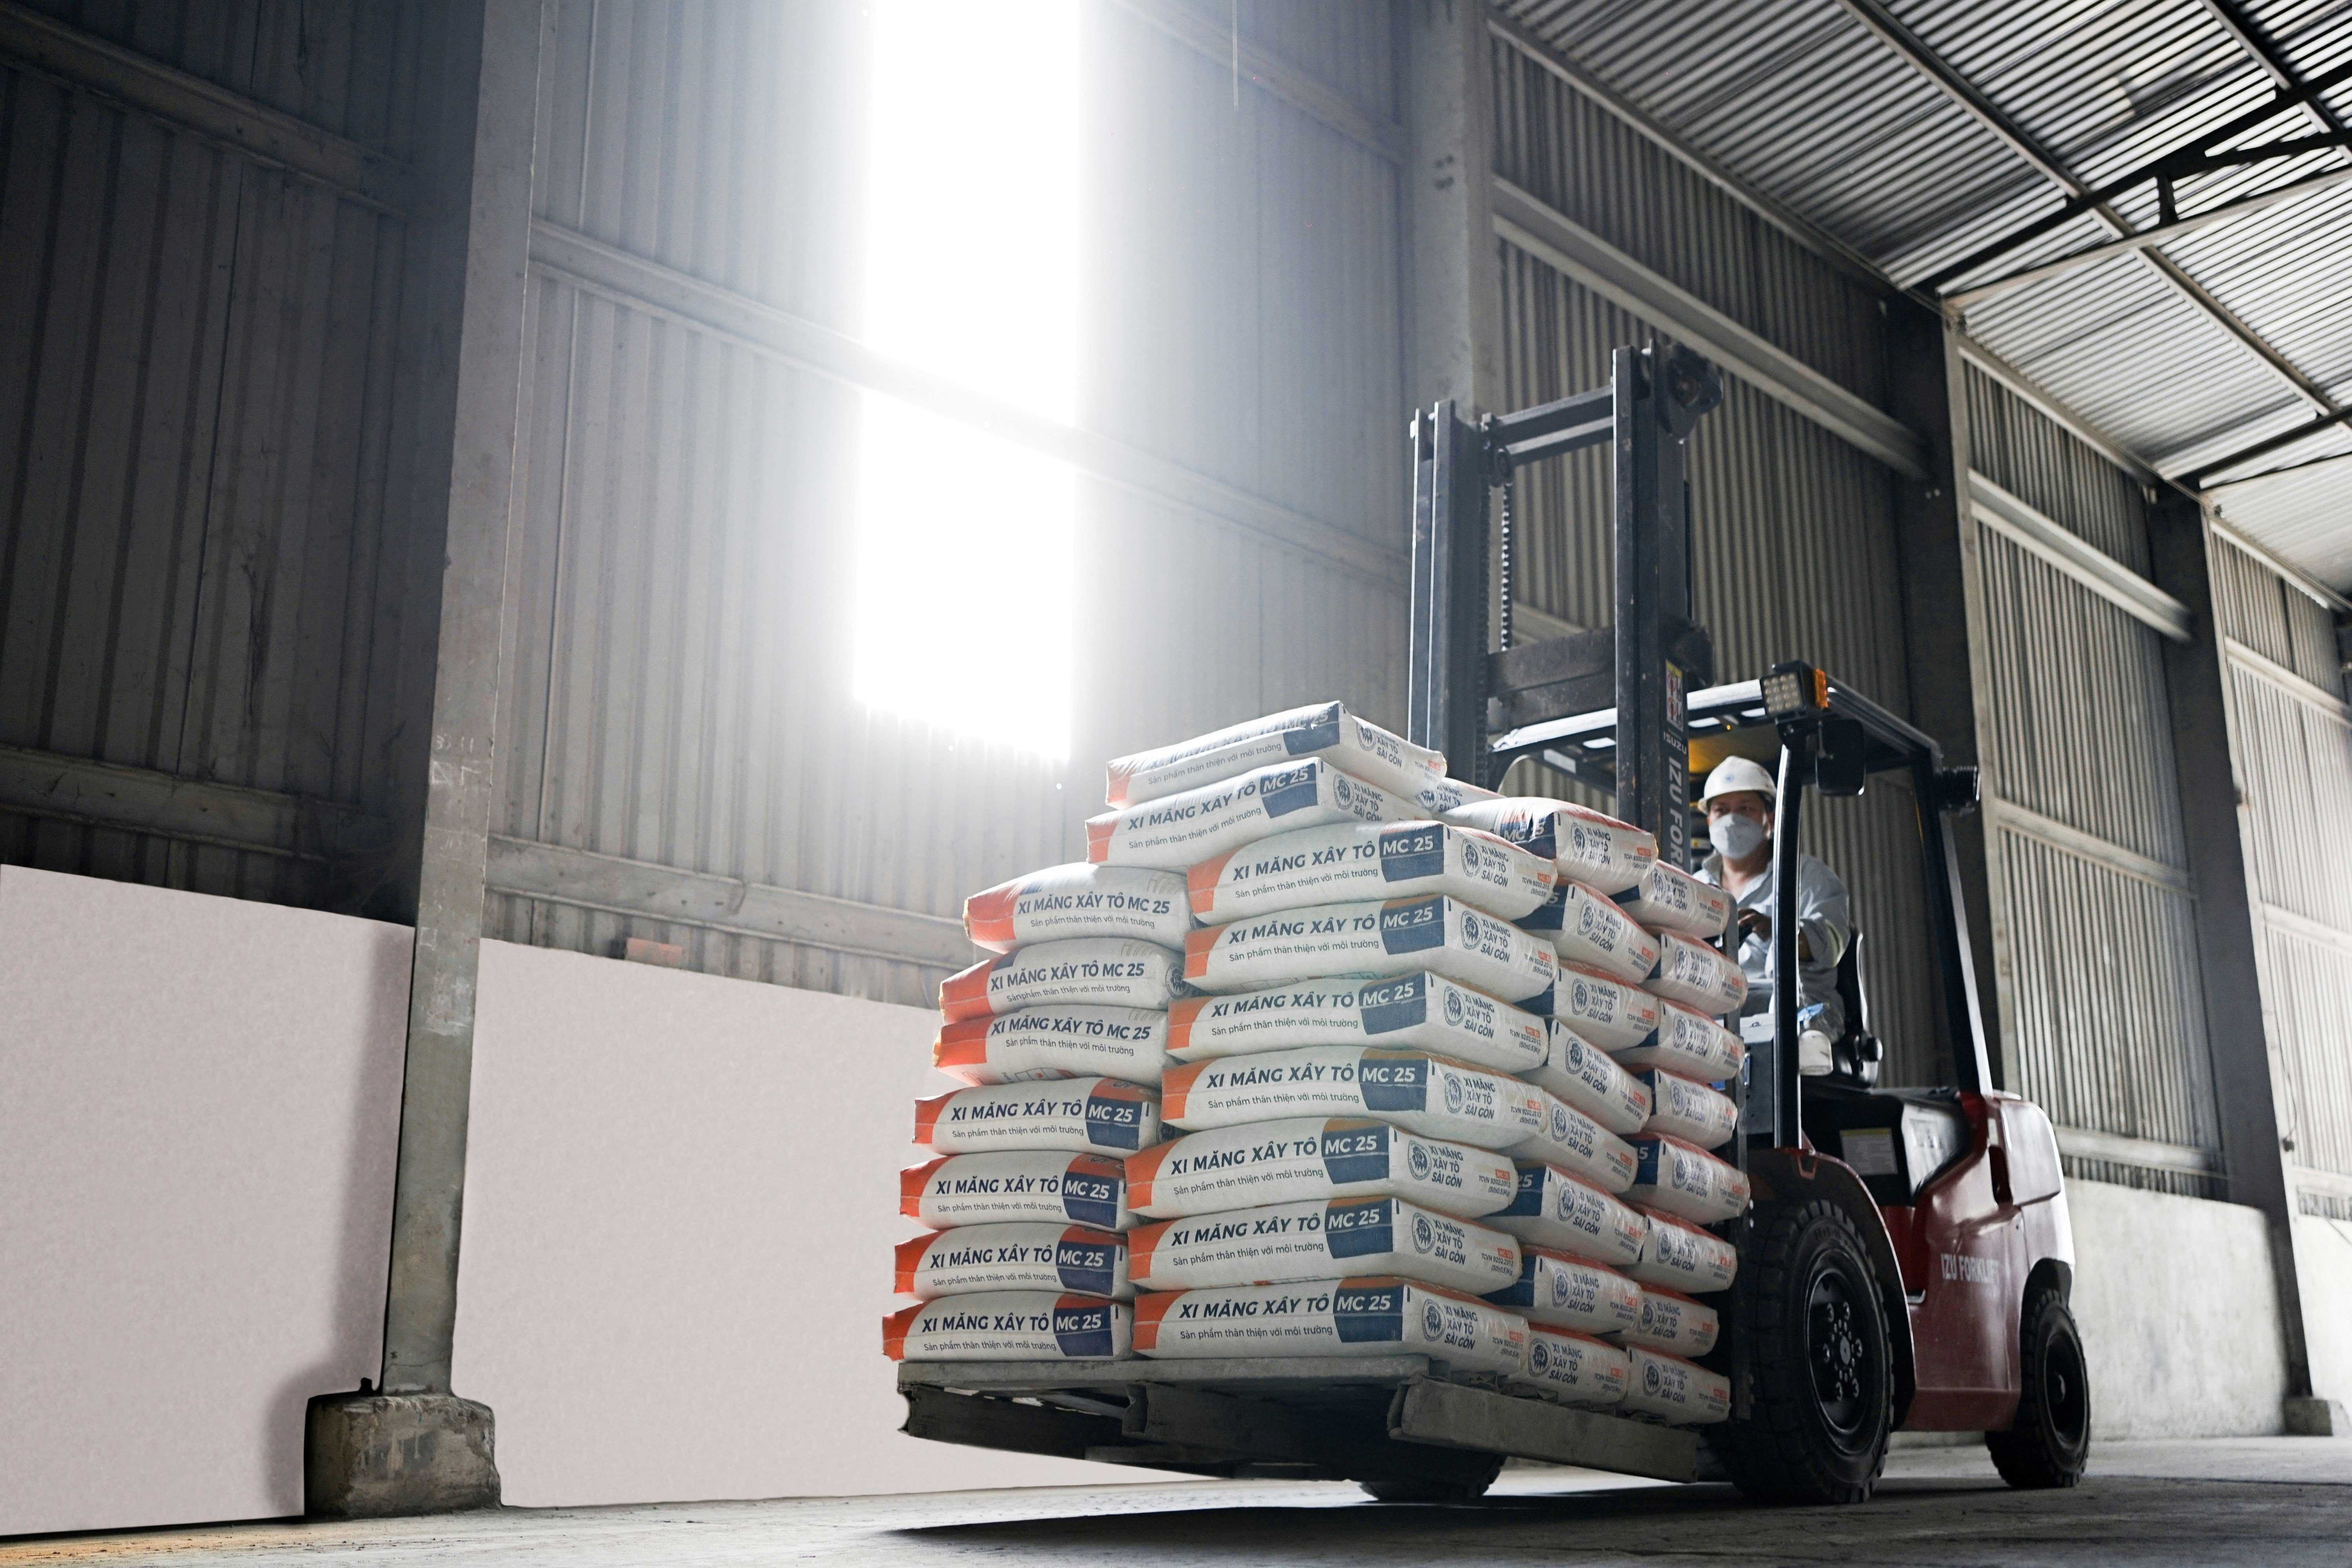
Importers are increasingly rerouting non-European cement into the United Kingdom following the rollout of the European Union’s Carbon Border Adjustment Mechanism (CBAM), pushing non-EU cement imports to their highest share since HM Revenue & Customs (HMRC) records began in 2000.
According to trade data analyzed by the Mineral Products Association (MPA), cement originating outside the EU accounted for 29.3% of all UK cement imports between January and September 2026, representing a substantial increase from 17.1% during the corresponding nine-month period in 2025. The MPA attributes the surge directly to trade diversion triggered when the EU CBAM entered its definitive financial compliance phase at the start of 2026.
While HMRC trade statistics do not provide a country-by-country breakdown of the incoming volumes, recent commercial announcements by UK port terminal operators establishing supply links with Turkish producers point to expanding non-EU import corridors.
Because overseas manufacturers in non-regulated jurisdictions frequently rely on coal-fired kilns and fossil fuel subsidies, British cement producers face growing competitive pressure from higher-carbon imports entering the domestic market free of equivalent carbon costs.
The trade diversion findings arrive ahead of the November 20 EU-UK Summit in Brussels, where leaders are expected to announce the conclusion of negotiations to link the EU Emissions Trading System (EU ETS) and the UK Emissions Trading Scheme (UK ETS) – a step designed to pave the way for mutual CBAM exemptions between both jurisdictions.
Although the UK is scheduled to introduce its own domestic CBAM on January 1, 2027, industry leaders warn that structural design gaps will leave British manufacturers exposed to ongoing carbon leakage.
Source link