Four open Granite models, one extensible forecasting interface, and less guesswork about which model to use.
Pre-trained time-series models can forecast without training on your dataset, but you still have to choose one. A model that handles smooth industrial signals well may struggle with noisy retail demand or a long seasonal horizon, and the best choice depends on the series and the task.
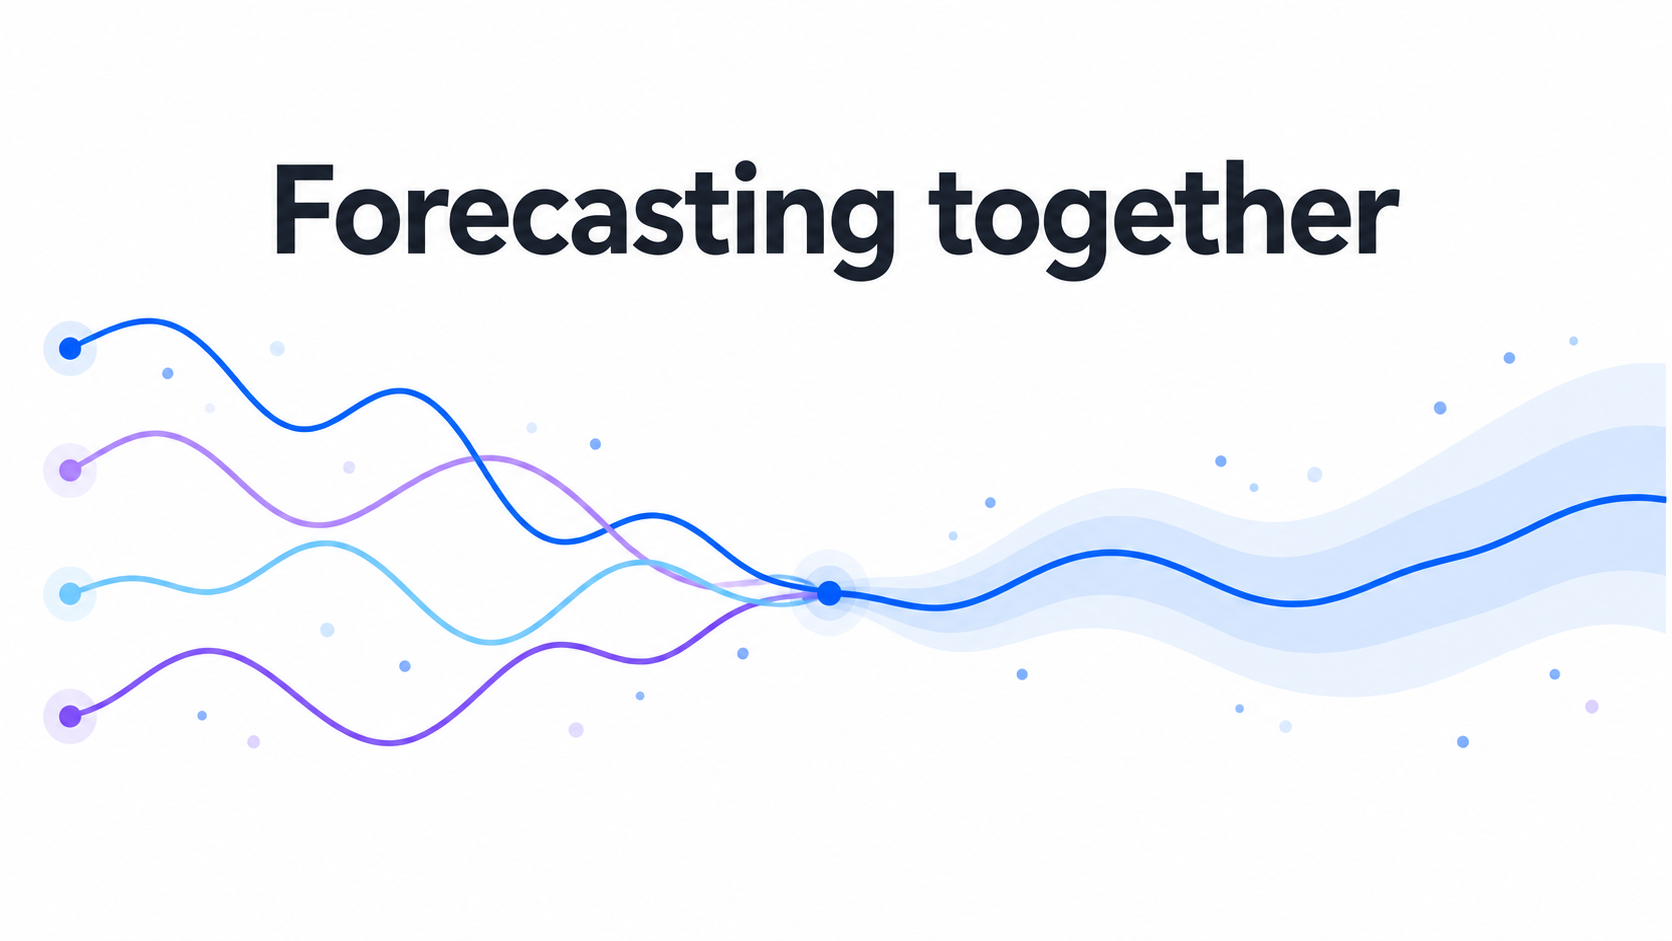
Granite Timeseries Ensemble reduces that choice to a sensible default. One recipe combines four complementary Granite architectures and returns median and quantile forecasts, with no retraining and no fitted ensemble weights. Start with the Probabilistic Ensemble (uniform probability pooling), compare the adaptive Inter Quartile Range (IQR) Ensemble, and extend the same interface with compatible forecasters. The ensemble recipe and its default Granite members are permissively licensed.
The idea will be familiar from weather forecasting. Ensemble forecasts explore a range of possible outcomes, and systems such as the North American Multi-Model Ensemble combine different models for seasonal prediction. Time-series forecasting benefits in a similar way: complementary models offer different views of what comes next, and an ensemble merges those views into one forecast.
Install Granite TSFM and load the recommended four-model recipe directly from Hugging Face:
The recipe stores the ensemble configuration rather than merged model weights. It downloads the four member checkpoints at runtime, so allow extra time for the first run. For the full configuration, member checkpoints, evaluation details, and limitations, see the model card.
9. Applications can use the point value as a central prediction and selected quantiles to express forecast ranges.
Source link