
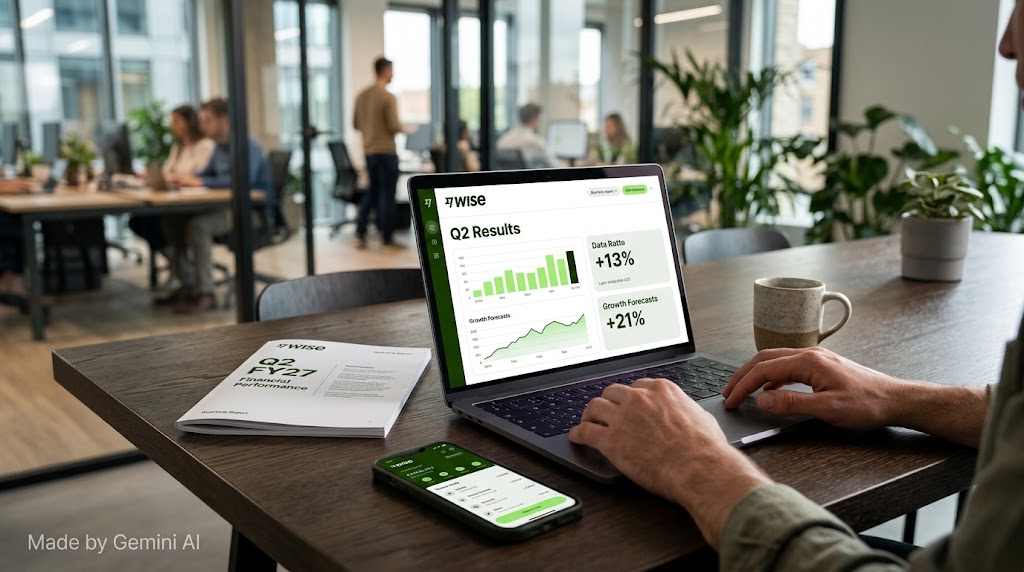
The outperformance was driven primarily by net interest income, which beat expectations on both gross yield and customer balance metrics, compensating for a modest shortfall in volume per customer. Total payment volume grew 22% year-on-year to $72 billion, though it came in 2% below consensus owing to that VPC miss.
Active customers reached 12.5 million at the end of the quarter, up 20% year-on-year and 5% sequentially, with Personal customers growing to 11.9 million and Business customers reaching 633,000. The Business segment is the faster grower on a percentage basis, up 31% year-on-year in TPV terms to $22 billion.
Card and other revenue was the standout line, rising 34% year-on-year to $206 million, 3% ahead of consensus. Card spend TPV grew 30%, and the card book now accounts for 27% of net revenue, up from a lower base in the prior year. That structural shift matters: card revenue carries different margin and competitive dynamics than the core cross-border transfer business, and its increasing weight provides a partial hedge against the gradual compression in cross-border take rates, which fell 1 basis point sequentially to 50 basis points.
Total customer holdings reached $44 billion, with Wise account balances of $32 billion growing 4% sequentially. The gross yield implied on those balances was 2.3%, down from 3.0% in the prior quarter, reflecting the interest-rate environment.
Wise has also continued its share buyback, completing 39% of a planned $550 million programme that began in July 2026 and runs to March 2027. 10 per share, representing around 2% of the diluted share count.
Source link