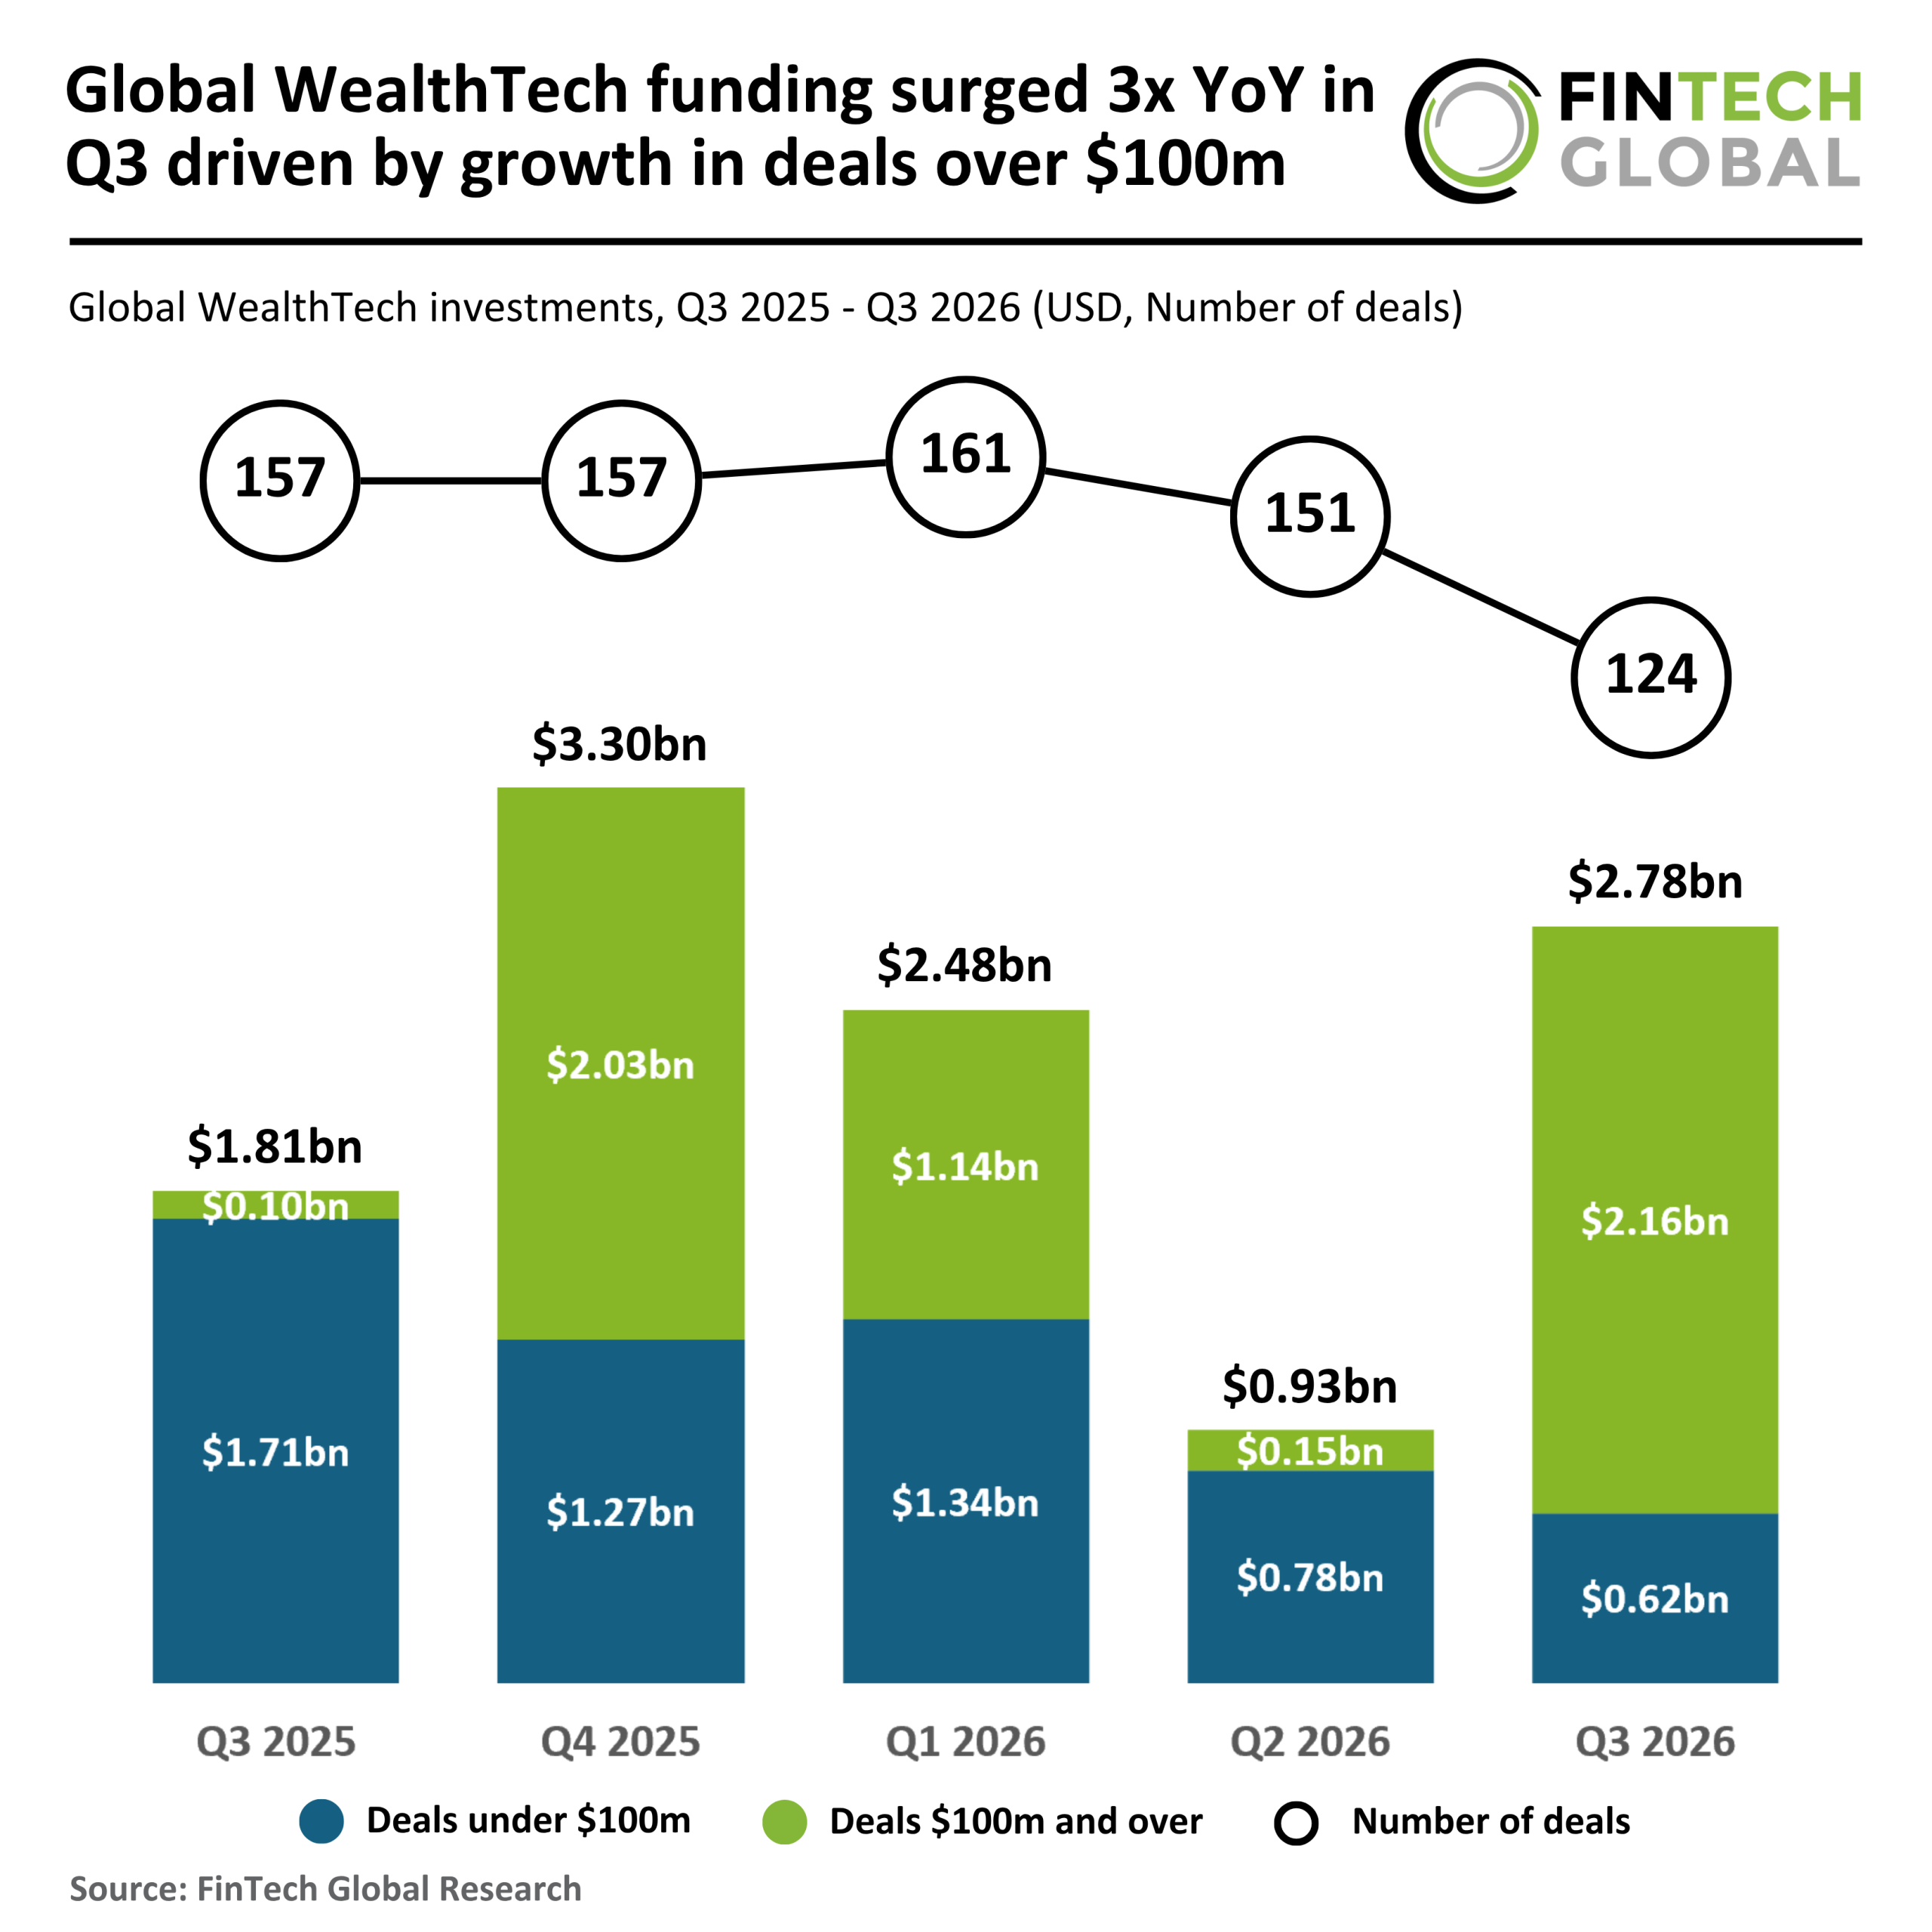
Global WealthTech companies raised $2.8bn across 124 deals in Q3 2026, 3x the $932.2m recorded across 151 deals in Q2 2026, though deal volume was 18% lower over the same period.
Against the same quarter a year earlier, funding was up 54% from the $1.8bn raised across 157 deals in Q3 2025, whilst deal volume fell 21%.
The divergence between rising funding and falling deal counts is the defining characteristic of Q3 2026 and points to a market increasingly shaped by a smaller number of high-value transactions.
Average deal size was $11.5m in Q3 2025, rising to $6.2m in Q2 2026 before jumping to $22.5m in Q3 2026, its highest level across the period and a clear signal of how significantly the composition of activity has shifted.
Funding surge was driven by a 14.4x growth of deals over $100m
Funding from transactions under $100m reached $624.2m in Q3 2026, down 64% from the $1.7bn recorded in Q3 2025 and down 20% from the $782.2m seen in Q2 2026.
Larger deals of $100m or more came in at $2.2bn in Q3 2026, 21.6x the $100m recorded in Q3 2025 and 14.4x the $150m seen in Q2 2026, a total derived from just eight transactions.
That concentration underlines how heavily the quarter’s headline funding figure rests on a handful of large commitments.
With larger deals now representing 78% of total funding compared to just 6% in Q3 2025, the market has undergone a dramatic compositional shift, though whether that proves to be a turning point or a temporary concentration of activity remains to be seen.
Source link