
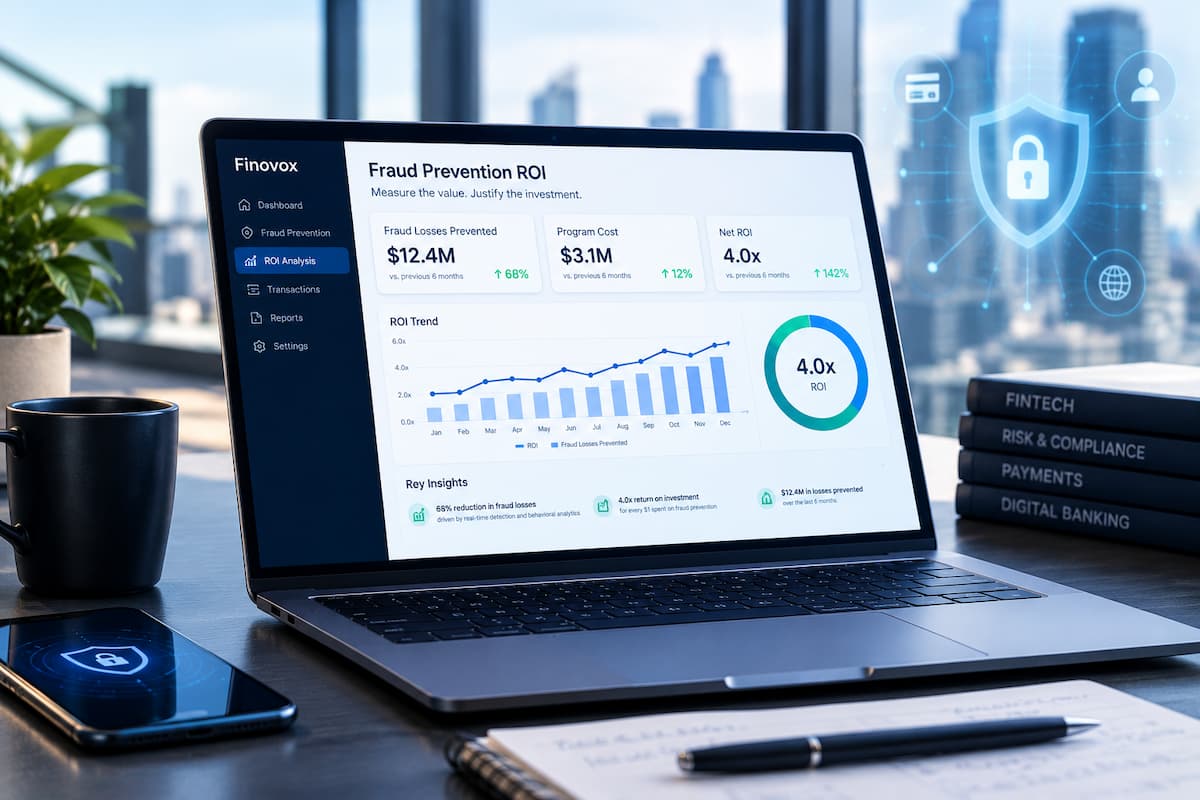
The new capability links individual fraud decisions to their financial impact, so organisations can track avoided losses and operational savings over time inside the Finovox reporting environment. Until now, the Paris-based company says, many of its prospective customers have relied on manual spreadsheets to work out whether their fraud prevention spending was paying off, adding administrative work for already stretched teams.
The cost of fraud runs well beyond the value of a fraudulent transaction. Investigating a suspicious case by hand can take around an hour, Finovox estimates, compared with roughly three minutes using its new investigation tool. Time spent on reviews, slower processing and the wider operational burden all add to the bill, and are rarely captured in a single figure.
Research Finovox carried out with the polling institute Selvitys puts fraudulent documents at around 3 per cent of document flows in banking and 5 per cent in insurance. The same study estimates the value of a typical fraud case at about 5,000 euros in banking and 500 euros in insurance.
Marc de Beaucorps, co-founder and CEO of Finovox, said: “You can’t effectively tackle a problem if you don’t understand how much it is costing your business. Fraud is no different. Yet many companies still struggle to quantify its true financial and operational impact. Our new ROI tool is designed to change that, giving businesses a clear view of the losses they are preventing and the value their fraud prevention efforts are creating.”
The aim, the company says, is to move customers beyond simply detecting fraud towards understanding what it costs them and how much prevention saves.
Source link