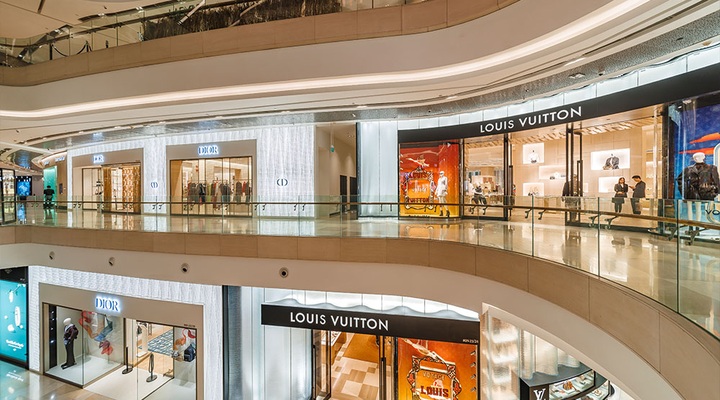
No matter how interesting the retail industry is – and it’s arguably getting more interesting every day – the quarterly reports of the big retail landlords in Singapore are almost always predictable and dull.
Investors like predictable and dull, so this is a compliment and not a criticism. It reflects an underlying nose-to-the-grindstone kind of diligence on the part of retail property owners, a belief that even when things get rocky on the consumer side, it is always business as usual in the malls: they will invariably be able to find an answer to challenges by juggling tenancies, creating social spaces, and hosting what seems to be a never-ending cycle of community events.
So it was again in the third quarter. 3 per cent growth in August – rents also edged up and can be expected to continue doing so because new retail floor space is going to be well below the historic average through at least the end of the decade. What new space there is will do little more than match demand by retailers, particularly those from the food and beverage, health and beauty, and fashion accessories categories which have experienced the strongest sales growth this year. Orchard Road, secondary downtown shopping precincts and suburban areas are all seeing upward pressure on occupancy costs for retailers. In this respect, Singapore is in a similar situation to other major Southeast Asian cities like Bangkok and Ho Chi Minh City.
Source link