The apparel brand’s Q3 net revenue jumped 19% and analysts remarked on its strong performance as a newly public company.
Reformation may be new to the public markets, but its recent quarterly results have exceeded expectations, according to analysts from William Blair.
“The company continues to demonstrate an ability to read and react to demand faster than traditional apparel peers (weekly apparel drops), while strong brand resonance is driving outsized customer acquisition alongside healthy retention and cohort spending,” William Blair analysts remarked in a Thursday note. “New stores are also tracking ahead of plan and driving broader DTC growth in their markets, while AI-enabled merchandising should further enhance the company’s ability to localize assortments and chase demand as it scales.”
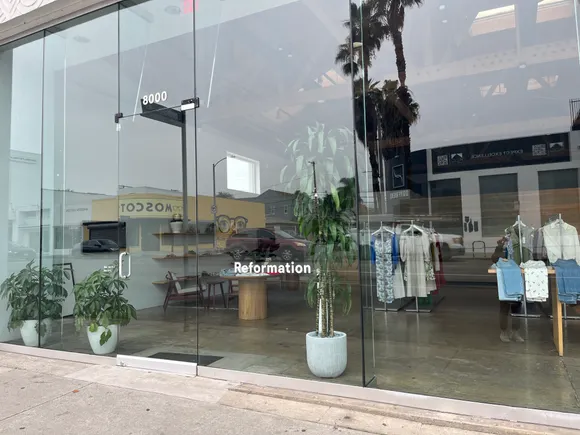
The DTC-focused apparel brand opened seven new stores in the quarter and ended the period with 77 locations.
Active customers during Q3 jumped 23.4% to 1.25 million and the brand raised its full-year guidance. Reformation now expects net revenue for the year to range from $610 million to $612 million, an increase from the previously expected range of $602 million to $606 million.
Looking to the holidays, the brand’s fourth quarter is off to a good start, Borenstein told analysts on the call.
“We are confident heading into Q4 based on all of the data we've seen so far and the response,” the chief executive said, adding that Reformation’s agile and fast merchandising model is “a particular advantage in a dynamic environment right now, particularly in holiday because we are able to so quickly identify trends and respond in a period that is so important.”
Source link