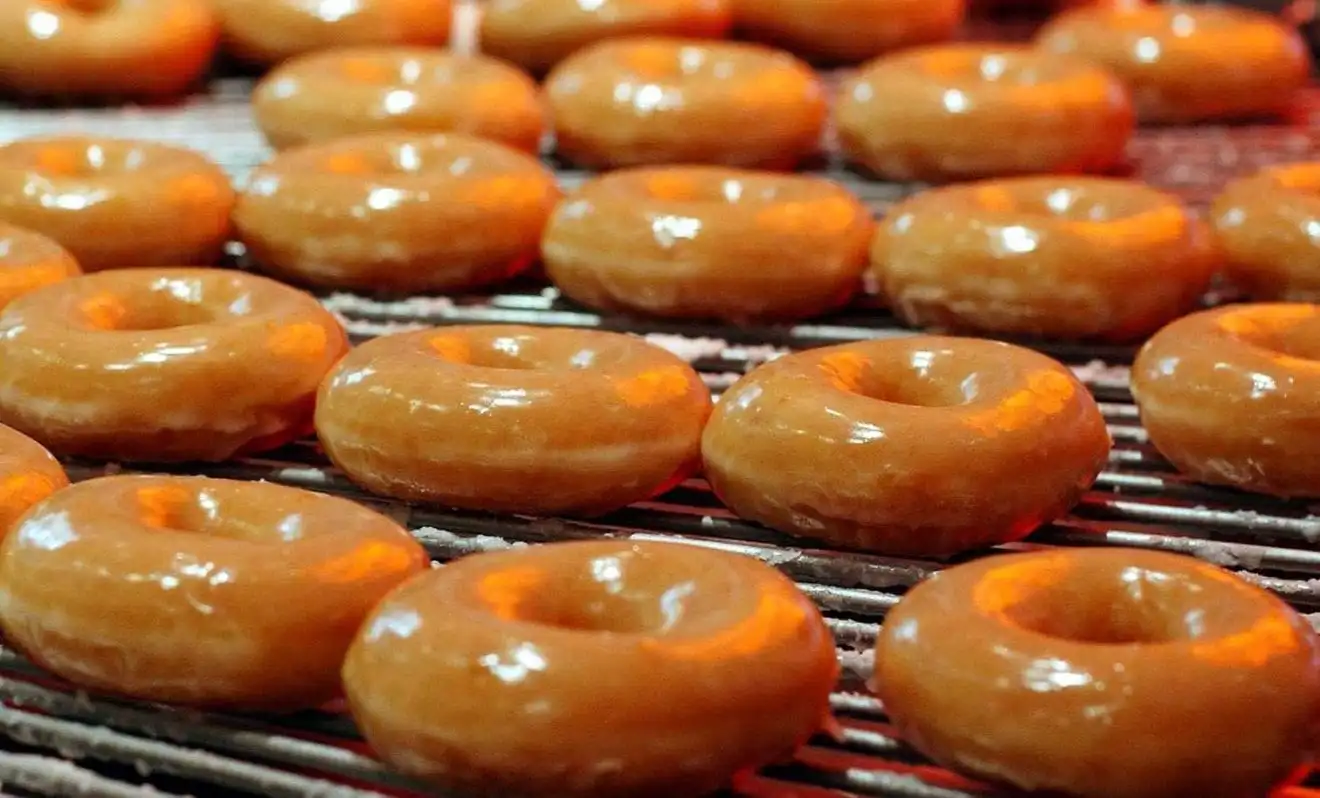
Krispy Kreme narrowed its third-quarter loss to $13.4 million on Thursday as restructuring moves began lowering overheads.
The deficit narrowed from $20.3 million in the second quarter and $19.4 million reported a year ago.
Adjusted earnings hit $9.9 million when excluding expenses from selling Krispy Kreme Doughnut Japan Co. Ltd. And paring its stake in a western US joint venture with WKS Restaurant Group from 55% to 20%.
Krispy Kreme confirmed plans to refranchise select company-owned operations in Japan, Australia, New Zealand, Mexico, Ireland and the UK. The strategy trades direct capital investment for steady franchise fees, reducing balance-sheet exposure in overseas territories where local supply chains and retail leasing costs compress margins.
International division revenue fell 11.9 per cent to $123.5 million during the quarter. US sales dropped 25.6 per cent to $160.9 million, heavily influenced by the closure of roughly 1,400 underperforming American shops during the third quarter of 2025.
By contrast, the company’s market development unit surged 135.3 per cent to $44.4 million. The division captures smaller fresh shops, direct delivery channels and mobile food trucks, formats that demand substantially less capital than traditional factory stores with dedicated production lines.
For quick-service operators across Asia, running corporate-owned production hubs in high-cost metro markets like Tokyo has grown increasingly punitive. Rising import expenses for core ingredients, utility inflation and tight retail labour markets have made master franchisee models far more attractive to multinational head offices.
Local partners absorb local operational risk. They handle storefront rent negotiations, regional distribution logistics and store-level staffing while the parent company collects recurring royalties and brand fees.
Source link