
A lot of energy-transition analysis begins with an assumption that is easy to miss: the size and shape of today’s market are carried into the future. Once that happens, the analytical task becomes finding a low-carbon substitute for everything the incumbent system currently supplies.
That approach can make the replacement problem much larger than it needs to be. Industries change as the energy transition proceeds, technologies compete across sector boundaries, demand responds to price, and some of the commodities that dominate today’s energy system shrink for reasons that have little to do with the technology being proposed as their replacement.
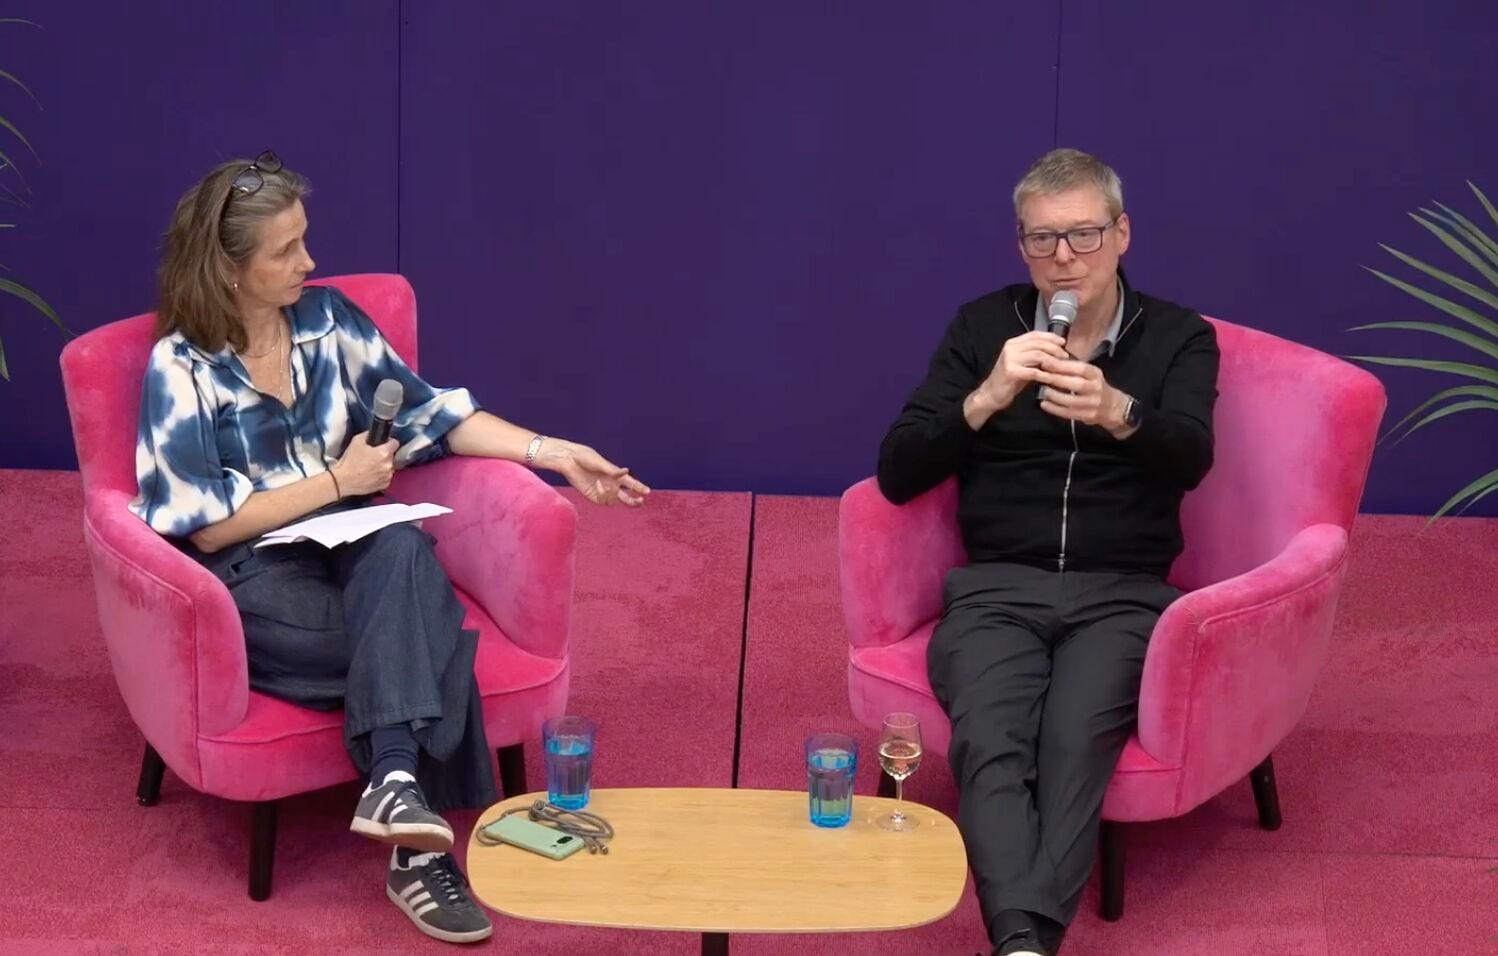
I discussed this recently with Amy Rennison at an Earth Set event at Octopus Energy’s London headquarters. The conversation covered shipping, hydrogen, grids, heat pumps, aviation, carbon removal and data centres, with questions from the audience repeatedly pulling us back to the assumptions underneath apparently confident transition forecasts. I expanded the discussion in The Energy Transition Has An Assumptions Problem.
Shipping is a good place to see the problem. Roughly 40% of maritime freight tonnage is coal, oil and gas, with raw iron ore accounting for another 15%. Fossil-fuel demand declines as energy systems electrify, steel production changes, and inland and short-sea routes increasingly become candidates for battery electrification. All of those changes affect the amount of liquid fuel the shipping industry will eventually require.
My projection leaves about 70 million tonnes of annual shipping fuel demand by 2100. Other projections reach several hundred million tonnes. That gap has enormous consequences for investment because it changes how much biomass, synthetic fuel, renewable electricity and supporting infrastructure appear necessary.
Source link