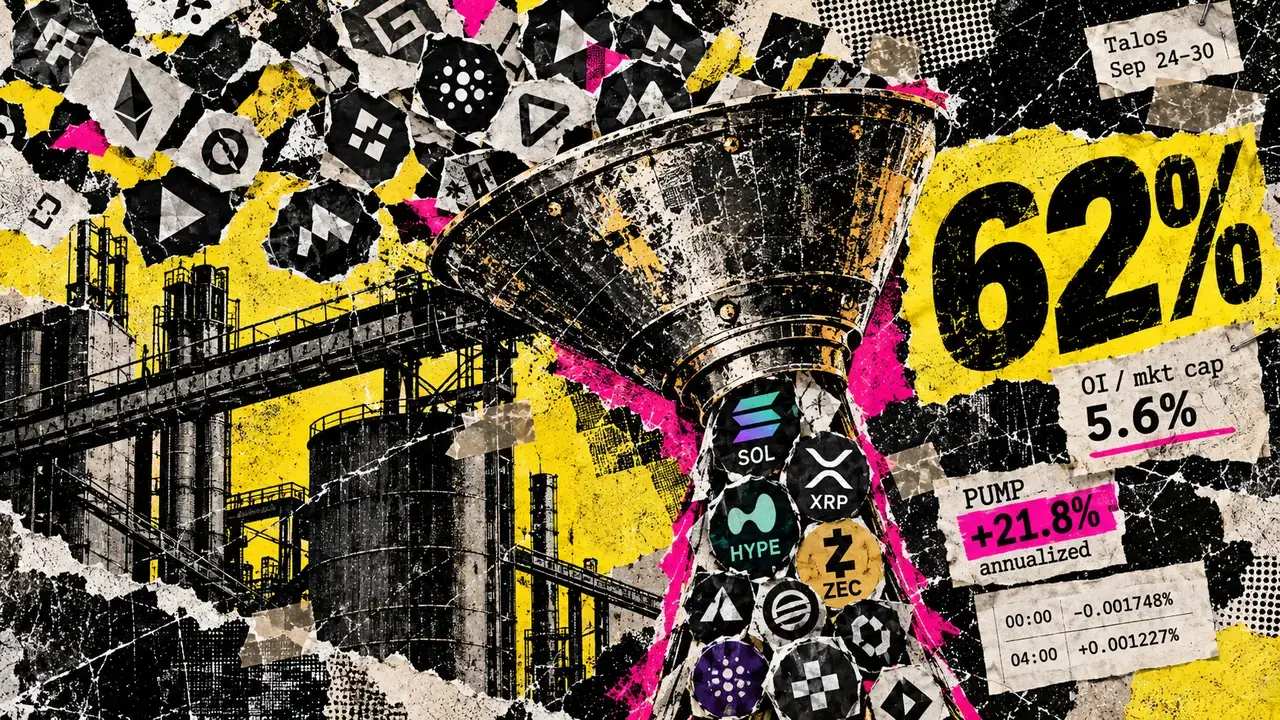
Ten tokens accounted for 62% of outstanding altcoin futures exposure, known as open interest, in Talos’s weekly market report covering September 24–30, 2026. That concentrated exposure came with different financing burdens: the report put SOL funding below zero while PUMP funding reached +21.8% annualized.
Published October 1, the market report also put altcoin open interest relative to market capitalization at 5.6%, a record in Talos’s series. For investors entering the October trading week, those numbers identify a concentrated derivatives footprint, while later Binance settlements show how quickly the cost of holding a particular contract can change.
Perpetual futures use funding payments to help keep the contract price aligned with the underlying market. As Hyperliquid’s funding mechanics explain, positive rates transfer money from long holders to short holders. Negative rates reverse that direction. A trader’s financing burden therefore depends on the contract, side and funding interval, even when two tokens both have substantial open interest.
The October 5 refresh covers two Binance contracts, rather than a matching update to Talos’s altcoin aggregate. Their settled payment records, retrieved shortly after 04:20 UTC, show positive SOL funding and a PUMP rate that changed sign within four hours.
Sources: Binance’s SOL settlements and PUMP settlements. Rates are native settlement percentages, not annualized rates.
SOL’s preceding observed payment, at 16:00 UTC on October 4, was also +0.010000%, eight hours before the midnight payment. PUMP’s two observed payments were four hours apart.
PUMP’s midnight payment charged shorts; its 04:00 payment charged longs. The change illustrates a financing burden that can reverse while the underlying contract remains the same.
Source link