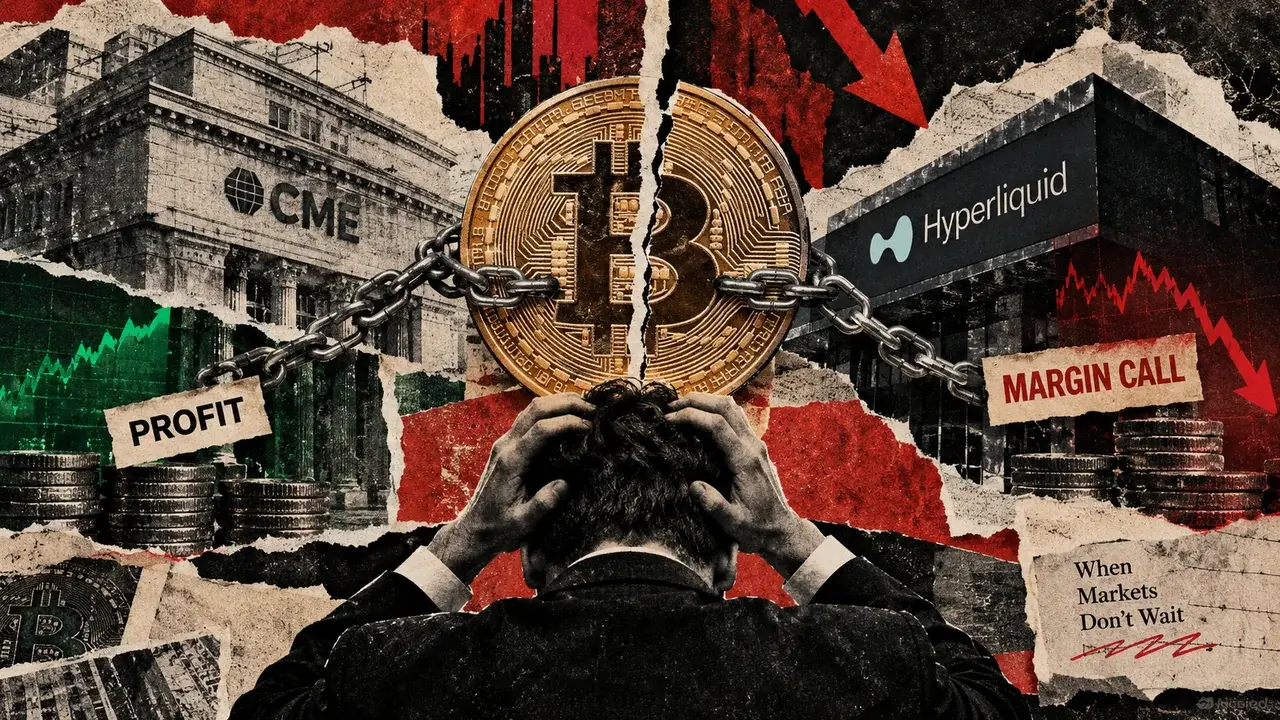
Here's a hypothetical situation: a hedge fund is making money, but one of its exchanges is about to liquidate its position anyway. Bitcoin has fallen, its short position on CME is profitable, and the matching long on Hyperliquid is bleeding cash. The two trades were designed to offset each other, but Hyperliquid can't use profits sitting at CME to cover the losses on its own books. The fund has to find more collateral before the exchange closes the position for it.
Moving money between exchanges takes time, and during a downturn, withdrawals can slow down or stop altogether. The fund could have enough money to cover every position and still lose half its hedge because the profits are sitting in different accounts.
Once that happens, a strategy designed to avoid betting on Bitcoin's direction can suddenly become a very large bet on where the price goes next.
In the high-stakes world of institutional Bitcoin trading, a fund can be profitable across its entire portfolio and still face forced liquidation because the exchange holding its losing position doesn't know or care about the money it has made somewhere else.
And the more efficiently the fund uses its capital, the less money it may have sitting around to solve the problem.
Here's another hypothetical situation: a fund holding two opposing Bitcoin positions. It's long Bitcoin on Hyperliquid and short Bitcoin futures on CME, with both positions worth $4.5 million.
If Bitcoin falls 20%, the short position earns roughly $900,000 while the long loses approximately the same amount, assuming both contracts track the price equally.
Source link