Japan’s October 6, 2026 auction of ten-year government bonds attracted more competitive demand relative to the debt sold, even as its average yield rose to 3.101%. For Bitcoin, higher returns on Japanese debt raise a question about how a sustained shift in bond allocation could affect global financing.
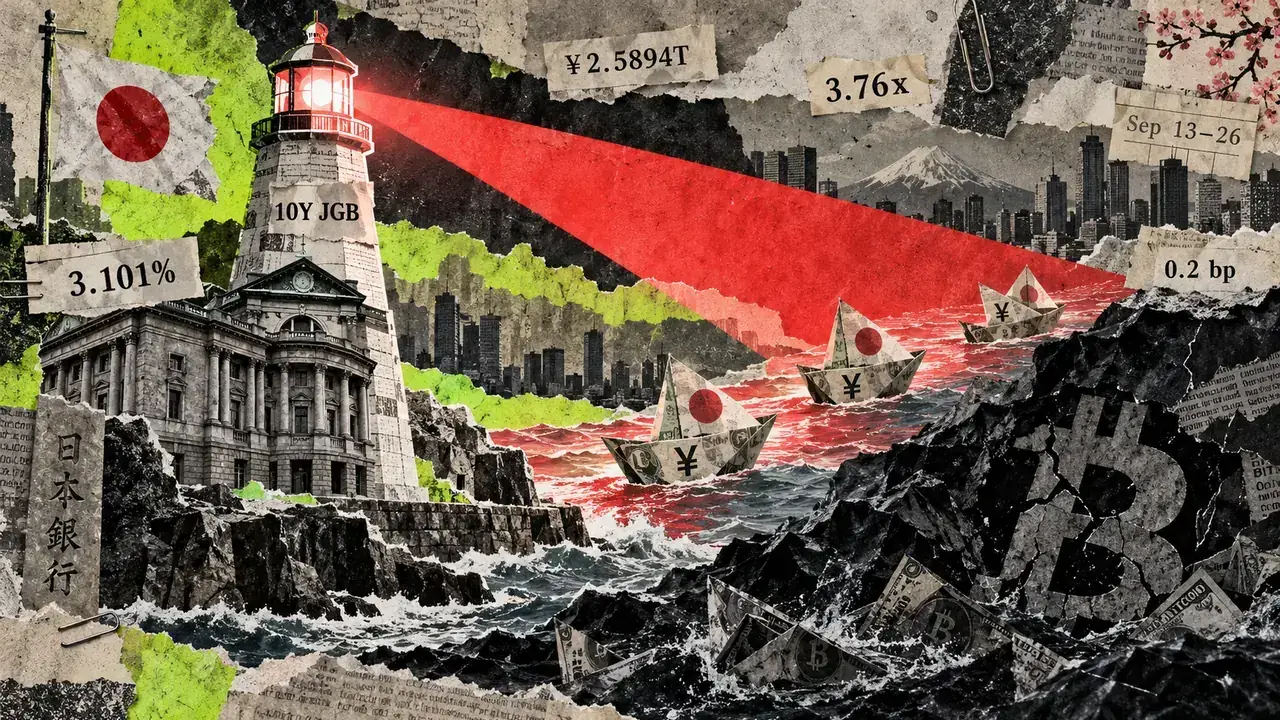
The Ministry of Finance’s result put the average yield up from 2.995% at the September 1 sale, an increase of 10.6 basis points. Competitive auction coverage, the amount sought by participants divided by the amount accepted, rose from about 3.29 times to 3.76 times.
The yield tail narrowed from 1.6 to 0.2 basis points. That gap measures the yield at the lowest accepted price against the average yield. Alongside the higher coverage, the smaller tail points to firmer demand at the higher yield.
The backdrop is two earlier weeks of foreign-debt selling. MOF’s October 1 flow release recorded net long-term debt sales of ¥1.9049 trillion during September 13–19 and ¥684.5 billion during September 20–26. Together, those weekly observations amount to net sales of ¥2.5894 trillion.
The series covers designated major Japan-resident reporting institutions and classifies foreign securities by issuer residence. It does not identify US Treasury sales, currency conversion, reinvestment into Japanese government bonds or Bitcoin transactions.
If Japanese institutions persistently prefer domestic bonds over overseas debt, reduced foreign bond demand could raise borrowing costs and weigh on capital available for risk-taking.
The authors of a Bank for International Settlements working paper identify global funding conditions and speculative motives as important drivers of cross-border Bitcoin and Ether flows.
Source link