The historical source estimated a CPI-window move, not a cash hedge premium or a directional forecast. Its volatility readings are not live quotes.
A pre-release Bitcoin options analysis estimated a 2.5% move for a window containing the November 10 US inflation report. Its comparison of past and expected volatility did not establish whether buying protection was cheap.
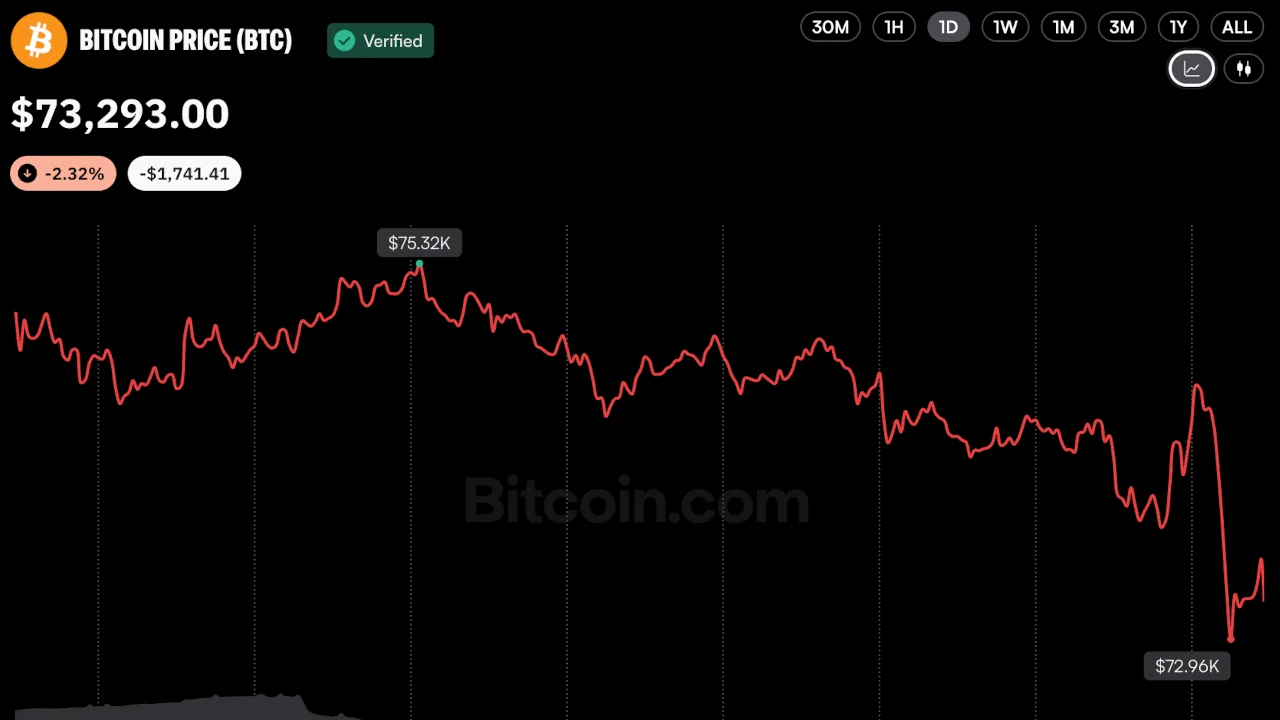
The analysis reports 3,183 BTC of long liquidations, approximately $245 million, on November 5 and another 2,450 BTC, approximately $181 million, on November 8. These are forced closures of bullish Bitcoin positions, rather than totals for the entire crypto market.
The study puts Bitcoin’s 30-day realized-volatility reading at 33.7 and Deribit’s DVOL index at 40, leaving a reported gap of 6.3 volatility points. These are the study’s readings, not live quotes. It does not document the realized measure’s annualization method, limiting how precisely it can be compared with annualized DVOL.
The observations concern the period before October’s Consumer Price Index release was scheduled for November 10 at 8:30 a.m. Eastern, or 13:30 UTC. They are not a post-release market update.
Realized volatility describes swings that have already happened. Deribit defines DVOL as a forward-looking, annualized measure covering the next 30 days. Its calculation draws on option prices at expiries on either side of that horizon and interpolates between them.
The two readings describe different stretches of time. A turbulent week can lift the backward-looking measure and bring it closer to implied volatility without demonstrating that the cash price of protection has fallen.
Source link