Across the U.S. healthcare market, reinsurance has long been a buffer against risk—providing a measure of stability in a volatile industry. Recent moves by three major reinsurance providers to exit or reposition offerings have sparked debate about stop-loss capacity and market disruption.
Less discussed is what these major market shake-ups reveal about the growing complexity of healthcare risk, which is becoming harder to predict, price, and manage using traditional methods. That creates new challenges for self-funded employers, brokers, stop-loss carriers, and reinsurers alike.
To adapt, stakeholders need stronger internal capabilities—supported by advanced analytics, AI, and richer data—to gain deeper visibility into the health of member populations today, and anticipate where risks may emerge in the future.
Reinsurance companies evaluate and absorb large-scale risk, so when major players signal increasing caution, it is indicative of a shift in the underlying market conditions. While each company that recently exited or reduced participation in the reinsurance market did so for different reasons, the overall market disruption highlights emerging trends making healthcare risk harder to predict:
Traditional actuarial models rely heavily on historical claims data. In a volatile and rapidly changing environment, that retrospective view can miss emerging exposure before it becomes catastrophic, increasing uncertainty around claims trends, pricing, and long-term exposure for stop-loss carriers and the employers and brokers who rely on them.
Three factors are especially important to highlight in understanding the recent reinsurance market shifts.
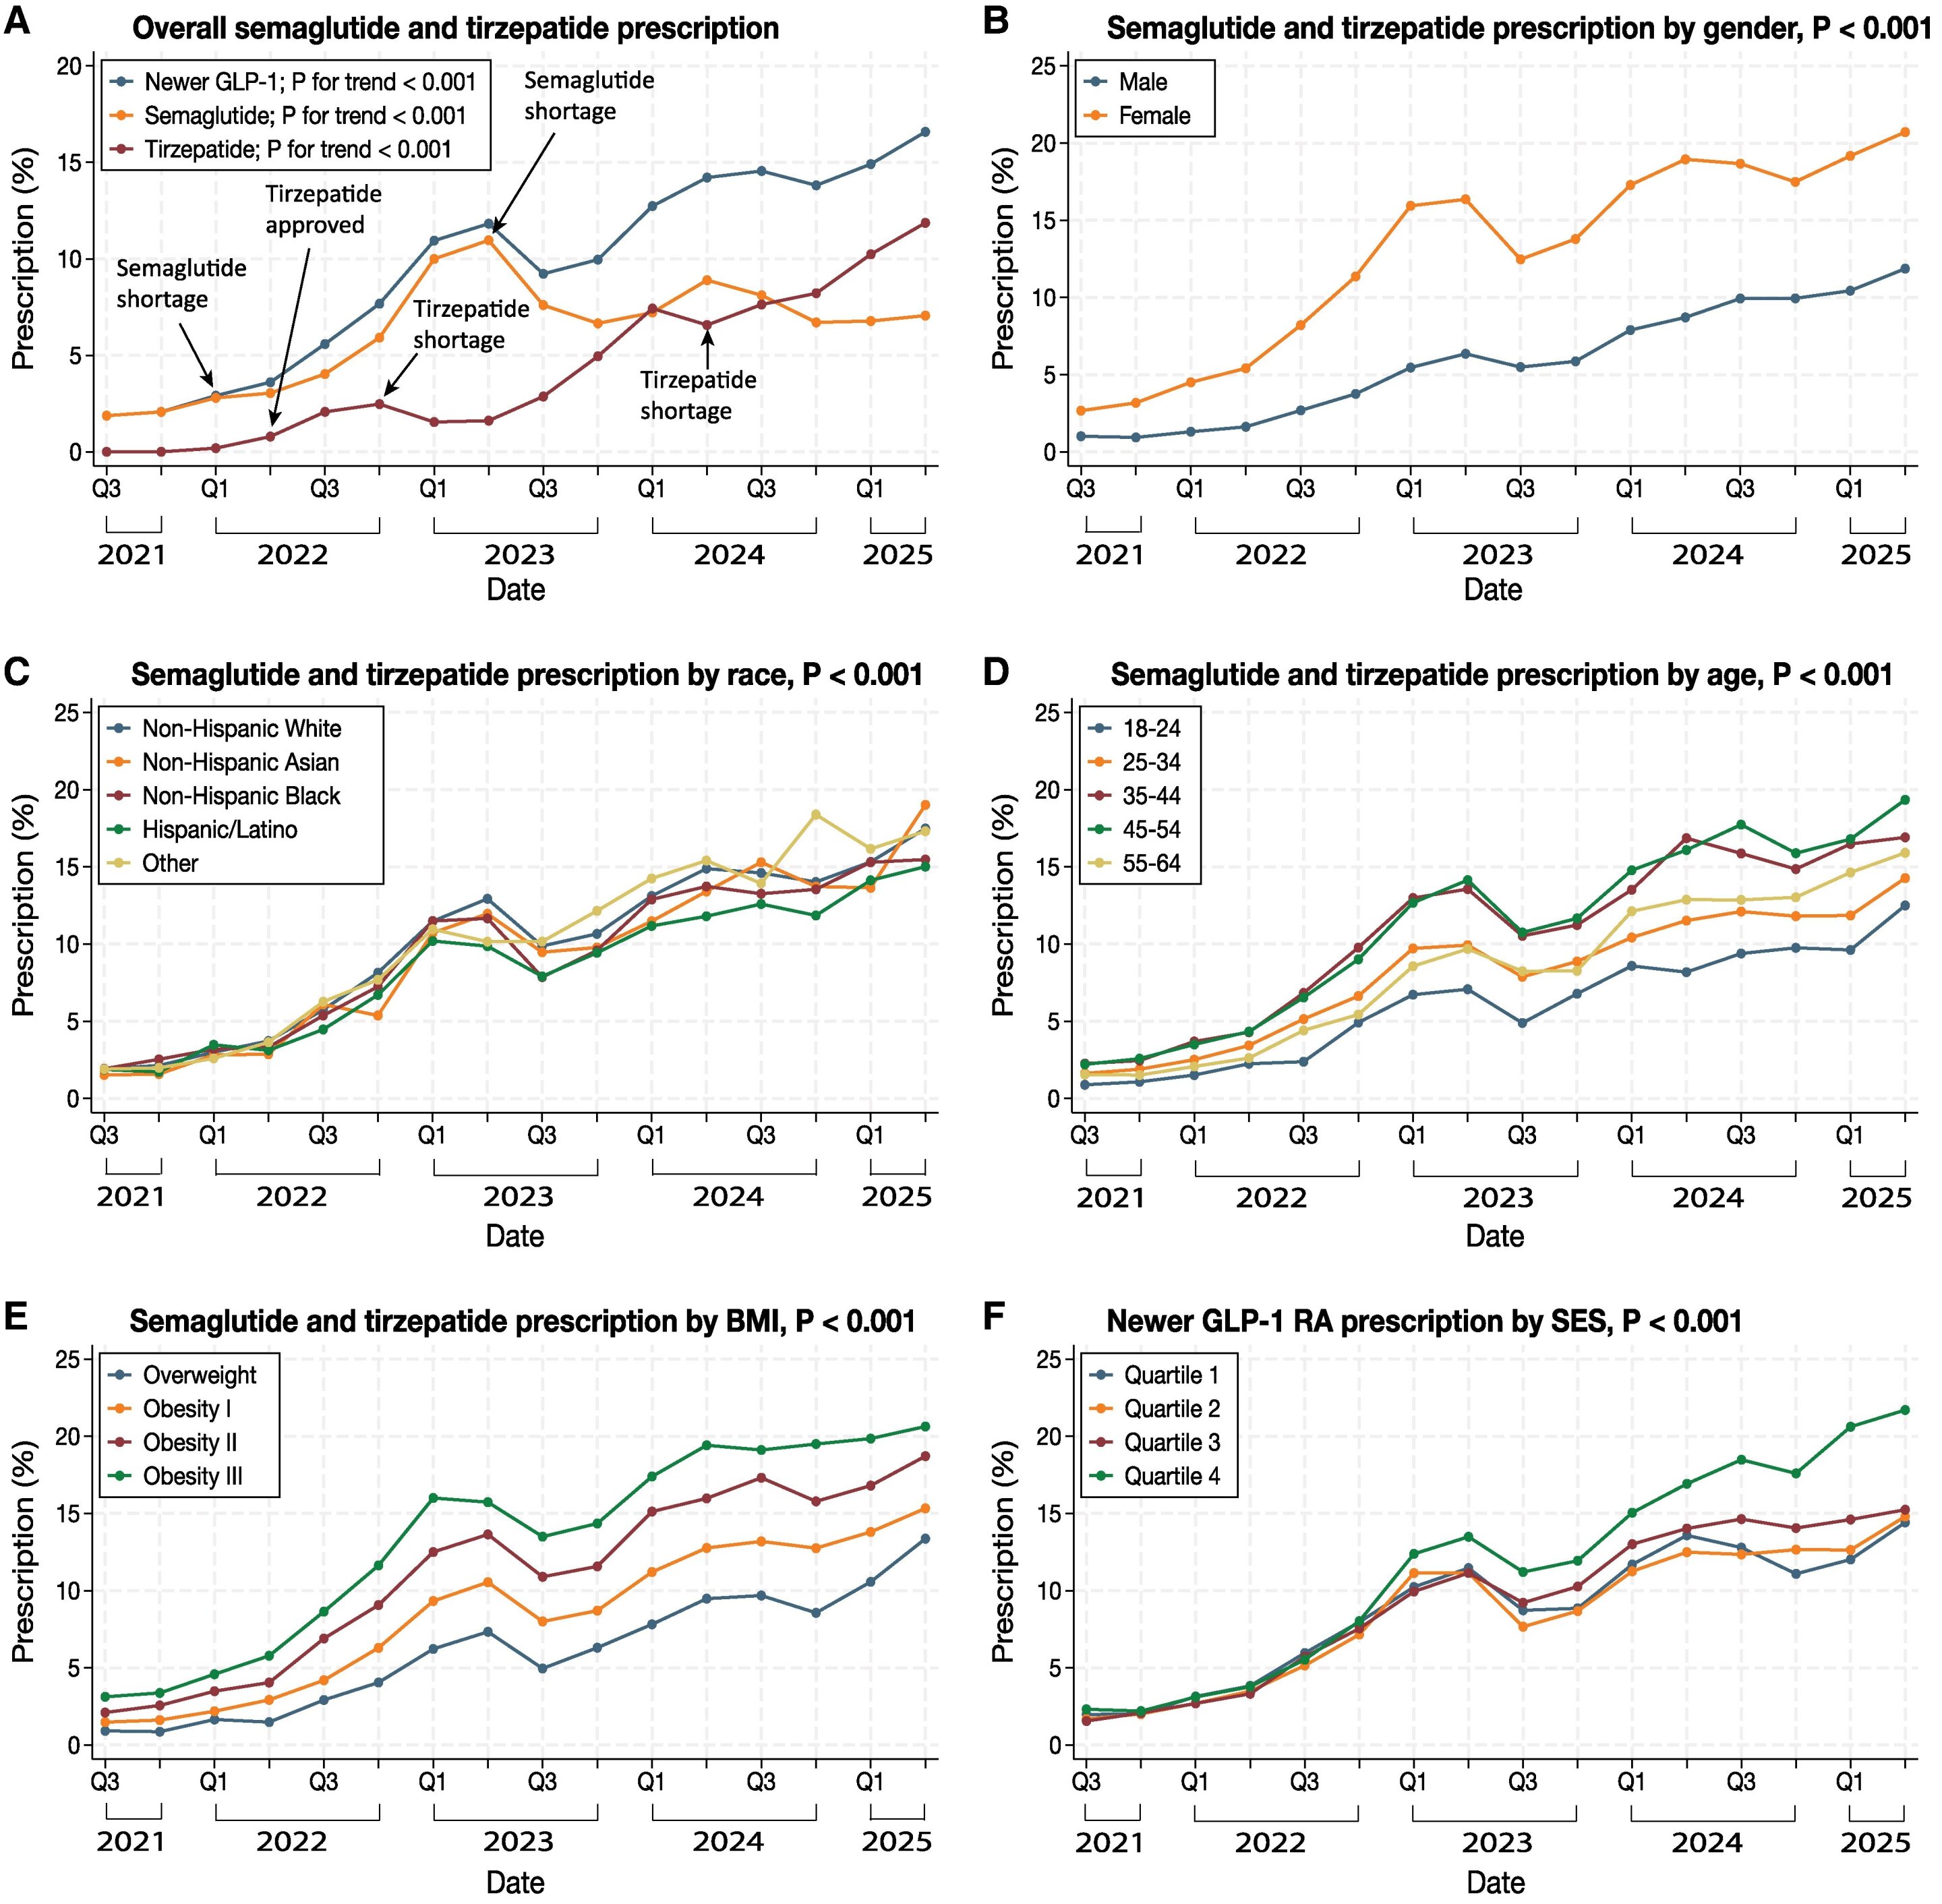
Specialty drugs are reshaping risk. High-cost drugs and specialized treatments such as gene therapies account for a disproportionate share of healthcare spending growth.
Source link