
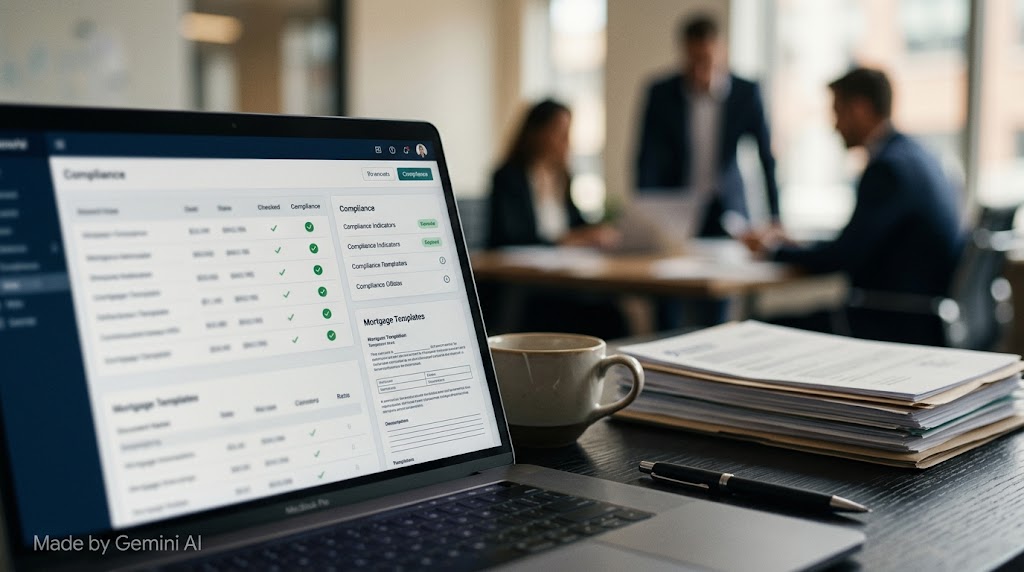
Curvestone ingests call transcripts, emails, WhatsApp and text messages, credit files and applicant data, then scores each file against the group’s internal policies as a case progresses. The four checks now live cover document completeness (what the platform calls shopping list validation), vulnerability assessment, Land Registry report review, and an advice suitability assessment that runs each case against more than 100 validation points. Each report is generated in approximately five minutes and cites the underlying evidence for every finding.
The deployment carries direct regulatory weight. The FCA‘s Consumer Duty, which came into full force in July 2023 and extended to closed products in July 2024, places explicit obligations on firms to identify and support vulnerable customers. The regulator has also recently completed a distribution review of the second charge mortgage market, with suitability rather than eligibility at the centre of its scrutiny. For a firm operating across 40 to 50 advisers, consistent vulnerability identification at the case level is no longer a best-practice aspiration; it is a compliance requirement with audit trail expectations attached.
Barney Drake , chief executive of Specialist Mortgage Group, said the previous approach to vulnerability assessment was handled at adviser level and maintaining consistency across the team was considerably harder. “Now it’s driven by our policy, and takes minutes to present all evidence to the advisor, who then makes the final call,” he said. Drake added that the cost of the platform is comparable to employing a person to carry out the same work, but that the output is consistent across every case.
Source link