
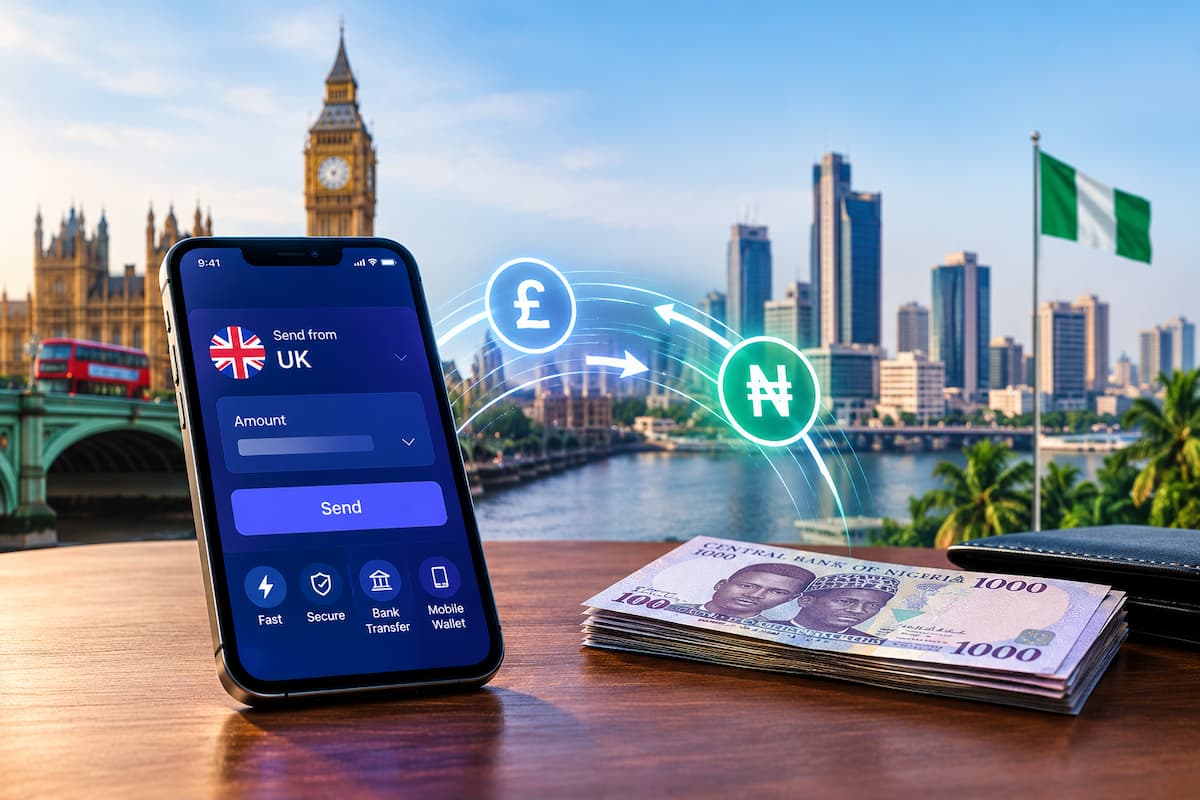
The corridor processes an estimated £2.8 billion annually, making it the largest cross-border payments channel between the UK and Africa and the third largest from the UK to any single country, according to data cited from the Migration Observatory at the University of Oxford.
Exchange rates remain the sharpest point of differentiation. An analysis of more than 37,000 matched price comparisons, drawn from aggregator platform BestRates and covering January 2025 to August 2026, found that Africhange delivered higher GBP-to-NGN payout quotes than LemFi in over 90% of instances, averaging an additional NGN 12.69 per pound sterling.
The analysis cautions, however, that static historical comparisons capture only part of the picture, given that live FX rates shift throughout the trading day. Fee structures also vary: Africhange and LemFi both operate zero-transfer-fee models, while NALA uses a hybrid approach, charging a flat £0.99 fee on direct bank payouts and waiving fees on mobile-money channels.
LemFi’s competitive response rests on institutional scale rather than spot-rate aggression. Backed by a $53 million Series B completed in early 2025, the company reported crossing two million global users and processing approximately $1 billion in monthly transaction volume. NALA, meanwhile, serves more than one million users across 35 countries, with a pan-African coverage model targeting both consumer remittances and cross-border business payments.
All three operators are pursuing product expansion that goes well beyond the transfer itself. Africhange has partnered with UK-licensed bank Griffin to offer customers dedicated GBP current accounts with individual sort codes and account numbers.
Source link