
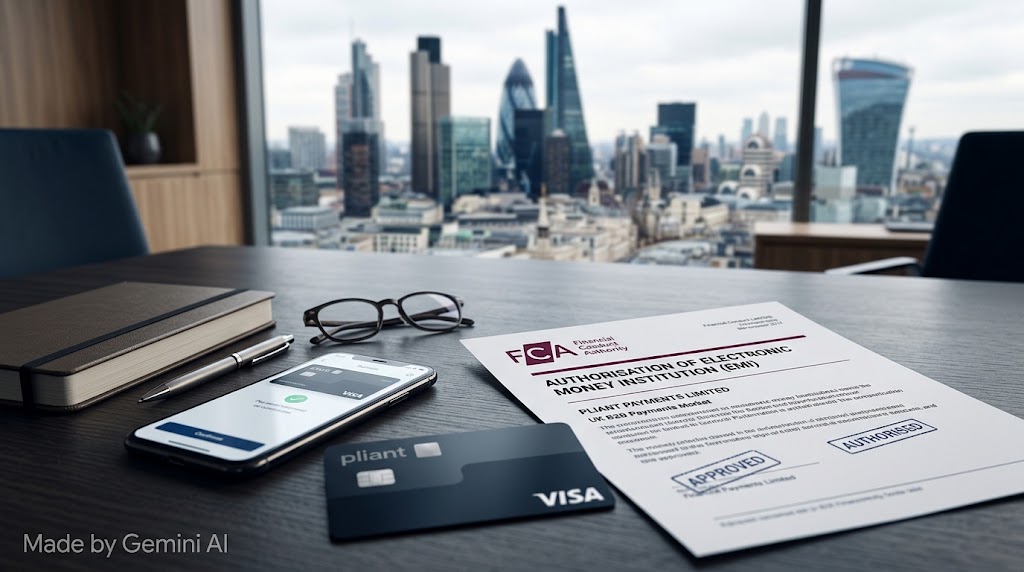
The milestone closes a structural gap in Pliant’s UK market position. The company had previously operated in the UK through its Finnish subsidiary, a common bridging arrangement among European fintechs that hold an EU e-money licence but have not yet secured a post-Brexit UK authorisation of their own. That arrangement provides market access but limits commercial independence: contractual relationships, safeguarding obligations and product structuring are all routed through an entity incorporated in a different jurisdiction, which can slow product iteration and add friction for regulated UK counterparties such as banks and public-sector bodies.
Malte Rau, chief executive and co-founder of Pliant, said: “This authorisation gives us greater independence and flexibility to serve UK customers directly. It also puts us in a stronger position to bring our technology to more businesses, financial institutions and public-sector organisations as we continue to expand our capabilities and reach.”
As an authorised EMI, Pliant Payments Limited can issue e-money, hold client funds under the FCA’s safeguarding regime, and build payment programmes for corporate customers without relying on a third-party licensed entity in the UK. For a platform that positions itself as infrastructure for fintechs, software platforms and banks building their own commercial card and payment offerings, holding a UK licence is a commercial pre-condition rather than a regulatory nicety. Regulated financial institutions conducting due diligence on a vendor typically require the vendor to carry its own local licence rather than passport from elsewhere.
Pliant’s broader product stack covers commercial card issuing, payment accounts, foreign exchange and spend management.
Source link