A hub migration can begin with one rail and expand in stages.
Tested controls and payment visibility must precede the transfer of customer activity.
Complete the form to unlock this article and enjoy unlimited free access to all PYMNTS content — no additional logins required.
A commercial customer asked its bank for a direct connection to instant payments and encountered an 18-month wait.
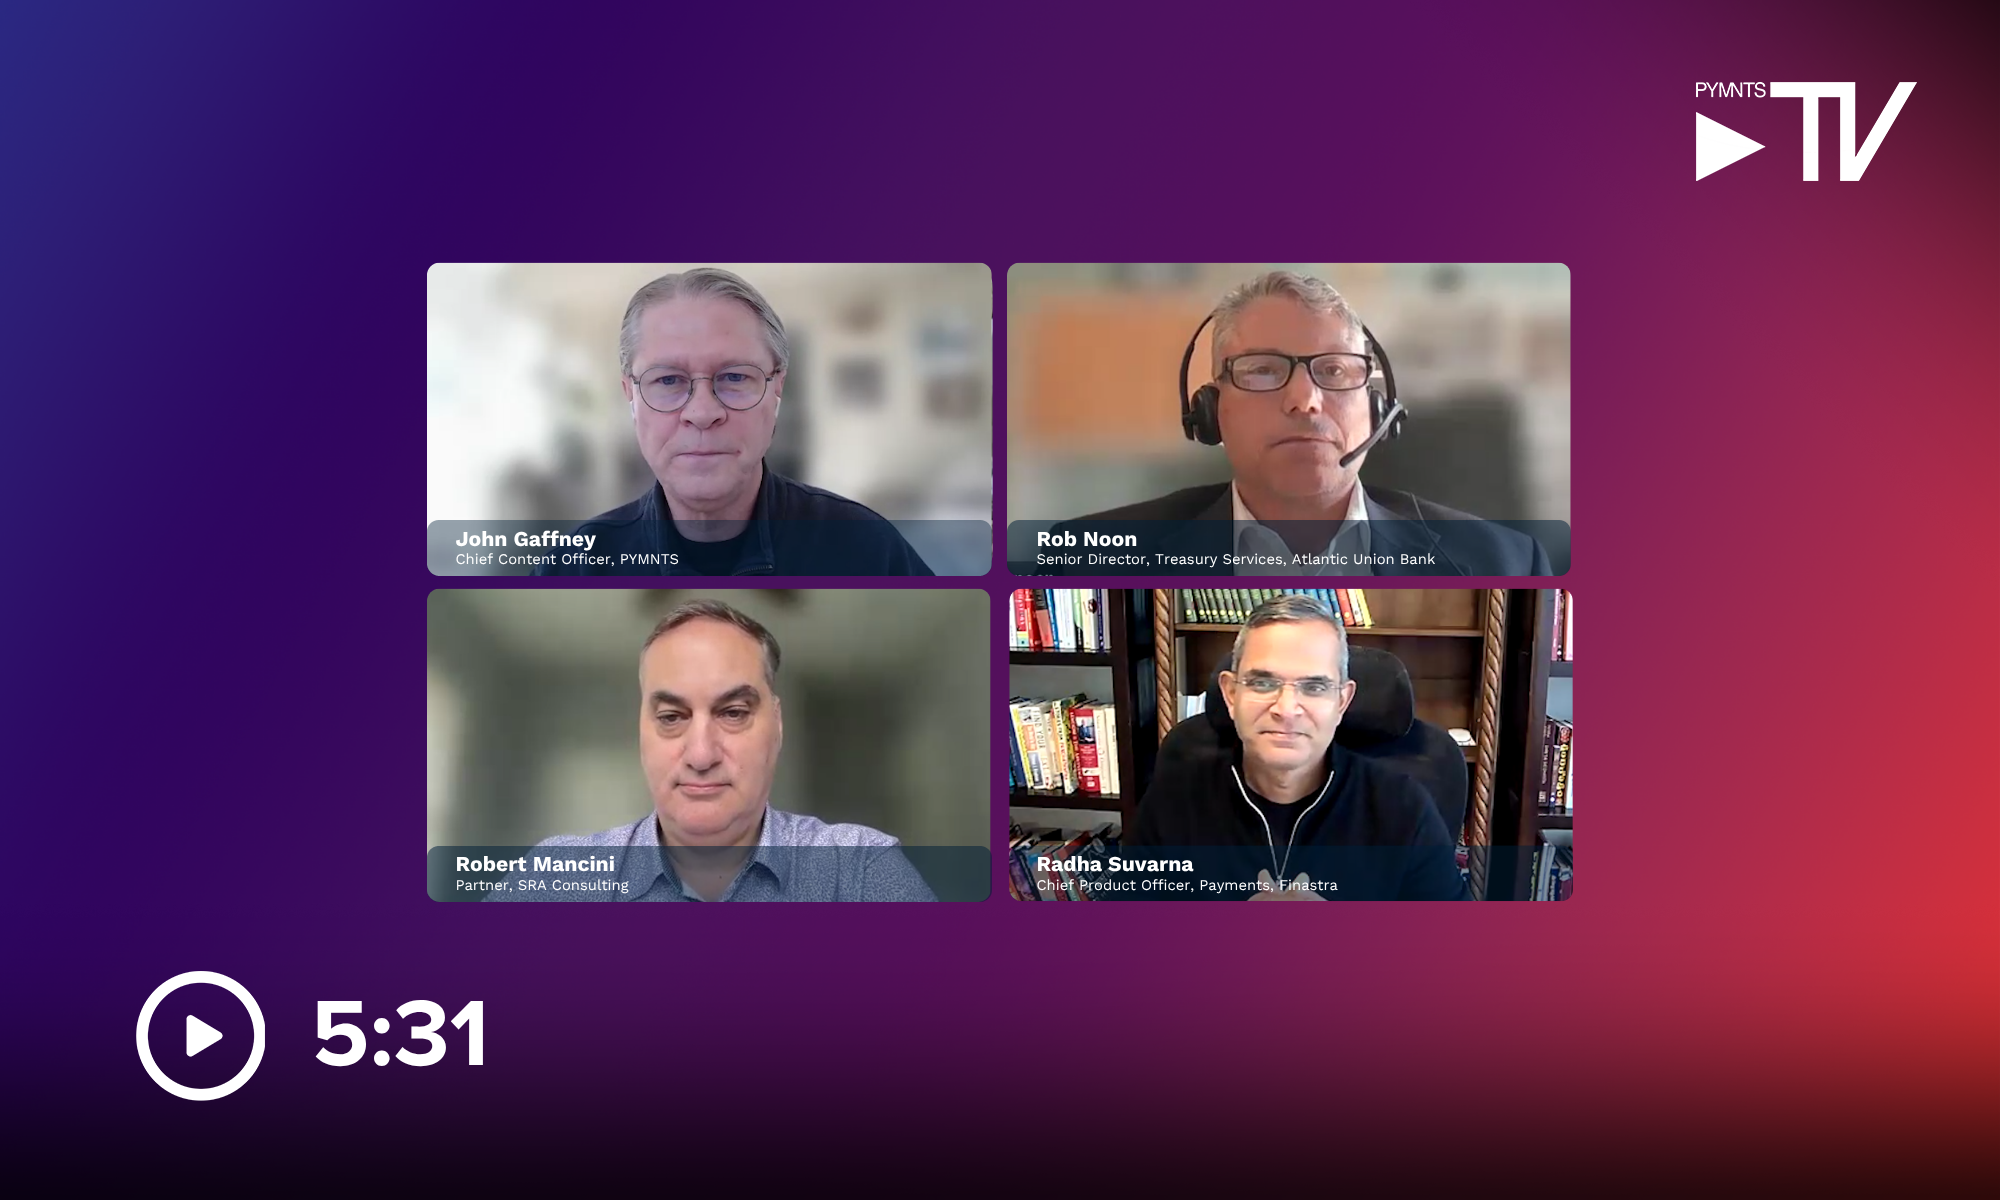
The bank needed to rebuild its architecture before onboarding the client, Robert Mancini, partner at SRA Consulting, recalled during a PYMNTS On Air discussion. The customer was ready to transact; the bank’s systems couldn’t accommodate the request.
“Modernization means you can say yes to your customer’s next ask fast without a two-year project,” Mancini told PYMNTS.
Joining Mancini were Radha Suvarna, chief product officer for payments at Finastra, and Rob Noon, senior director of treasury services at Atlantic Union Bank. The wide-ranging discussion examined how banks can move from separate applications for individual rails toward a payment hub, with common functions for routing, controls and operations.
A bank can complete its scheduled upgrades and still lack the connections needed to accept new business. Management must then approve another project before the customer can use the service.
Customer expectations start with an accessible interface and extend through every step required to move money, Noon said.
“Over the years, banks invested in the ‘front door’ to the organization, the client-facing applications,” Noon said.
A simple digital experience carries an operational commitment. A business submitting payroll needs its employees paid on time, regardless of how many applications process the instructions behind the screen.
Source link