SpaceX reported its third-quarter 2026 financial results on October 20, posting the company’s first solidly profitable quarter since going public earlier in the year under the ticker $SPCX.
Revenue reached $14.58 billion, up 161 percent year-over-year from $5.6 billion, and well ahead of consensus estimates in the $12.7 to $12.9 billion range. The results highlight a rapid shift in SpaceX’s center of gravity toward artificial intelligence/super intelligence, while Starlink and traditional space operations continue to show robust progress.
The AI/SI segment generated $7.56 billion in revenue, an 830 percent year-over-year increase, making it the company’s largest segment for the first time. Growth was primarily driven by the activation of major cloud services agreements, the integration of Cursor (acquired earlier in 2026), and rising usage of Grok models and the newly introduced Grok Bot personal agent.
Revenue $14.58B (+161% YoY) vs. consensus ~$12.7–12.9B
Adjusted EBITDA $8.8B (+306% YoY)
GAAP net income $4.4B (vs. prior-year loss; first solidly profitable quarter post-IPO)
Adjusted EPS ~$0.35 vs. ~$0.13–0.16 expected
Super Intelligence (SI, formerly AI): $7.56B (+830% YoY) — now the largest segment, driven by cloud contracts, Cursor, and Grok.
Connectivity (Starlink): $5.25B (+69% YoY).
Space: $1.77B.
Starlink subscribers: 13.6M (+89% YoY).
Nameplate compute: 1.7 GW.
Capex: $19.6B (majority AI infrastructure).
Cash & marketable securities: ~$90B.
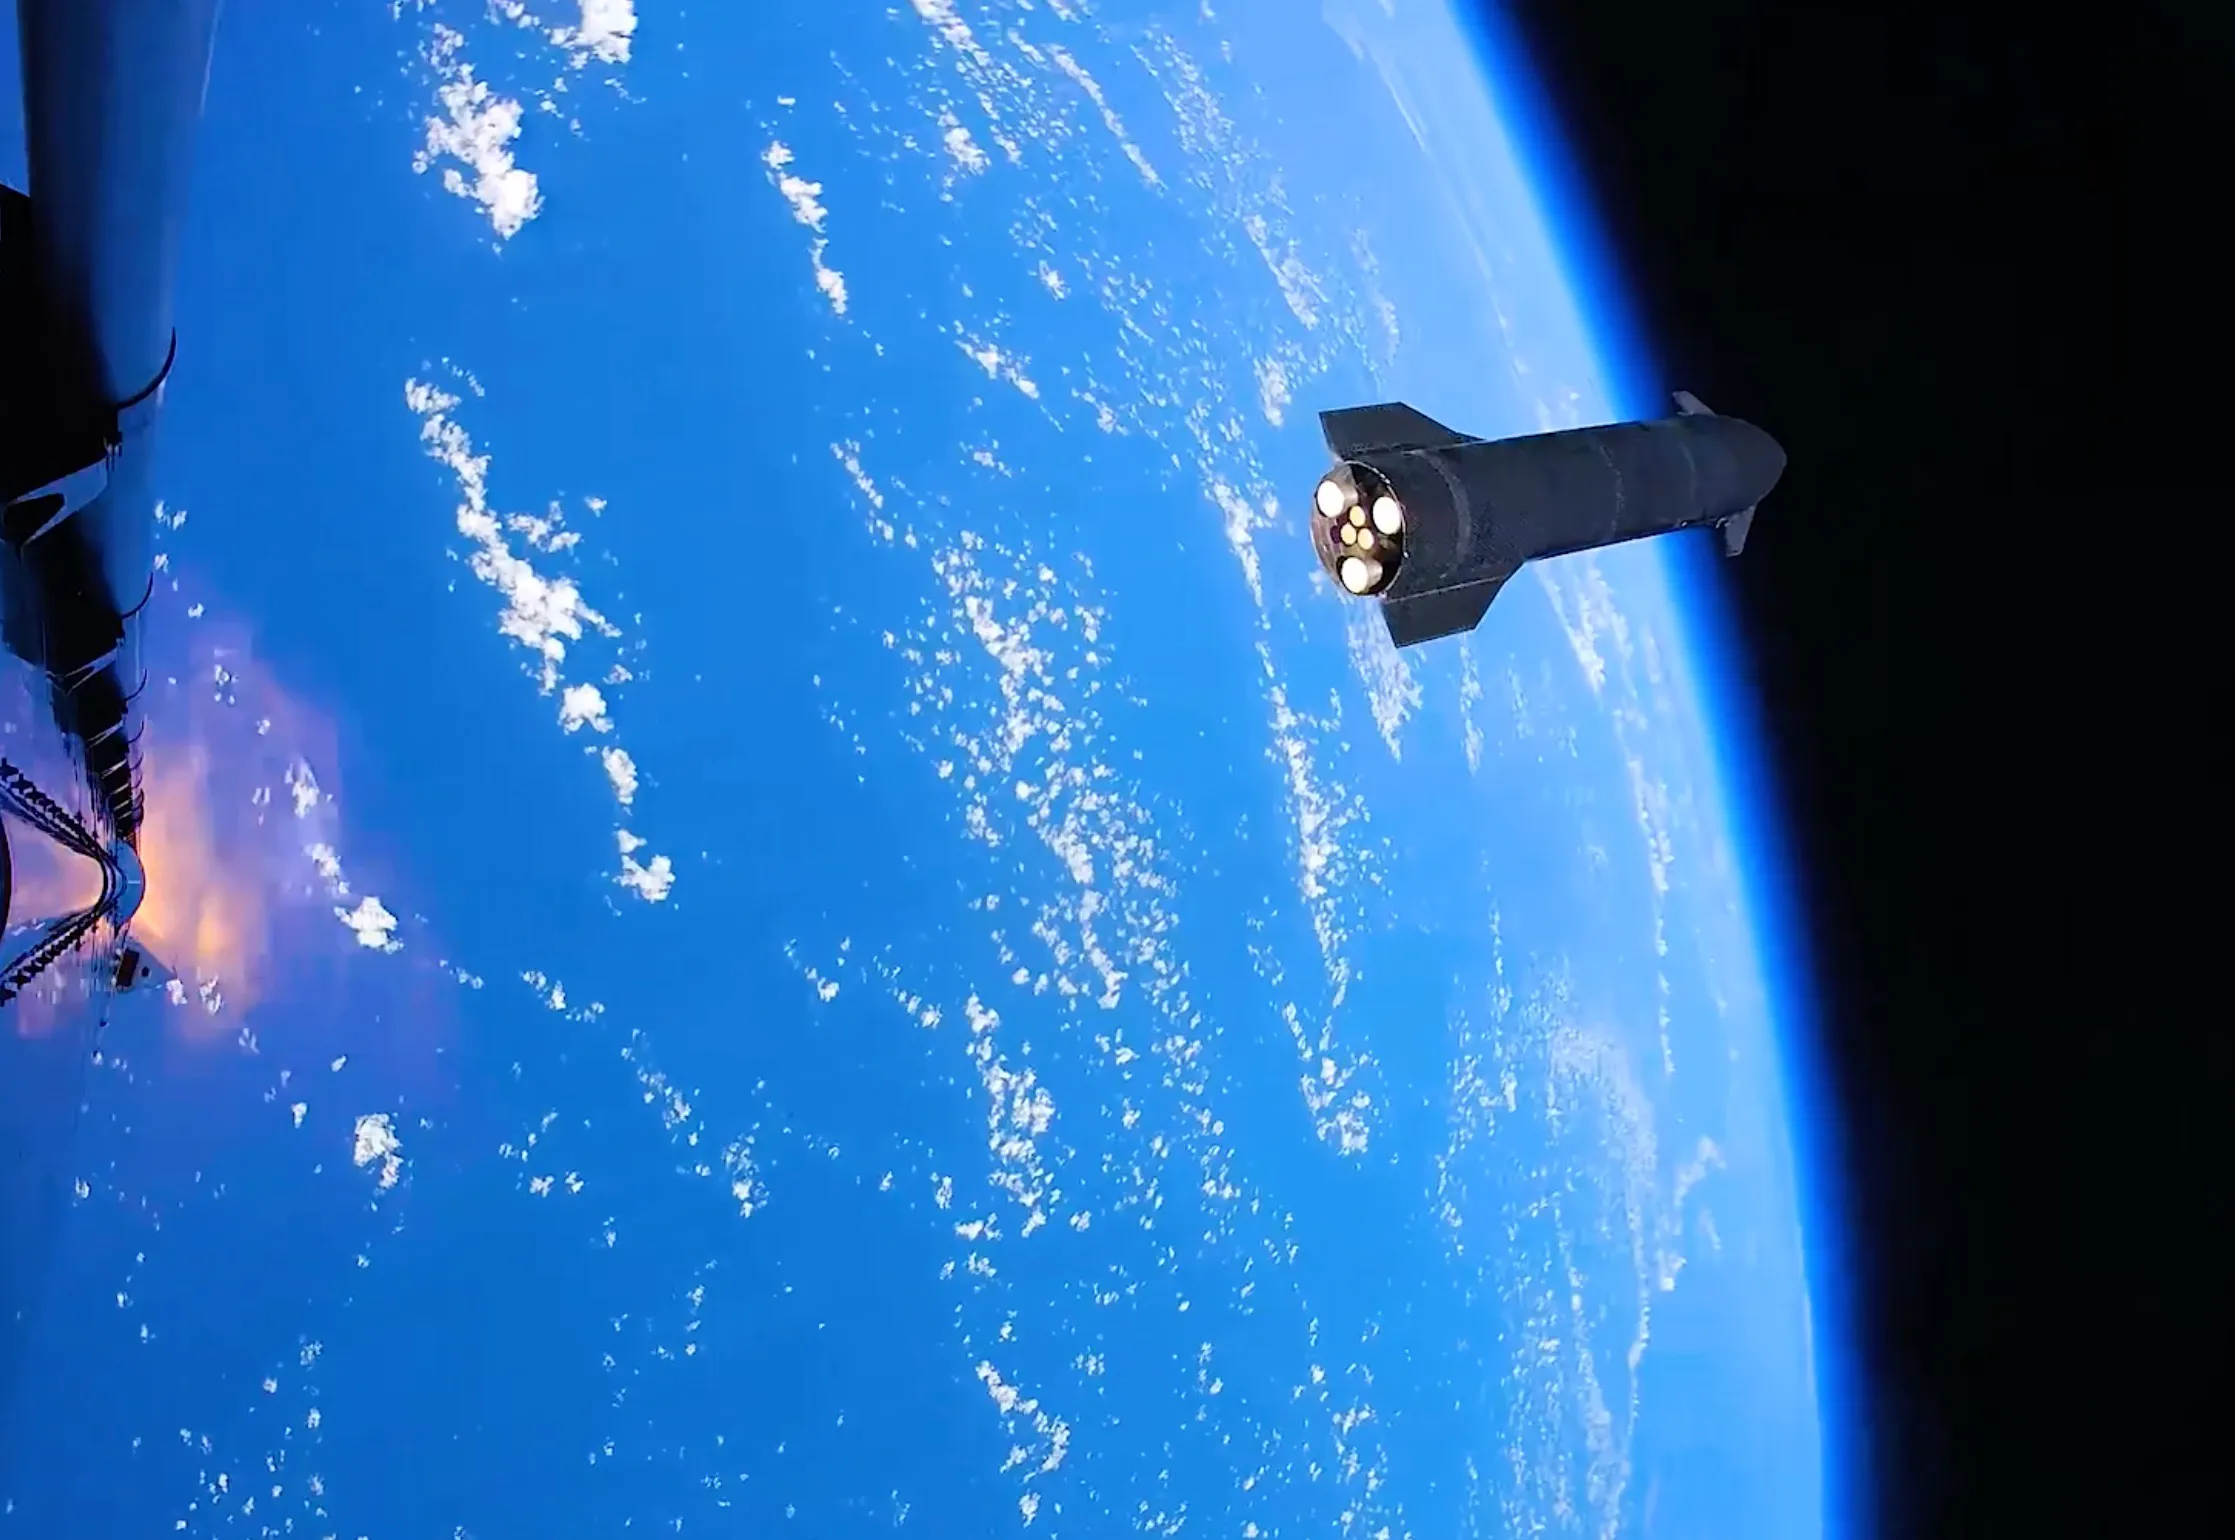
First revenue-generating Starship mission (26 V3 Starlink satellites, ~10× Falcon 9 downlink capacity per launch).
6 GW a year earlier. 6 billion, with the majority allocated to AI infrastructure, including continued expansion of the Colossus facilities.
Source link