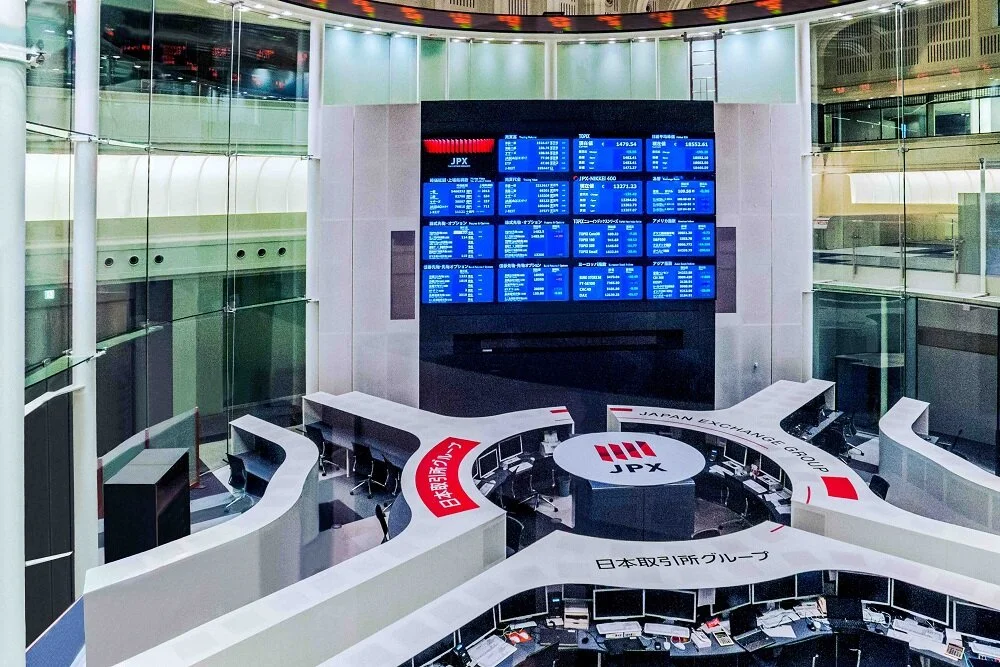
Tokyo Financial Exchange will introduce a futures contract tied to the Bank of Japan’s overnight call rate this month. The contract targets traders hedging volatility between policy meetings. Last month, the central bank lifted its benchmark rate to a 31-year high of 1.25 percent. That was its second increase this year.
Faster rate adjustments broke the central bank’s previous pattern of six-month pauses between increases. The new contract allows financial institutions and corporate treasuries to hedge specific policy meeting outcomes. They no longer have to rely on wider quarterly averages.
Trading in the exchange’s existing three-month Tokyo Overnight Average Rate (TONA) futures failed to match market needs during recent policy shifts. Volume in that contract fell nearly 50 percent in September compared to the same month a year earlier, the exchange reported.
Market participants faced mismatch risks under the three-month design when pricing rate hikes scheduled weeks apart. “Interest rate moves have become more active lately, and there is an increase in demand for derivatives trading,” said Ryosuke Seo, a director in the wholesale business department at the Tokyo Financial Exchange.
Both Tokyo Financial Exchange and Osaka Exchange, a unit of Japan Exchange Group, launched three-month TONA contracts in 2023 ahead of the central bank’s exit from negative interest rates. Neither venue took decisive liquidity away from private dealer networks.
Over-the-counter overnight index swaps remain the primary competition because they allow customized maturities matched directly to meeting dates. Notional volume in yen overnight index swaps extending out past 30 years reached a record high last month, according to Japan Securities Clearing Corp data.
Source link