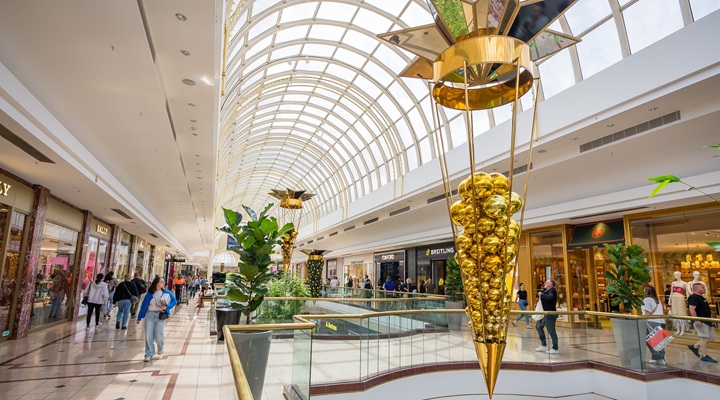
Australians are continuing to spend at shopping centres despite cost-of-living pressures and stretched household budgets, new Urbis data reveals.
The Urbis Shopping Centre Benchmarks draws on data from 516 Australian shopping centres, spanning neighbourhood centres through to major CBD and super-regional destinations. It represents 14.6 million sqm of gross leasable area, $118.8 billion in reported turnover and 46,743 tenants.
Analysis of comparable centres between 2025 and 2026 reveals a return to more stable trading conditions following several years of disruption and cost-of-living pressure, but with increasingly different growth patterns emerging across locations and centre types.
Food catering and food retail were the standout category growth drivers across all centre classes, increasing by 7.5 per cent and 6.9 per cent year-on-year, respectively.
Other significant growth categories for shopping centres were jewellery, which grew 11.6 per cent, and entertainment and retail services, up 8.8 per cent and 6.2 per cent, respectively.
Non-food mini-majors also performed strongly, with retail sales up 7 per cent, as retailers such as Uniqlo fill space traditionally occupied by department stores.
Urbis director Ian Shimmin said tenancy mixes are changing alongside consumer needs.
“The shift towards experiences and in-centre consumption also highlights the growing social role of shopping precincts and is helping centres remain resilient as e-commerce continues to expand,” he added.
CBD centres delivered the strongest retail sales growth at 7.1 per cent, while super-regional centres recorded a 5 per cent uplift.
9 per cent. Shimmin said mortgage pressures are influencing household spending in these areas.
Source link