China’s polysilicon output fell to around 105,000 metric tons (MT) in October, according to the Silicon Branch of the China Nonferrous Metals Industry Association. This was down from 120,400 MT in September, following three consecutive months of growth. Industry sources expect monthly output to decline to around 80,000 MT from December through February, reflecting deeper production cuts and Lunar New Year-related shutdowns. This would align with production-control targets and the minimum operating level existing producers can sustain.
Tighter supply expectations have supported a gradual polysilicon price recovery. The China Mono Premium assessment stood at CNY 38.786 ($5.80)/kg, or CNY 0.081/Wp, on Oct. 13, according to OPIS, up 21.6% from its year-to-date low in July and at its highest level since the second quarter began. However, actual transactions are still limited. Market sources said higher-priced deals mainly involved export-linked production or special commercial arrangements, such as suppliers selling polysilicon to long-term customers and subsequently purchasing wafers from them.
Producers have pushed for prices closer to the estimated full production cost of around CNY 43/kg, but downstream buyers continue to resist higher offers. Inventory reduction, sustained production discipline and stronger prices across downstream PV products will be needed to support a more durable recovery.
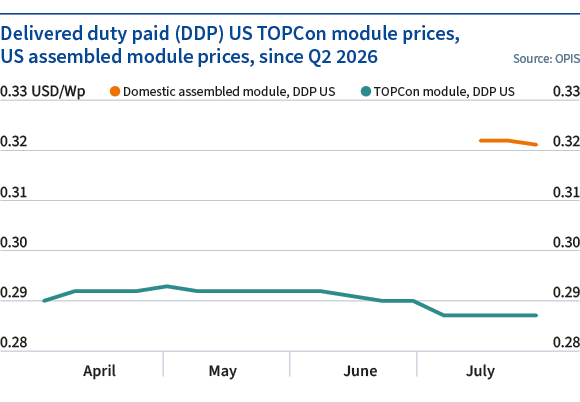
The disconnect between upstream costs and downstream pricing is particularly evident in the module market. 703/Wp on Oct. 698/Wp recorded in early August. 108/Wp in September.
Source link