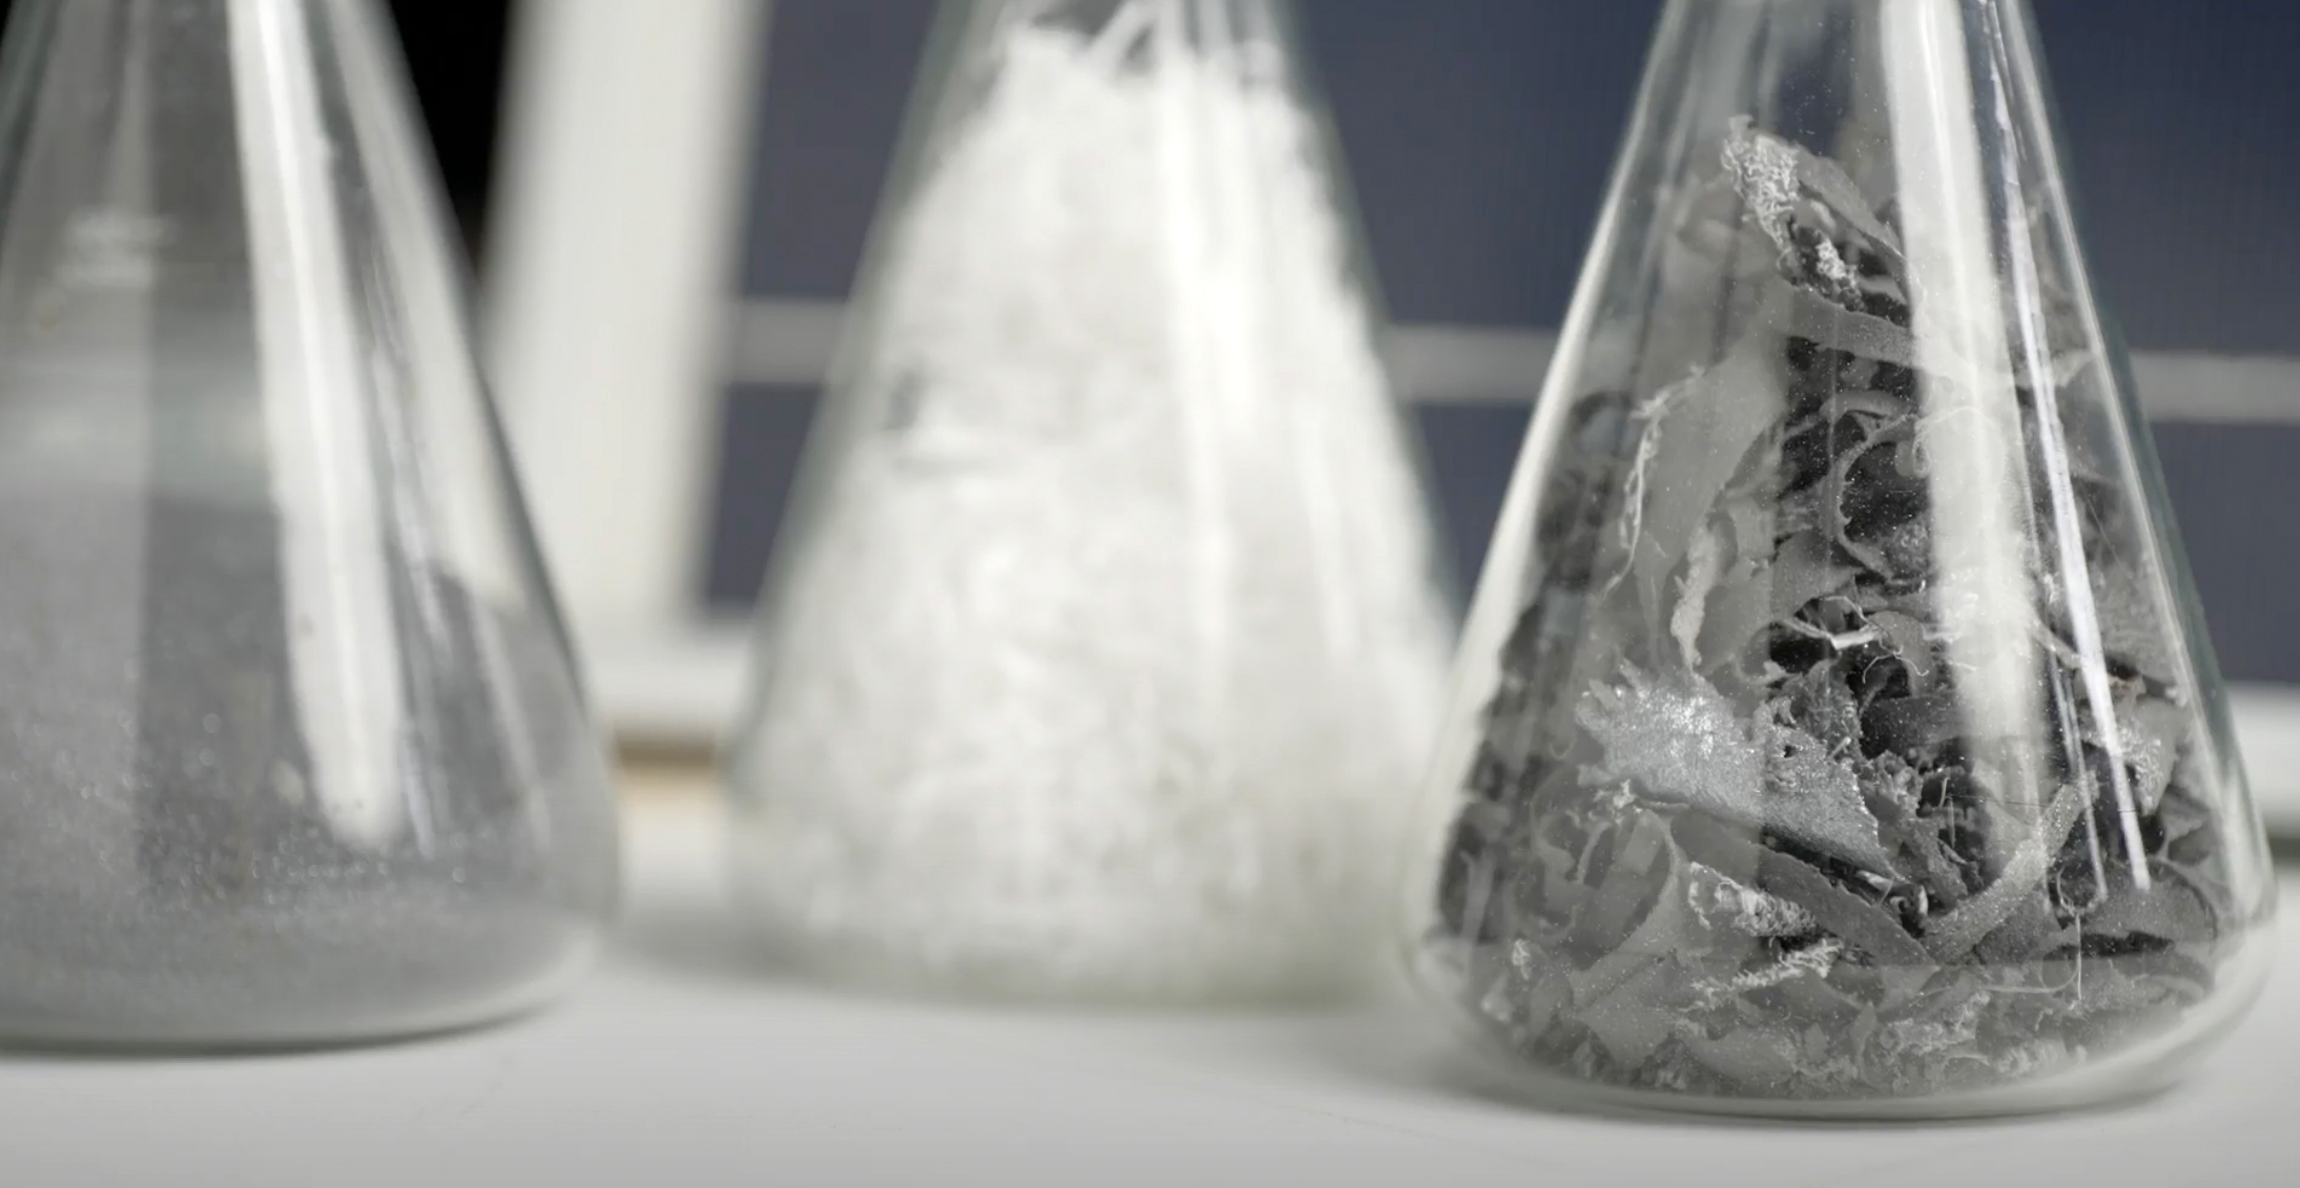
Every new terawatt of PV has a physical footprint. It requires tons of silicon and glass, kilometers of copper cable, and much smaller – but potentially more critical – quantities of silver, indium and tin. Those material flows have become enormous as global PV capacity has tripled from 1 TW in 2022 to today’s 3 TW and continues to move toward several tens of terawatts.
How enormous depends on where solar deployment eventually ends up. Scenarios examined in a new IEA-PVPS analysis range from 29 TW to 75 TW of silicon-based PV by 2050, with 29 TW and 63 TW representing the study’s main low- and high-deployment pathways
Such growth raises an uncomfortable question: can material supply keep up? The answer is more interesting than a simple “yes” or “no.” Some materials could indeed come under considerable pressure, but PV technology is not standing still. Cells are becoming more efficient, wafers thinner, silver contacts narrower, and material substitution more widespread. At the same time, an enormous stock of materials is accumulating in PV systems that will eventually become available for recycling.
“PV in 2050 will not look like PV today. PV material compositions will change in the race to make PV electricity even more cost effective and sustainable” said Rutger Schlatmann, chair of the European Technology and Innovation Platform (ETIP) PV.
Rather than assuming a fixed amount of material for every watt installed until 2050, researchers model a PV industry in continuous development. A key basis for this is the International Technology Roadmap for Photovoltaics (ITRPV), coordinated by German engineering industry association VDMA, which tracks expectations for the development of crystalline-silicon PV.
Source link