Gevo’s $70 million tax credit sale illustrates how carbon capture can support the economics of low-carbon fuel production.
The renewable fuels company said it had contracted to sell substantially all its expected 2026 Section 45Z credits generated by ethanol and renewable natural gas operations.
The announcement highlights a route to monetizing emissions reductions through federal incentives, although the transaction itself is not a sale of captured carbon.
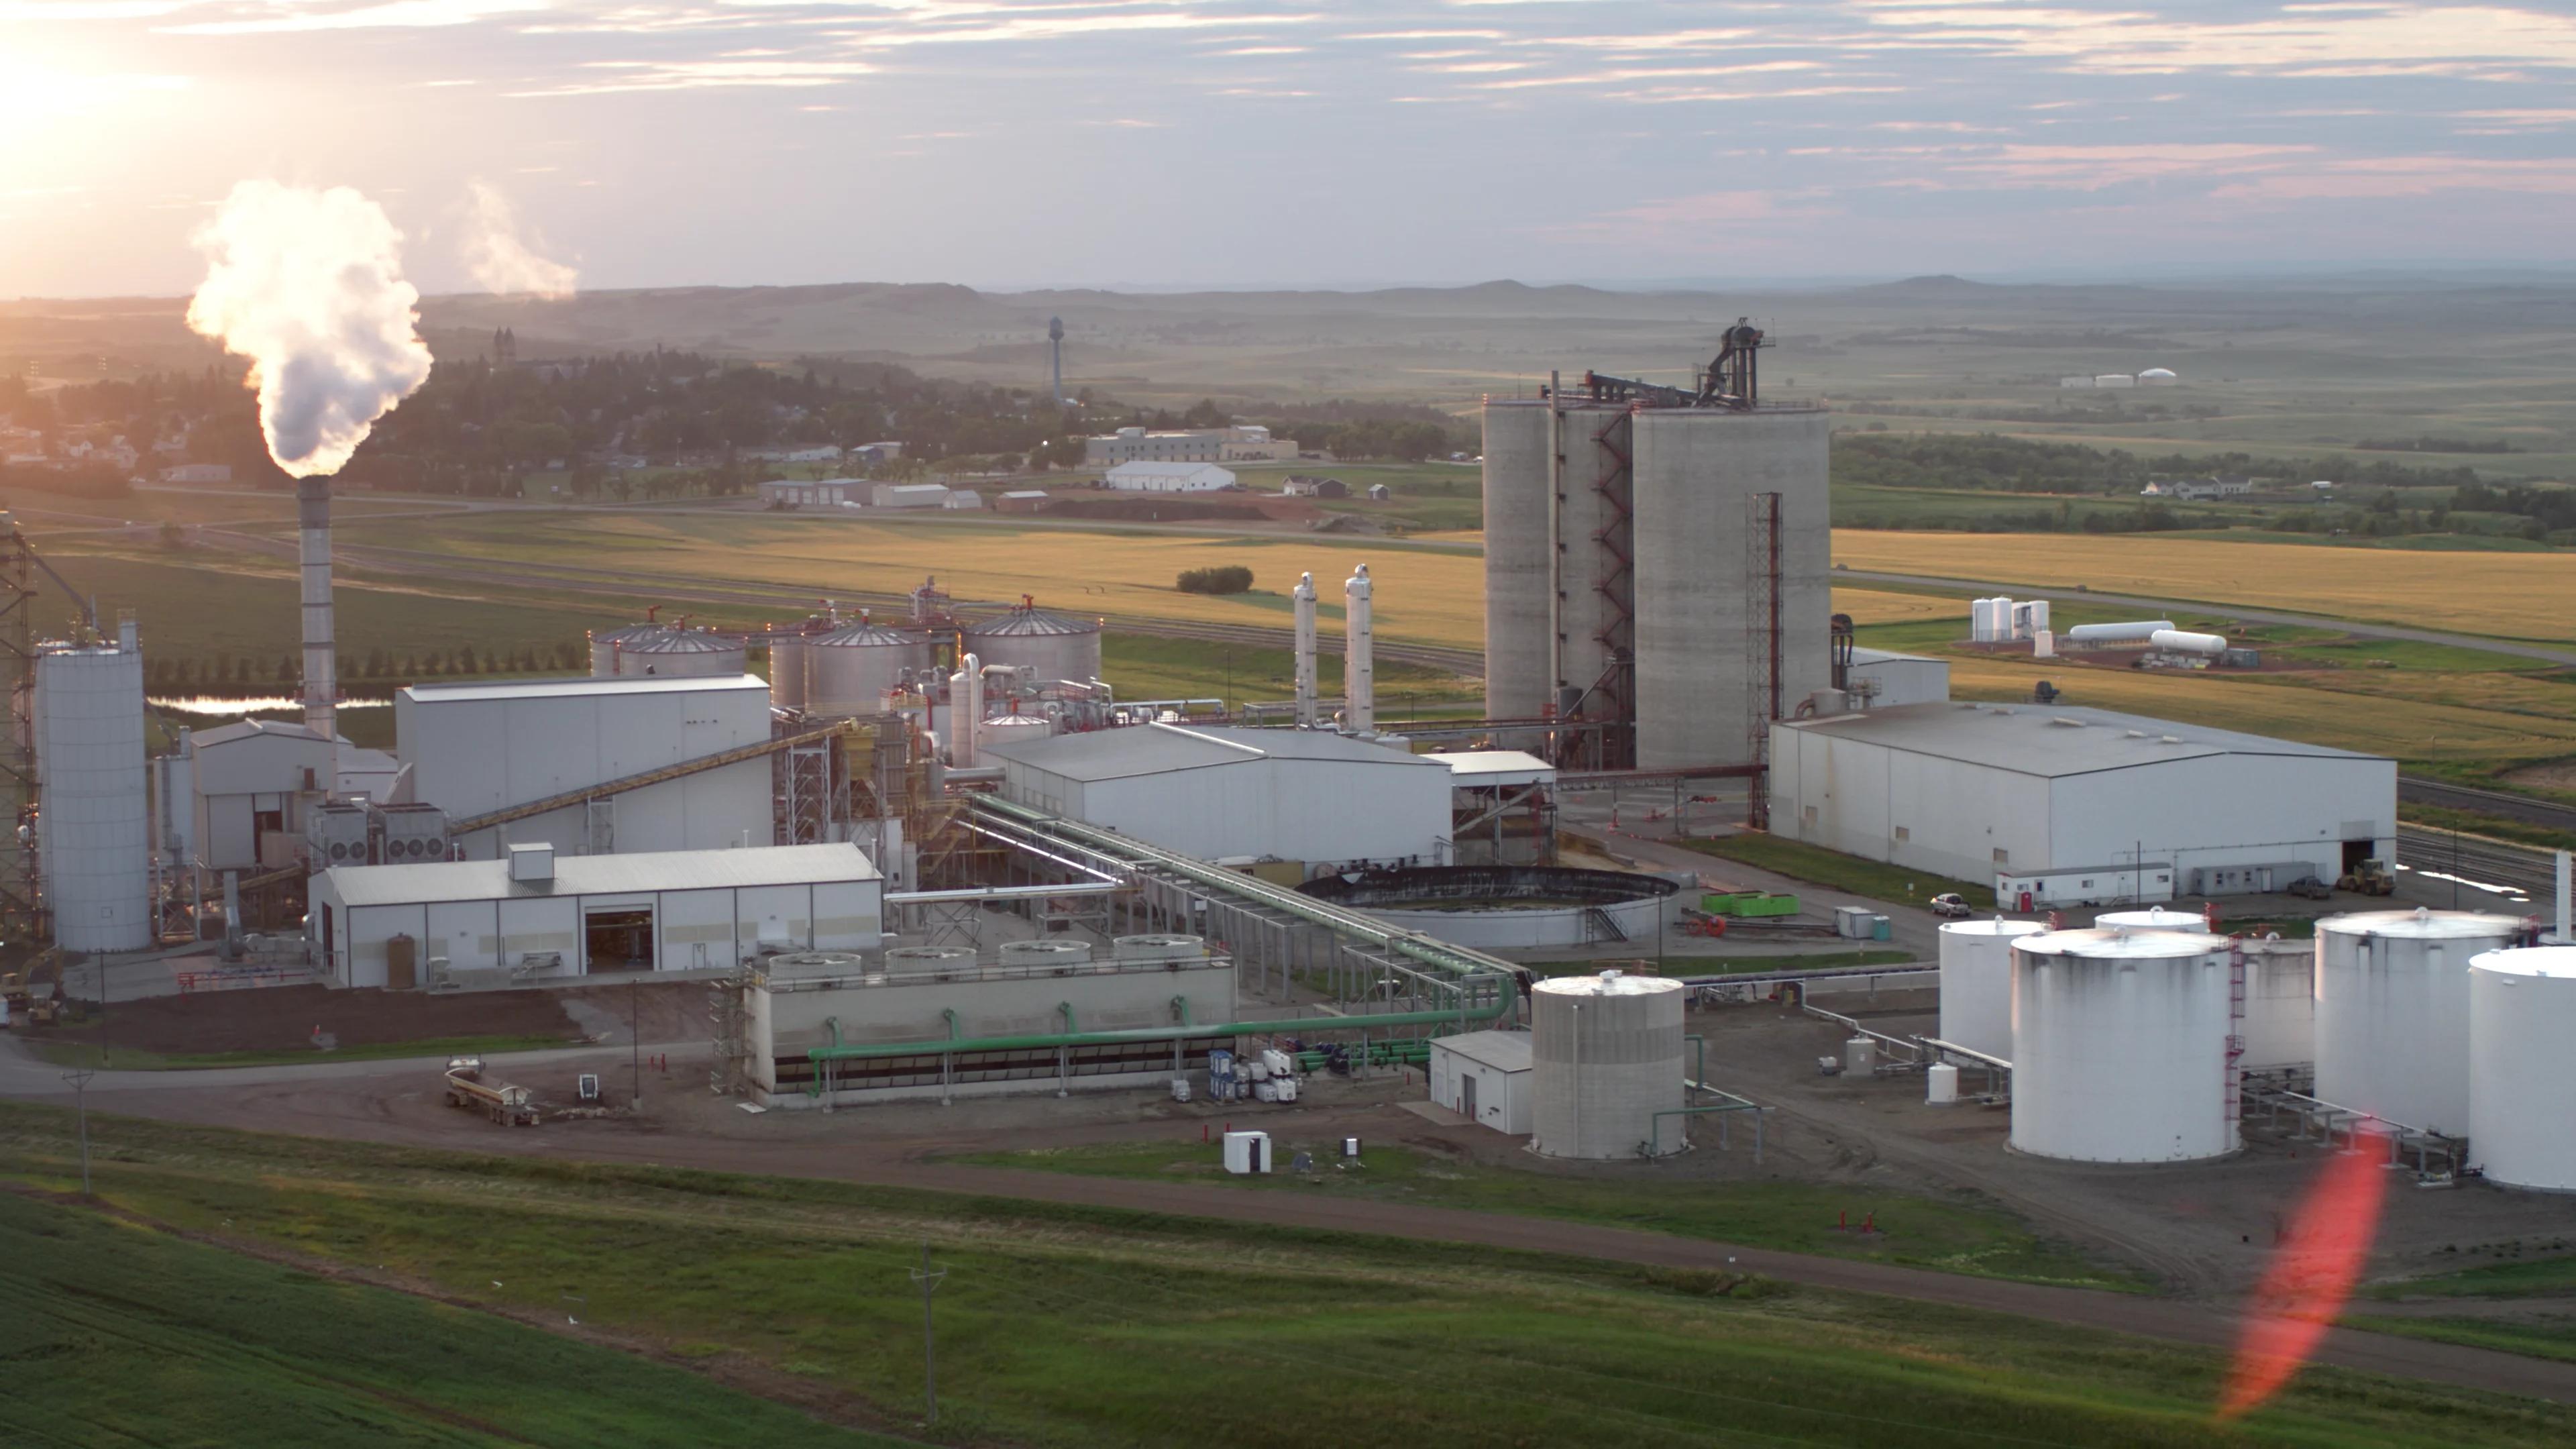
Gevo operates an ethanol plant alongside a carbon capture and storage facility in North Dakota. Capturing carbon dioxide released during ethanol production and storing it underground can help reduce the fuel’s lifecycle carbon intensity, a factor in determining eligibility and value under clean fuel incentive programs.
In a September operational update, Gevo reported progress on equipment upgrades intended to recover more CO2, improve processing capacity and lower the facility’s carbon-intensity score. The company expects the wider debottlenecking program to increase production capacity and associated carbon capture by 10% to 15%. Completion remains a target for the end of 2026, rather than an accomplished milestone.
Section 45Z rewards qualifying clean transportation fuel production based partly on emissions performance. Section 45Q, by contrast, provides a tax credit for eligible carbon oxide sequestration. The distinction matters because Gevo’s $70 million announcement concerns transferable 45Z credits, not revenue from a carbon storage contract or a direct award under 45Q.
IRS rules also restrict the simultaneous use of certain credits at the same facility, making the precise tax structure important when assessing projects that combine fuel production and carbon capture.
Source link