Following an incredible two days at Solar Manufacturing USA 2026 in Austin, Texas on 22-23 September, all the intel gathered regarding the U.S.-specific production and capex plans of more than 60 manufacturers has now been digested and analysed.
Overlapping with the official release of the new Solar Manufacturing USA Quarterly report, during this week, one aspect of the report’s key findings will be presented and discussed every day on pv magazine.
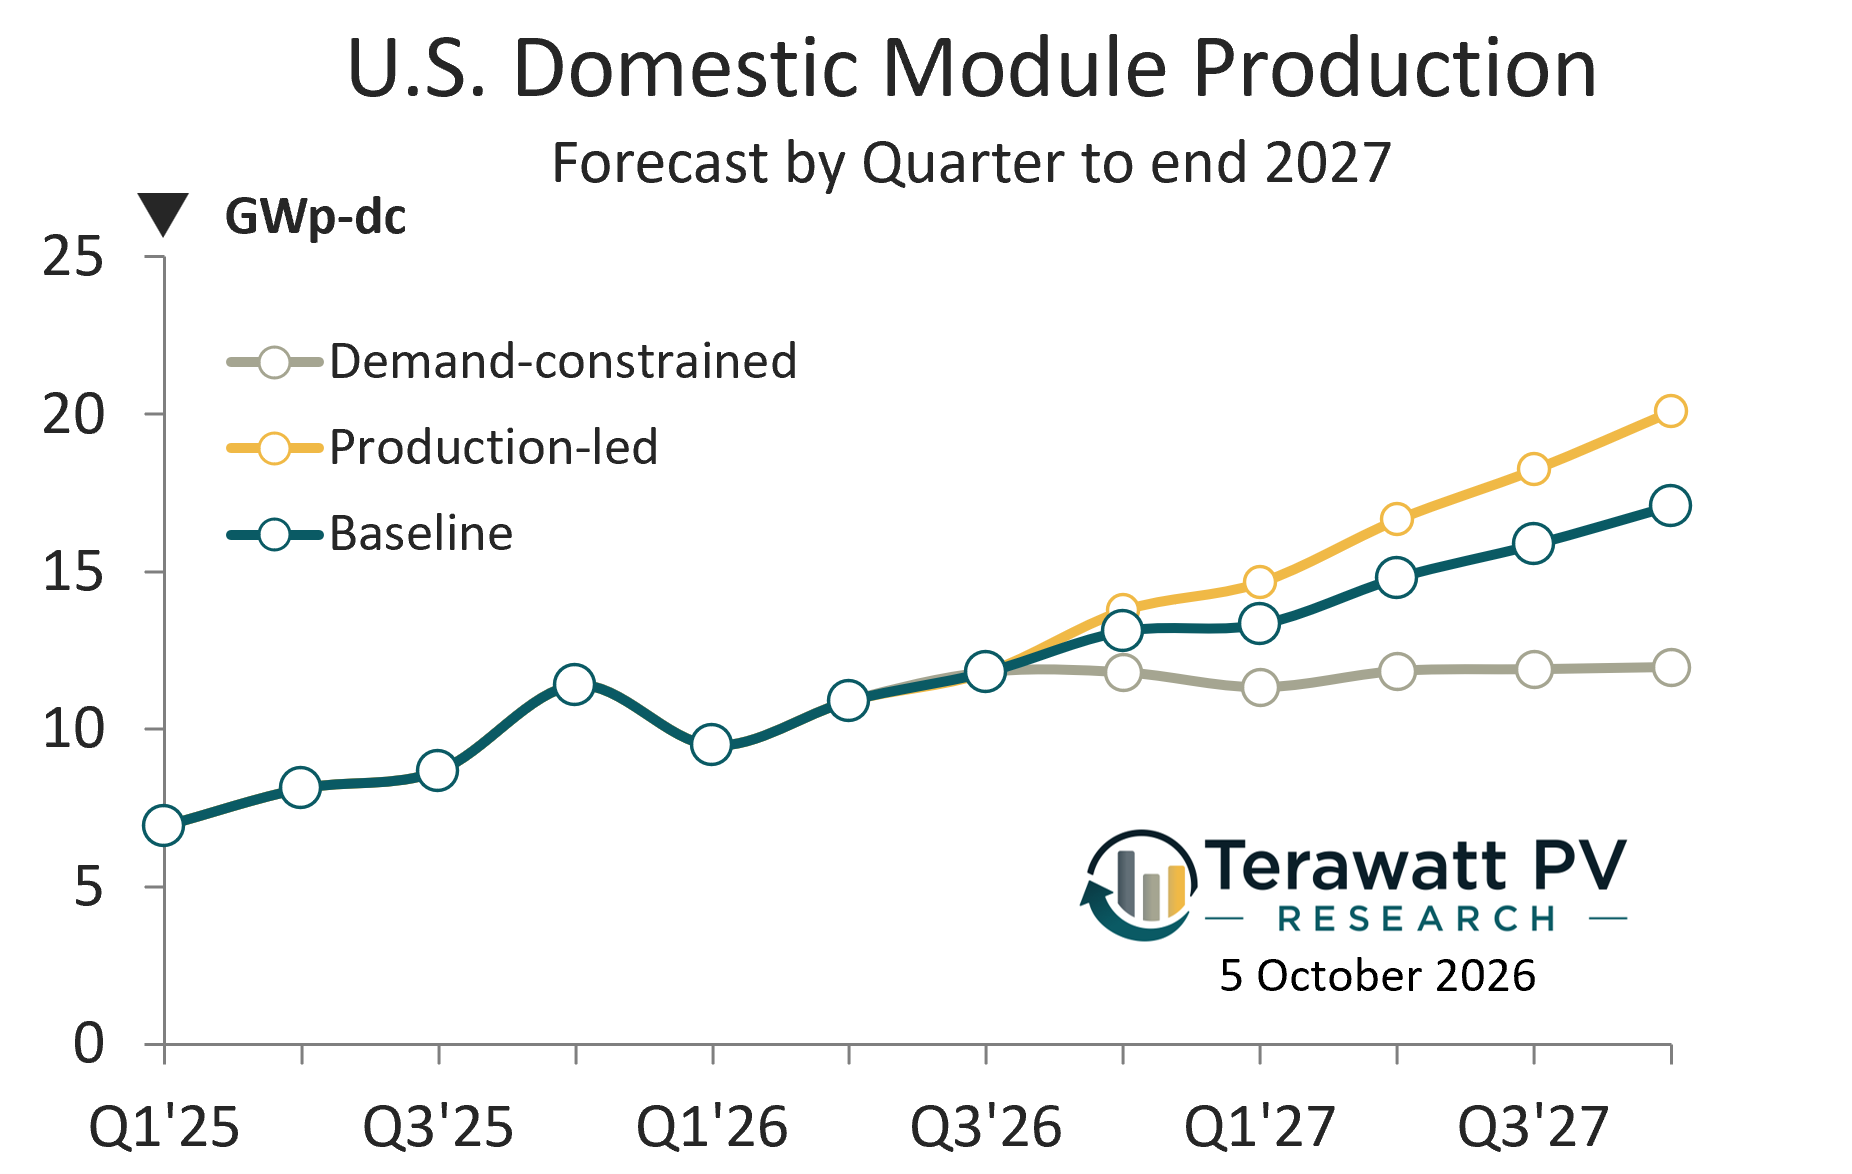
Kicking off this special Austin-debrief series of articles, Part 1 looks at domestic U.S. production volumes to the end of 2027.
The Austin event was pivotal on many fronts, with the 400+ attendees likely each having a unique subset of reasons why the event was needed and how it could help shape what comes next with domestic U.S. solar manufacturing.
One of my hopes is that the event could put an end to the past few years of U.S. solar market observers adding up announced capacity numbers or placing pins in maps every time someone is cited with an aspirational factory investment desire.
Adding announced capacities in the solar industry is naïve, unhelpful and misleading. Ditto, collating random investment figures only detracts from the real picture.
The Solar Manufacturing USA Quarterly report tracks and forecasts (to the end of 2030) the domestic solar manufacturing capex and production volumes for 40-plus companies (and set to grow in 2027), making up more than 99% of value-chain production to the end of 2027 at least.
Source link