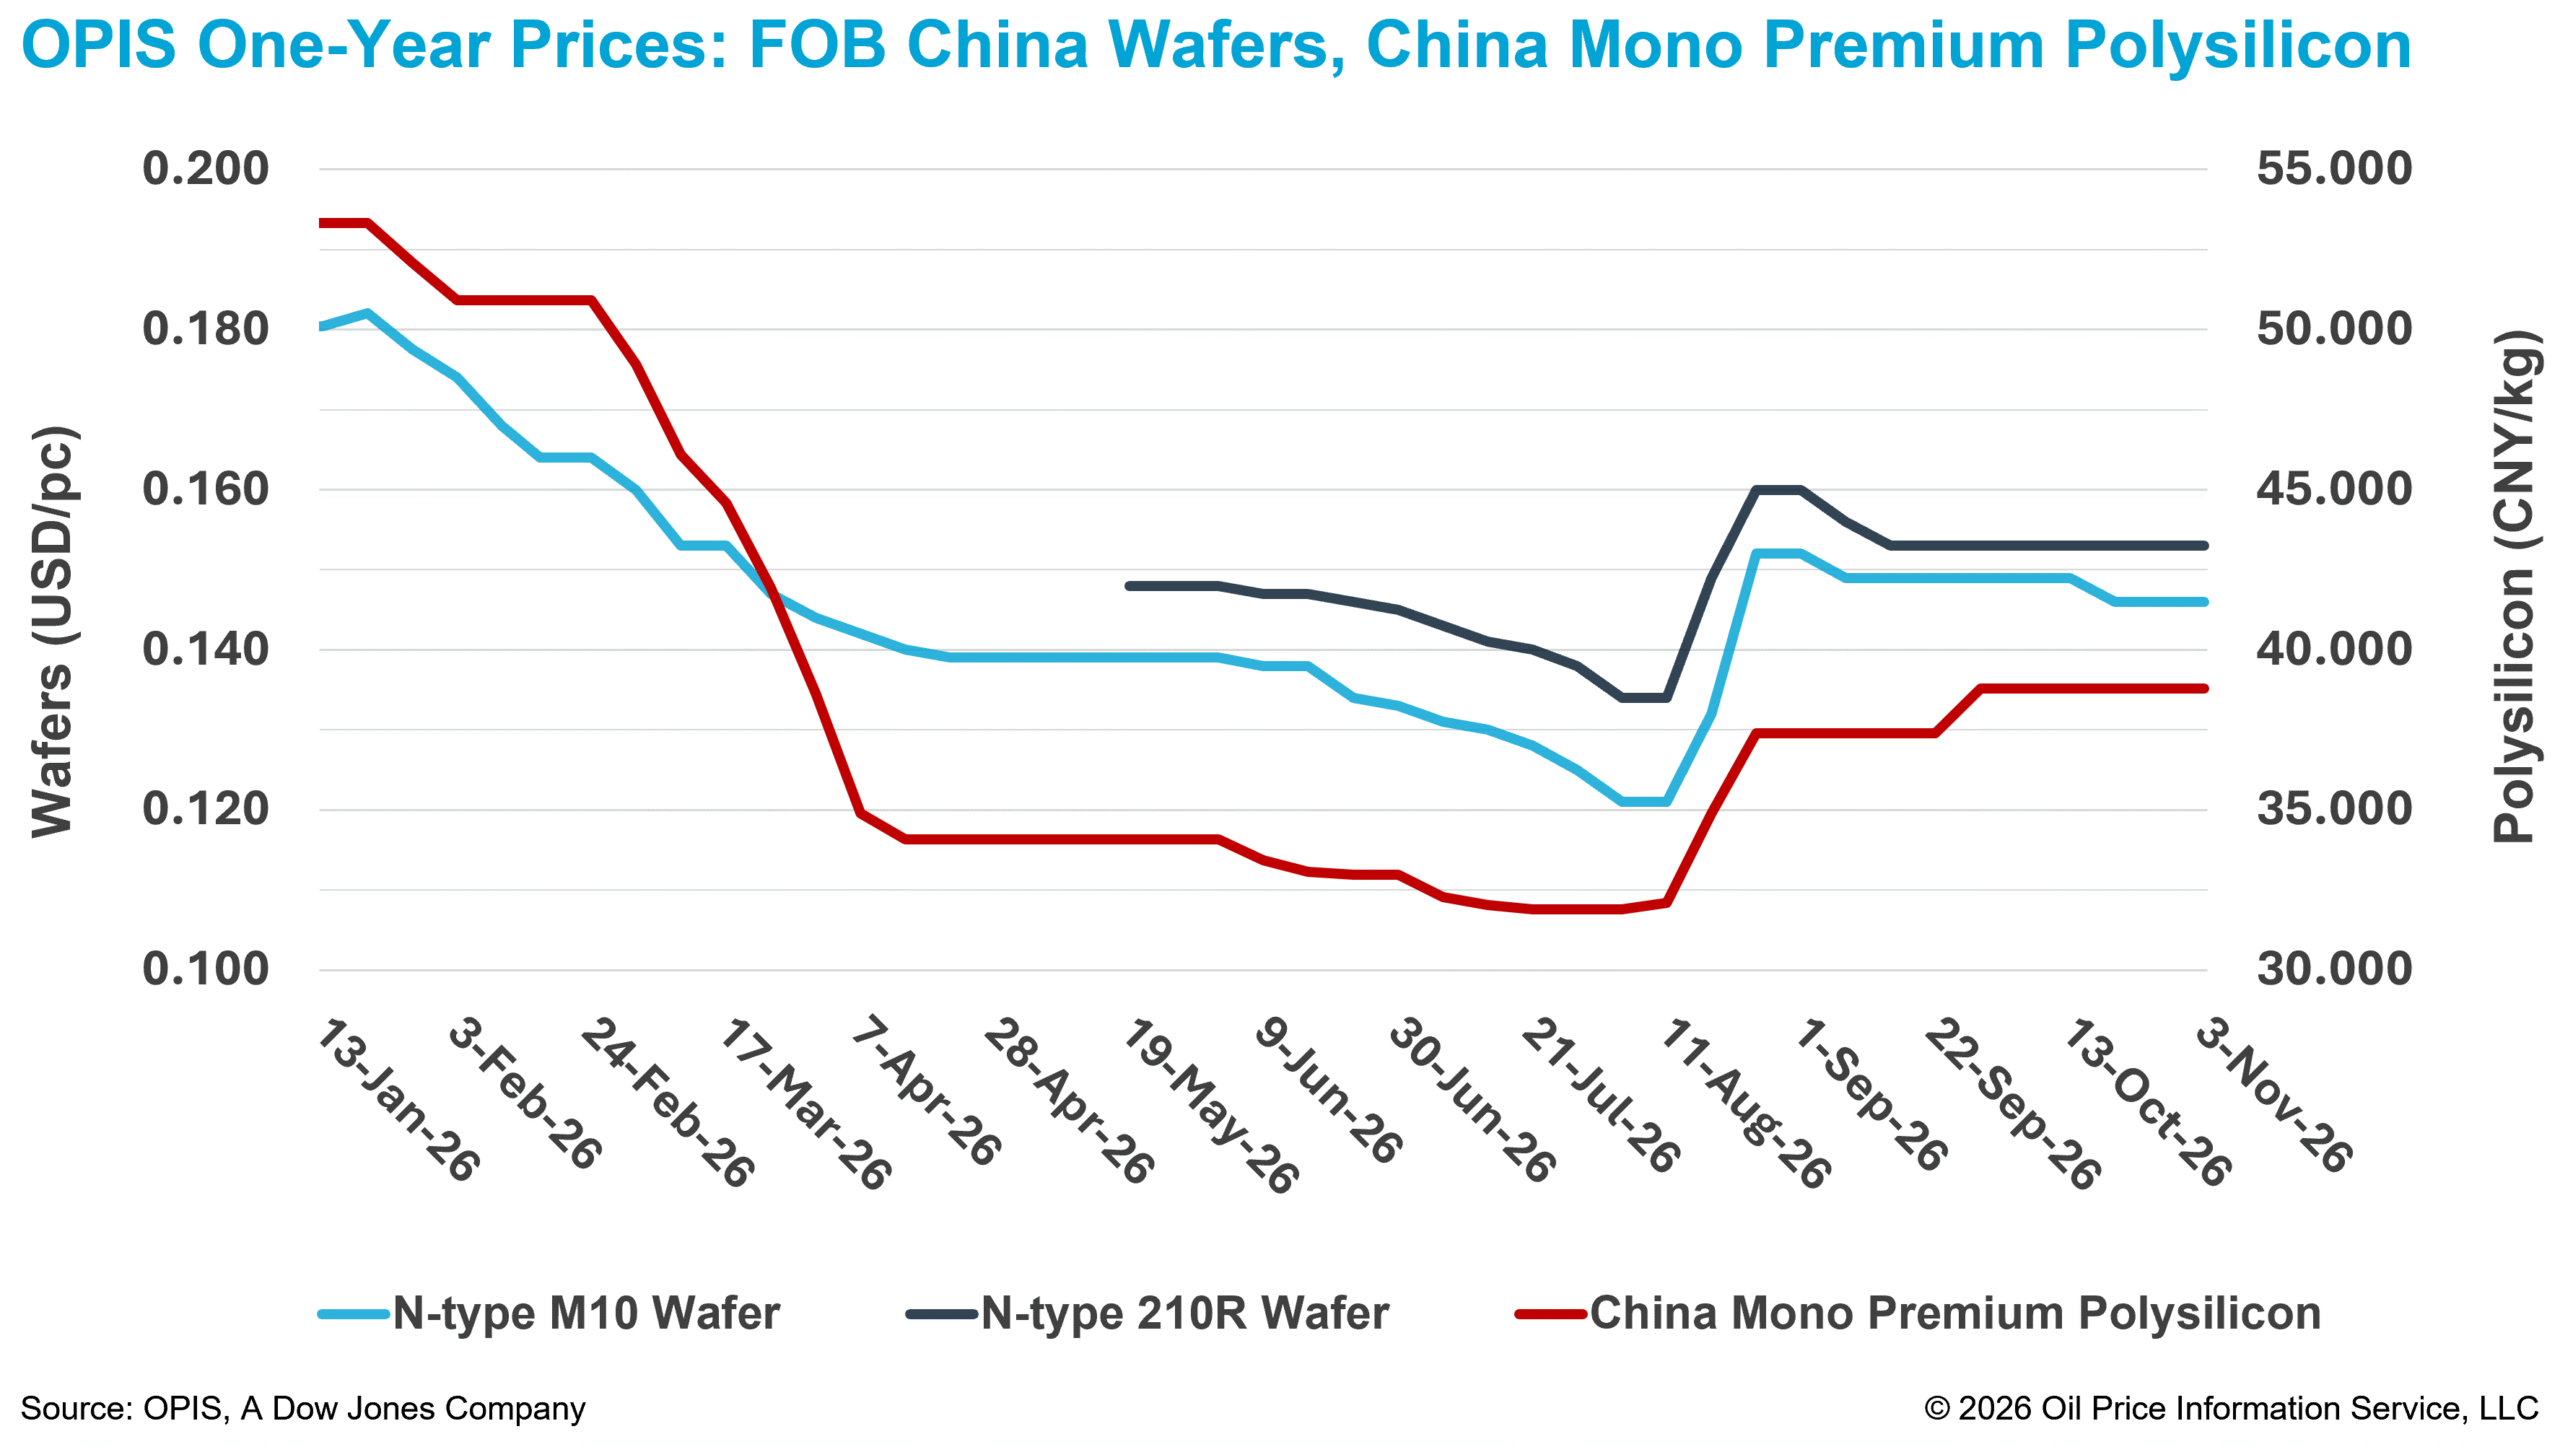
Free-On-Board (FOB) China prices for n-type M10 and 210R wafers remained stable week on week at $0.146/pc and $0.153/pc, respectively, according to the OPIS Global Solar Markets Report released on Nov. 3.
According to market participants, wafer price stability has been supported primarily by firm polysilicon prices. In addition, improving supply-demand dynamics in the solar cell segment, underpinned by overseas demand and domestic end-market installation activity, have provided further support for wafer prices.
Industry sources said that major wafer manufacturers have largely maintained the reduced operating rates implemented in October, with little change since the beginning of November. Leading wafer producers continue to operate at approximately 45%-50% capacity, while specialized manufacturers are maintaining operating rates above 60%.
However, these production adjustments have yet to translate into a meaningful improvement in overall market fundamentals, with oversupply and elevated inventory levels continuing to weigh on the wafer market. Market participants estimated that wafer inventories currently stand at the upper end of the 20-30 GW range. With these structural imbalances yet to ease, sources said the price outlook remains subdued, particularly if downstream demand weakens further.
Another industry source shared a similar assessment, describing the wafer market as fundamentally weak and noting that its pricing outlook remains highly dependent on supply-demand dynamics and price trends across both upstream and downstream segments. The source added that once polysilicon prices come under downward pressure, wafer prices are unlikely to remain insulated from the impact.
A major wafer manufacturer said that transaction volumes remain relatively modest, with customers continuing to adopt a cautious procurement approach.
Source link