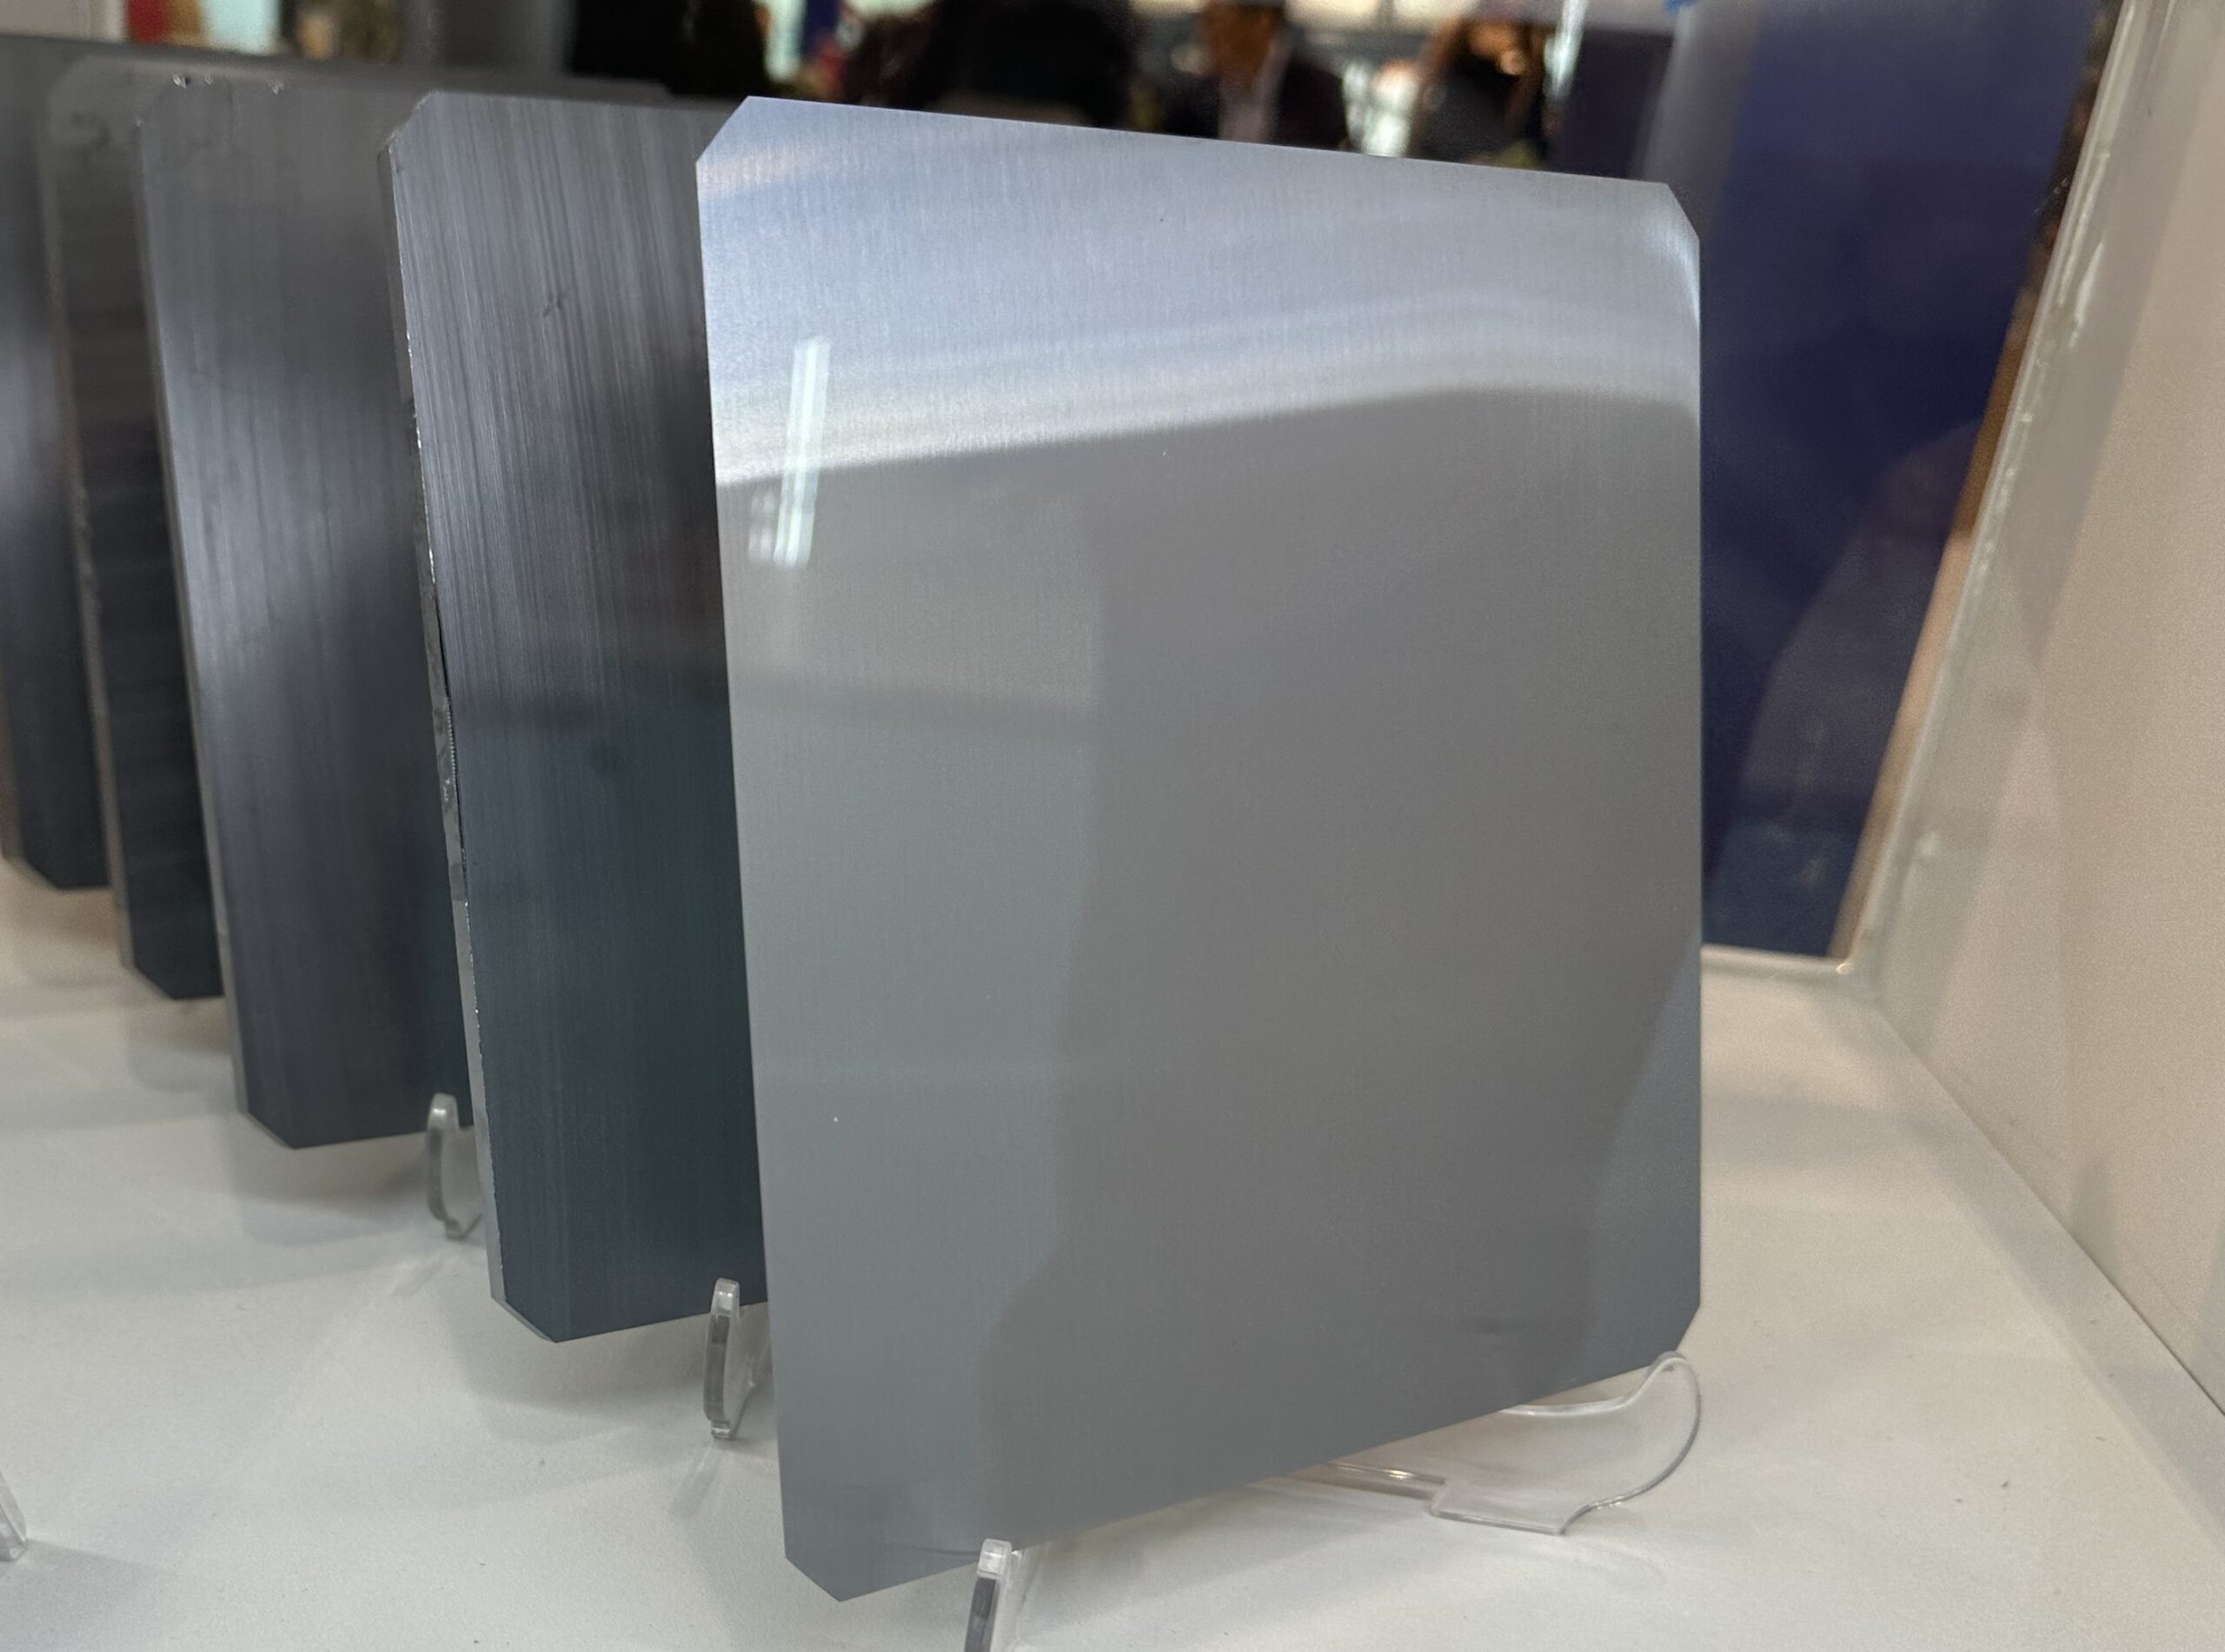
China’s wafer market activity remained subdued as the country entered the early-October Golden Week holiday.
Free-On-Board (FOB) China N-type M10 and 210R wafer prices remained unchanged week on week at $0.149/pc and $0.153/pc respectively, according to the OPIS Global Solar Markets Report released on Oct. 6.
Ahead of the holiday, market participants said prices for orders signed before the break were largely unchanged. Nevertheless, downstream buyers increased procurement to some extent to stock production material, supporting further inventory destocking. Wafer inventories are currently estimated at around 25 GW.
Entering the fourth quarter, wafer producers continue to show divergent production plans, with no broad consensus on production cuts comparable to that emerging in the polysilicon market. Some manufacturers are reportedly planning to increase output in October, partly in anticipation of stronger downstream installation demand toward the end of the year.
Upstream, meanwhile, the polysilicon supply outlook is beginning to shift after several months of rising production. According to the Silicon Branch of the China Nonferrous Metals Industry Association, China’s monthly polysilicon output rose from 92,900 metric tons (MT) in June to an estimated 120,400 MT in September. The association expects the trend to reverse in October, with output forecast to fall approximately 12.9% month on month to around 105,000 MT as planned production cuts outweigh restarts.
At the same time, one polysilicon manufacturer showed a strong willingness to support prices, saying new regulatory requirements require producers to maintain offers at no less than full production costs. Combined with the anticipated production cuts, the manufacturer expects polysilicon prices to move toward production-cost levels, although the adjustment is likely to be gradual.
Source link