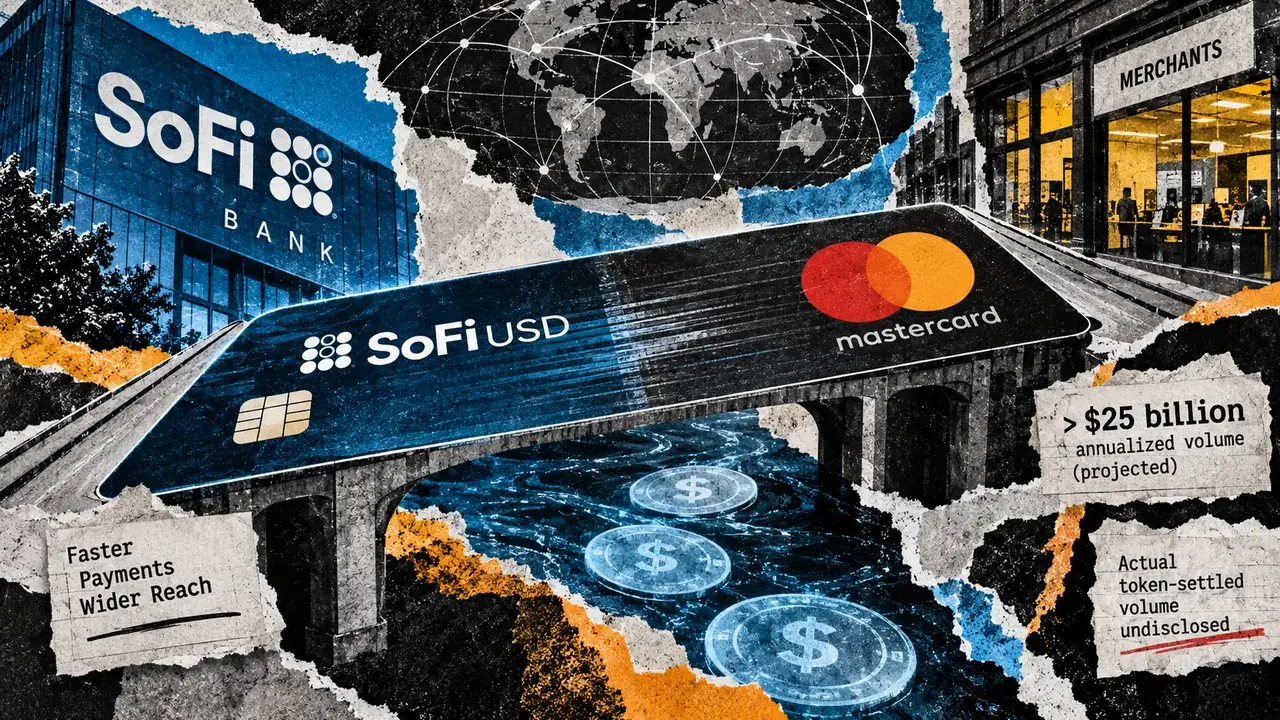
SoFi Bank and Mastercard have announced SoFiUSD settlement is live for the bank's debit and credit card program, moving their March plan into production.
The rollout puts a token-based settlement route behind familiar card payments and, according to SoFi, gives participating merchants a way to receive dollars in a bank account without holding the token. SoFi expects more than $25 billion in annualized card-program volume after migration; it has not disclosed how much has actually settled in SoFiUSD.
The migration remains underway. Cardholders can keep using existing cards, while SoFi describes a bank-account cash route for merchants and separate redemption rules for token holders. Those groups encounter different parts of the arrangement, so a live blockchain transaction alone says little about the scale of merchant benefit or token-holder access.
The March partnership announcement described SoFiUSD settlement as a future option. The companies' September release says transactions are now occurring on a blockchain for SoFi Bank's card program. The full-program migration is still in progress, and SoFi has not given a completion date.
SoFi expects the program to process more than $25 billion annually using SoFiUSD after that migration. The figure is a projection of card activity at an eventual run rate. SoFi has not disclosed the amount or share of transactions already settled in the token. That missing denominator prevents readers from treating the projected program size as the stablecoin's observed throughput.
The token operates behind cards people already carry. SoFi says merchants need no stablecoin holdings or new infrastructure to use its proposed route, and the companies describe no requirement for consumers to acquire crypto at checkout.
Source link