A newer study finds the earlier Binance trading pattern subsided after averaging, but historical wallet gains cannot quantify current losses.
Polymarket’s five-minute Bitcoin contract sampled on Oct. 27 uses averaged opening and closing benchmarks, following an August reform that changed the incentive to move its settlement price.
The current design requires a different risk assessment from the single-snapshot rule examined in earlier research.
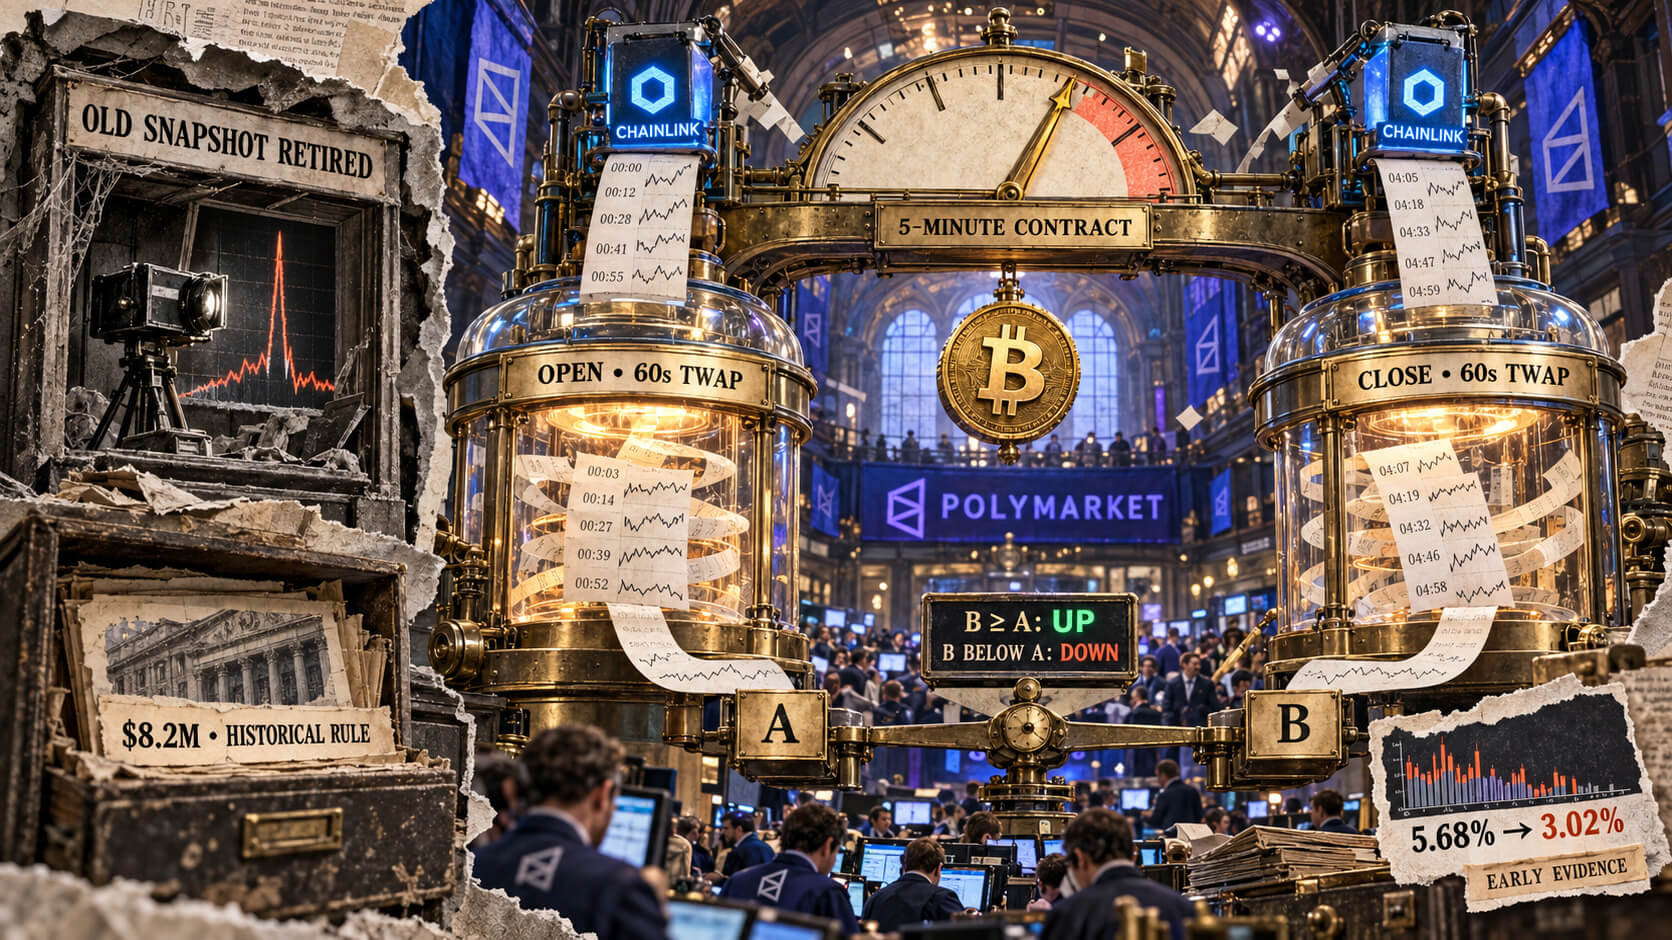
An estimate of about $8.2 million earned by 821 wallets in earlier pushed cycles belongs to that historical research. Guangzhe Wang’s newer study cites the finding from Dai and co-authors.
Wang’s before-and-after results instead point to a subsiding Binance trading pattern in the first weeks after averaging. That gives the reform an empirical test, while keeping separate whether an observed settlement-time pattern declined and how much traders lose under the current rule.
The Oct. 27 Bitcoin market, covering 12:20-12:25 p.m. ET, names Chainlink’s BTC/USD 60-second time-weighted average price (TWAP) as its resolution source. Up wins when the ending benchmark is at least as high as the opening benchmark, and Down wins otherwise.
The Dai, Jia and Yu working paper, submitted to arXiv on June 30, reported settlement-time spot-flow spikes and subsequent reversals after the five-minute contract’s launch. The broader finding concerns the incentive to move the underlying reference market.
Wang’s newer paper examined Binance one-second data from July 1, 2025, through Sept. 4, 2026, with 82,752 Bitcoin boundaries where only the five-minute contract settled.
Source link