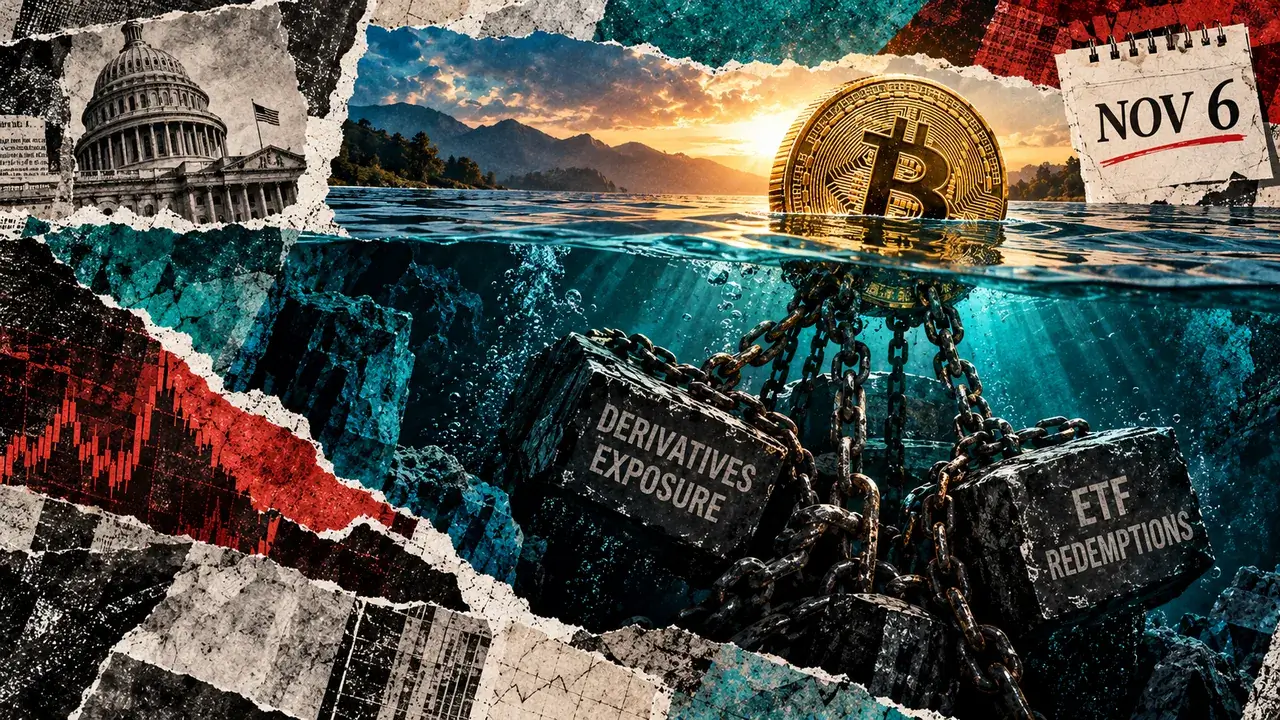
Higher selected derivatives exposure and ETF redemptions leave the recovery facing a demand test before November 6 payrolls.
Bitcoin was near $77,000 on October 31 after the selloff around the Binance breach. If you’re now thinking about assessing a recovery, the first thing to look at is whether demand returns without another expansion in outstanding derivatives positions. Forced closures removed positions during the shock, yet a later provider reading showed selected Bitcoin exposure higher in dollar terms.
Bitcoin traded at $77,367 on Saturday morning, October 31. Later that morning derivatives showed higher dollar exposure over its 24-hour comparison, while the last completed US spot ETF session recorded redemptions. That makes the composition of any recovery more consequential than the price level alone.
Block Scholes, a crypto derivatives data provider, reported $1.53 billion in crypto-wide liquidations over 24 hours in its October 30 note, with 84% in long positions. Those figures describe forced closures across crypto, rather than Bitcoin alone. They also belong to the note’s reporting window, rather than an October 31 tally.
The same report said open interest on Binance’s BTC-USDT perpetual held steady through the initial drop before rising 4.5% between 23:00 UTC October 29 and 04:00 UTC October 30. That is a narrower observation than a market-wide leverage reset: it concerns one contract on one exchange.
Open interest measures positions still outstanding. Liquidations describe positions forced shut. New positions can be opened while other traders are being closed out, so a large liquidation total and continued outstanding exposure can coexist.
Source link