
Want more housing market stories from Lance Lambert’s ResiClub in your inbox? Subscribe to the ResiClub newsletter.
Nationally aggregated inventory is up +5.6% on a year-over-year basis between September 30, 2025 and September 30, 2026.
That marks three straight months where the year-over-year growth in active inventory for sale has accelerated. However, it’s only a tad acceleration from the low of +1.9% year-over-year inventory growth in June.
If you go back 12 months, the year-over-year national inventory growth rate was higher (+16.9%). Nonetheless, the continued growth in nationally aggregated inventory suggests a nationally aggregated housing market that’s soft, with buyers in many markets gaining some additional leverage over the past year.
And with long-term yields and mortgage rates back at a two-year high, we’ll be watching to see how much momentum the national softening regains as we head deeper into the seasonally slow period. We’re already starting to see it regain some momentum.
Nationally, we’re just shy of reaching back to pre-pandemic 2019 inventory levels (-5.2% below September 2019).
Between September 2024 and September 2025, U.S. active inventory across the country rose by +159,427 homes for sale.
Between September 2025 and September 2026, U.S. active inventory across the country rose by +61,208 homes for sale.
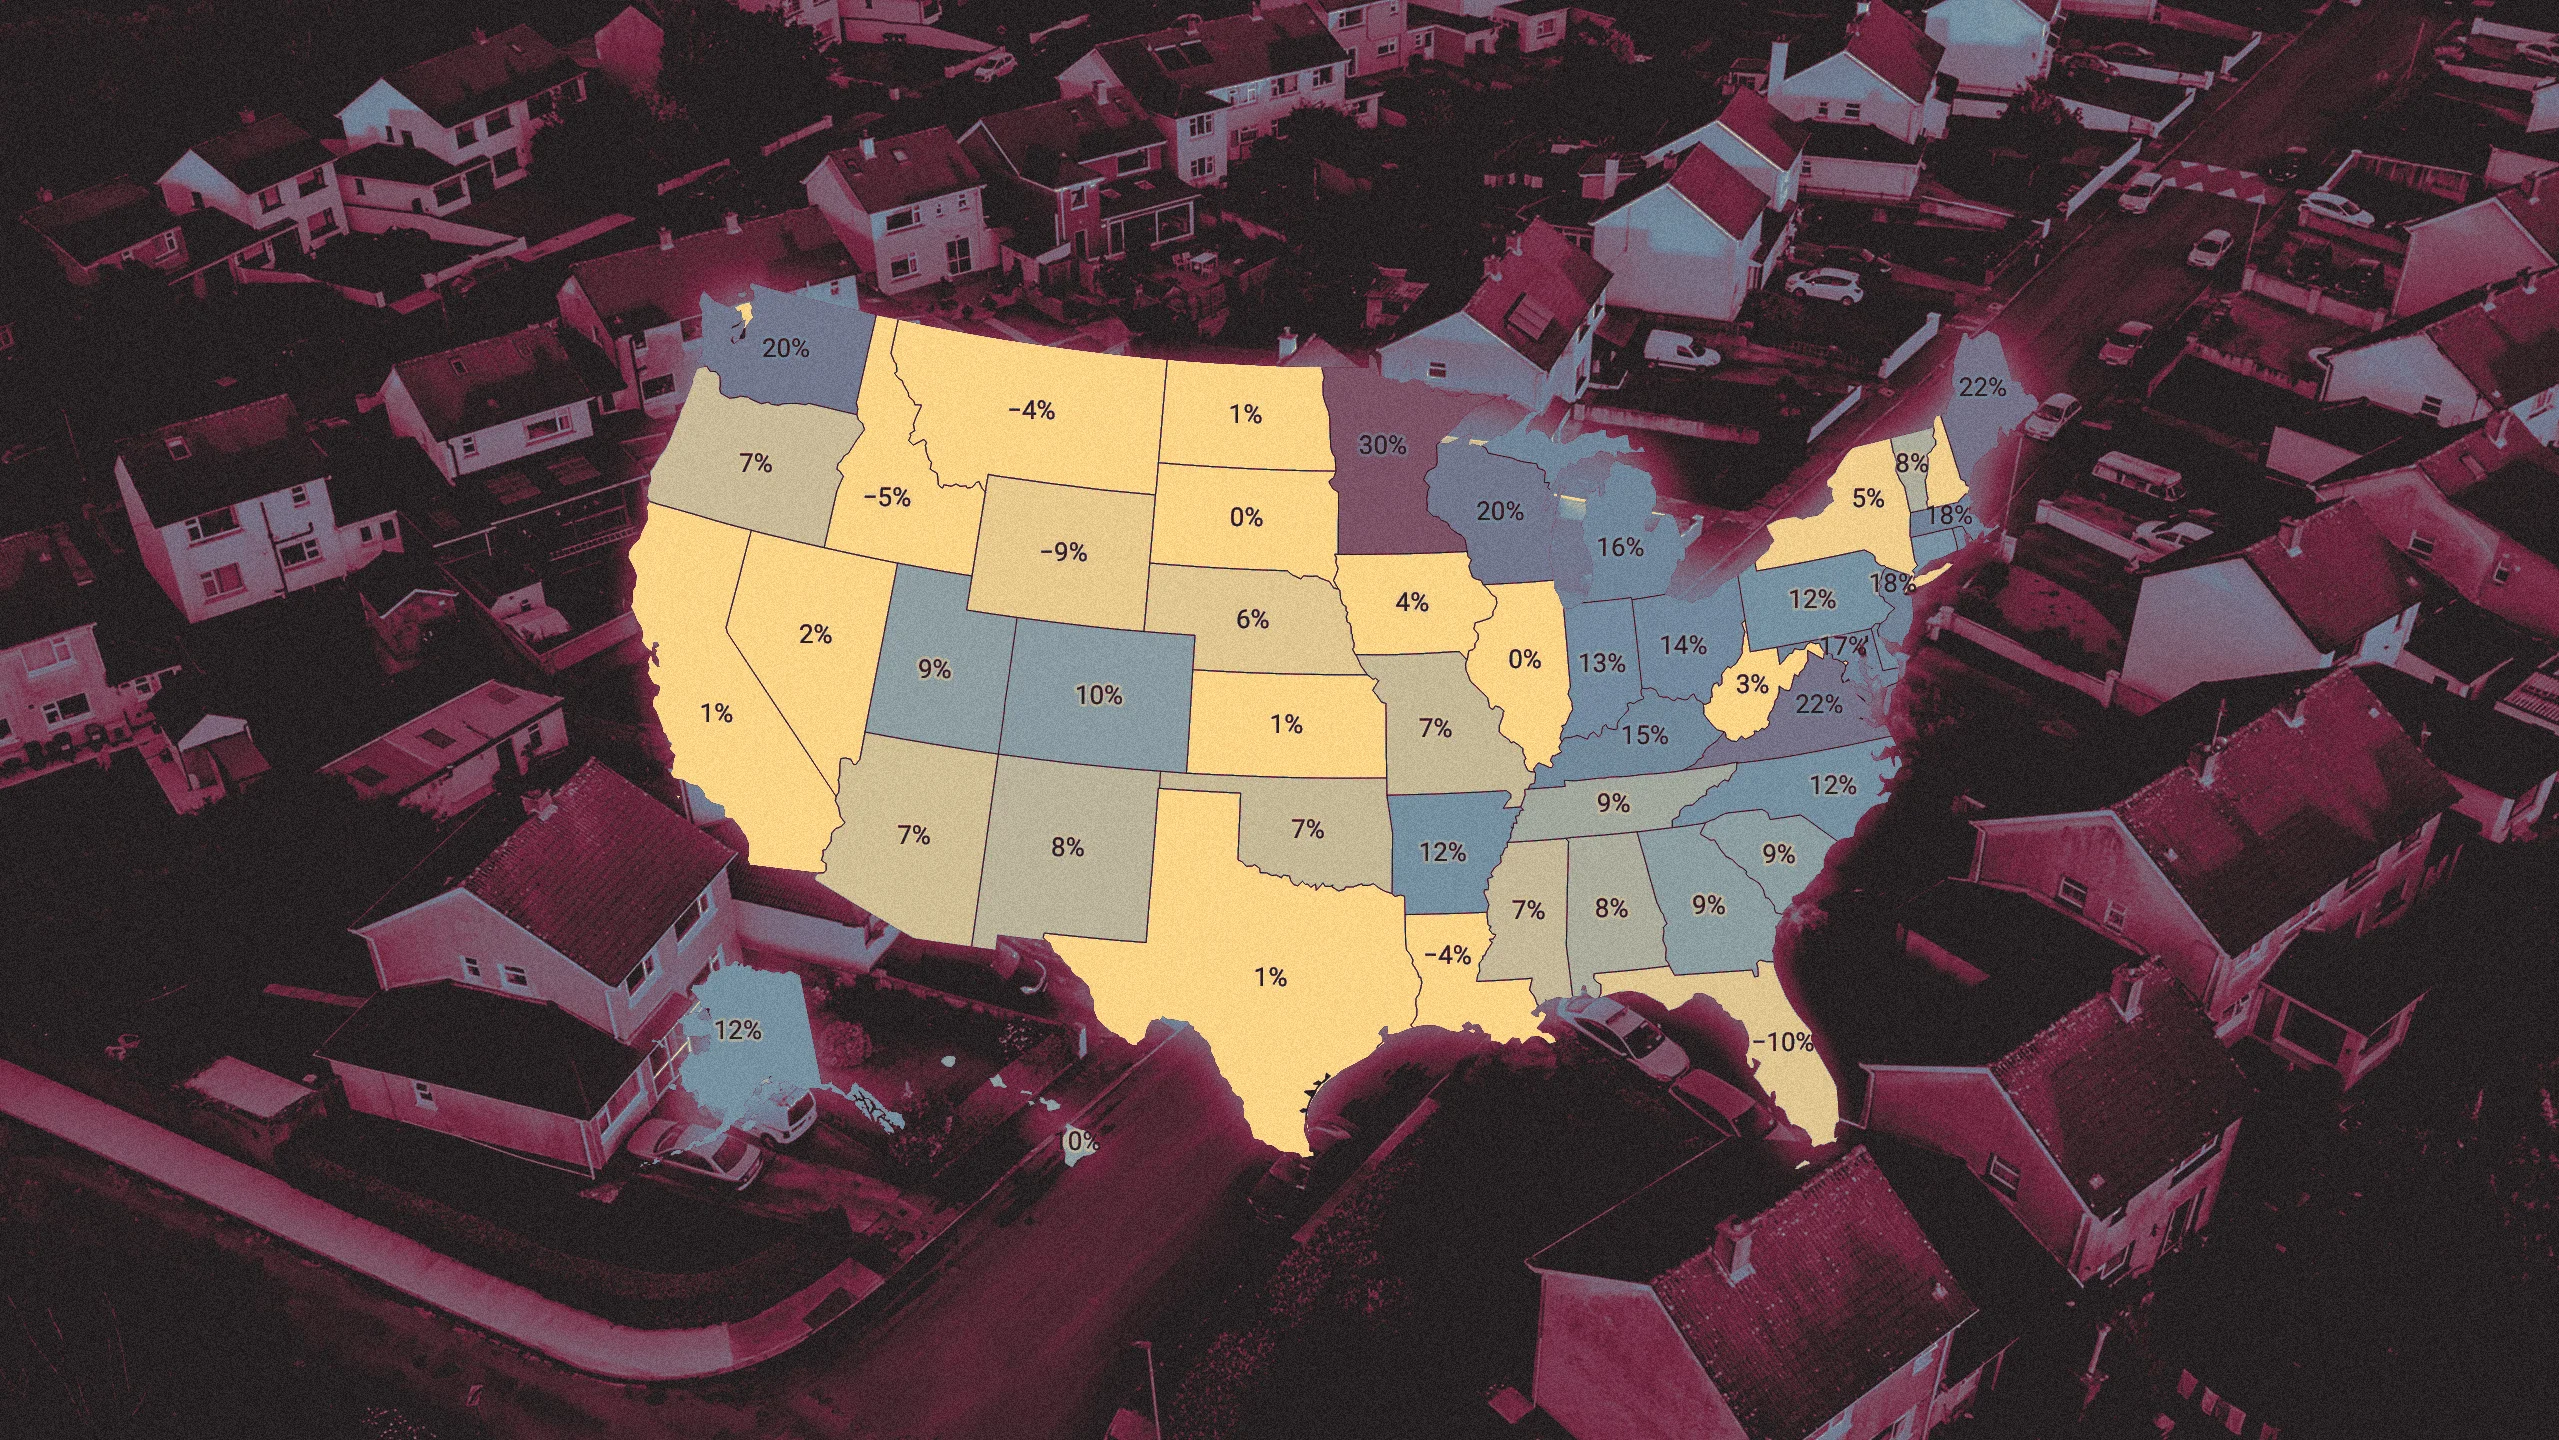
While active housing inventory is rising in most markets on a year-over-year basis, the pace of growth is more mild than a year ago (see the side-by-side maps below). In fact, Florida—home to many of the weakest regional housing markets over the past two years—is seeing active inventory edge down a little year-over-year (-10%).
Source link