Getting approval for a mortgage, a car loan or even a mobile phone contract can rest on a credit score.
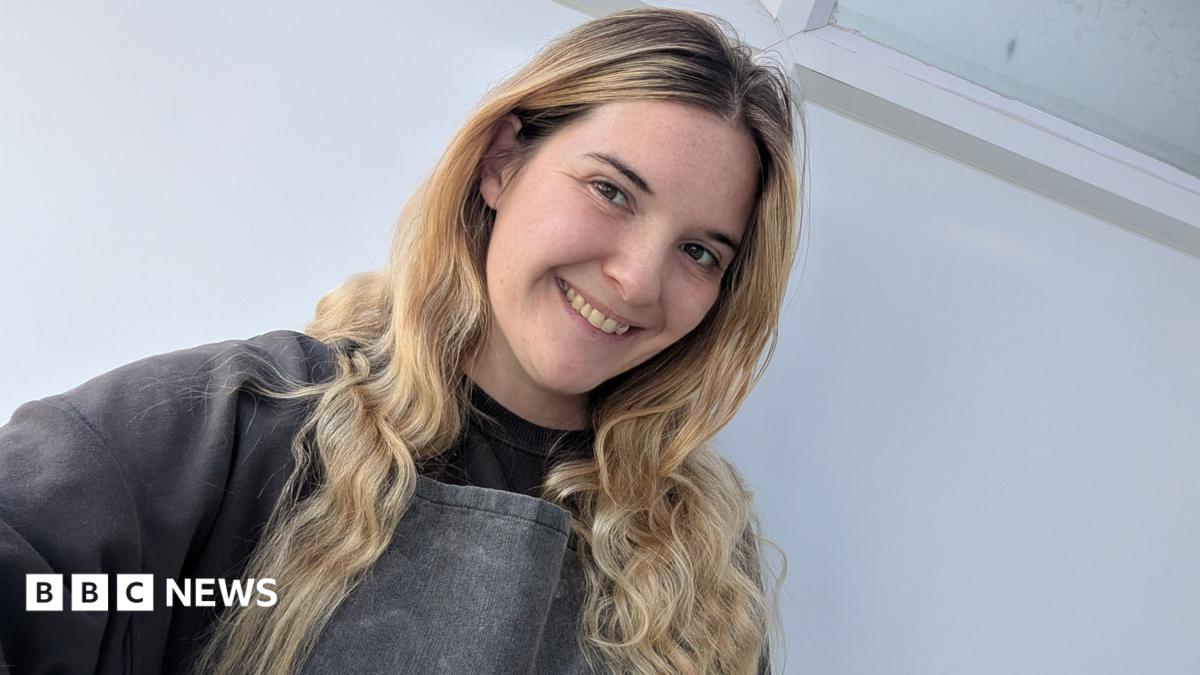
Sophie Hope was on the sharp end of just such a decision.
"When I first checked my credit score, it was excellent. But then my mortgage application was suddenly denied by the lender because of my credit report. It was a massive shock as I'd never had bad credit. When I looked into it, my score had gone to 'very poor'," she says.
It turns out, the Brighton-based nail technician and content creator, had been the victim of identity fraud.
"Someone had opened accounts in my name across various catalogue sites and ordered multiple items, including a PlayStation 4 and Nike socks," she says.
"Without me knowing, the debt was transferred to a secondary finance company. It spent three to four years accumulating in the background. It was only when I went to apply for a mortgage that I discovered how severely it had dragged down my credit score," she says.
Hope's experience shows how crucial a credit score can be, but, as in her case, it does not tell the full story.
"As a nation, we are overly obsessed with credit scores," says Funmi Olufunwa, a consumer finance lawyer and founder of financial education business, Hoops Finance.
Three firms - Experian, Equifax and TransUnion - produce credit scores in the UK, and they all work from roughly the same data.
"A credit score is backward looking. It's looking at what has happened in the past, which doesn't necessarily predict the future," says Olufunwa.
Source link