
But the moment money needs to move across markets, the experience can feel as if the business has stepped back into another era.
Companies still need to open accounts across jurisdictions, connect with different banks and payment providers, understand local clearing systems, navigate compliance requirements, manage FX and cut-off times, and reconcile transactions across disconnected systems.
Business operations have moved to the cloud. Money movement, in many ways, is still running on bare metal.
That is why I increasingly believe the missing layer in B2B cross-border payments is not another bank account, another wallet, or even another payment method.
The breakthrough of an operating system was never about teaching everyone how processors, memory, and motherboards work.
Windows and macOS created value by abstracting the complexity of the underlying hardware, allowing people to use applications and get work done without understanding every component underneath.
For years, the payments industry has focused on connectivity: connecting more banks, more markets, more currencies, and more payment methods. Those connections still matter. But as businesses become truly global, adding more connections is no longer enough.
The next generation of financial infrastructure must answer a different question: How do we make all that complexity manageable without making businesses navigate it themselves?
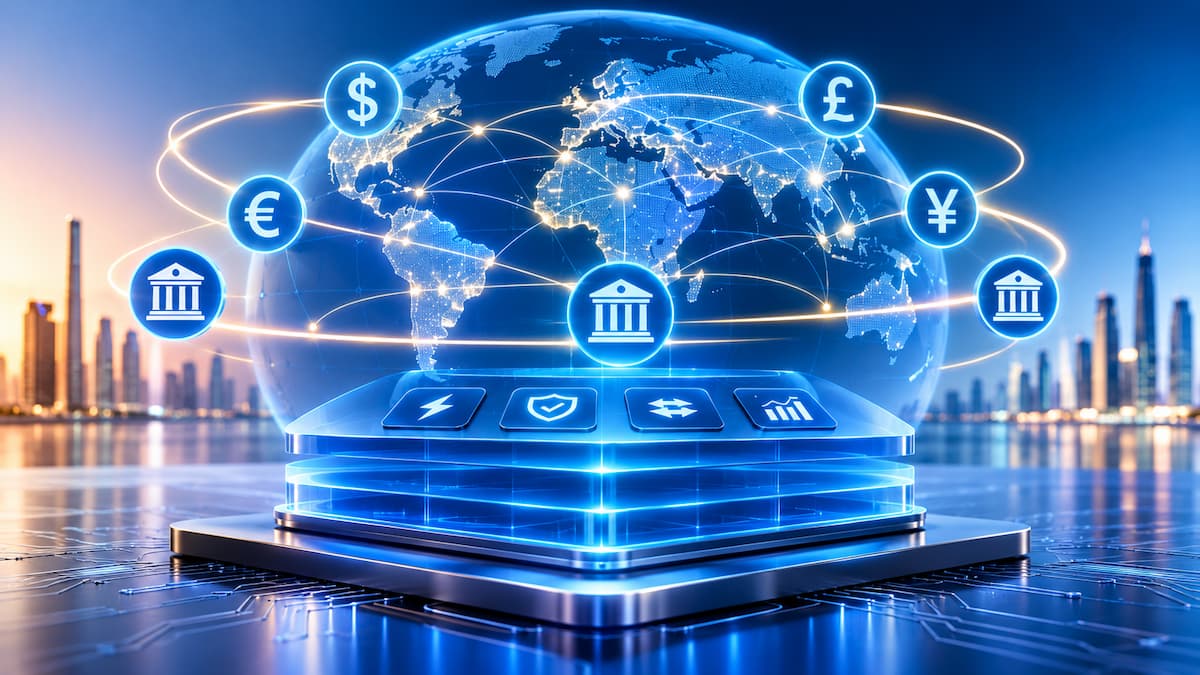
A true Financial OS needs to connect to bank accounts, local clearing systems, card networks, foreign exchange infrastructure, and emerging stablecoin rails, while abstracting their different rules, formats, settlement windows, and liquidity requirements into one unified infrastructure layer.
A business should not need to know which correspondent bank handled a transaction, which domestic clearing network was used, or which settlement rail was selected behind the scenes.
Source link