Marqeta’s 2026 State of Credit Report found that 67% of consumers would replace their primary debit card with a flexible credential. This isn’t curiosity but preference, and the gap between what consumers want and what most card programs offer is widening fast.
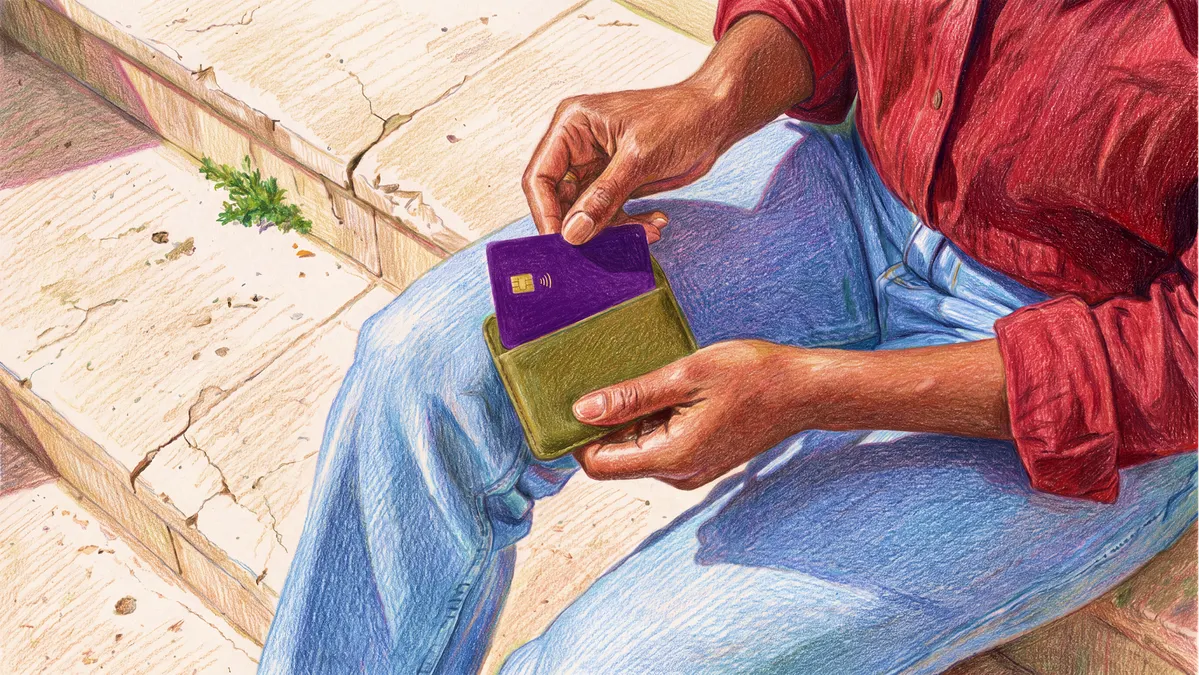
A single payment card that adapts to context. At checkout, the cardholder can pay with debit, draw on a credit line, split the purchase into BNPL installments, or combine funding sources. The form factor stays the same while the payment method changes. These products are live in market today, so the question for issuers is whether they’re positioned to deliver one.
Interest is strongest among younger consumers: 48% of 18 to 44 year olds are interested, and 60% of 18 to 34 year olds started their financial journey with a credit product, which makes them more attuned to flexibility. Consumers say they want to:
Notably, 71% of consumers with multiple credit cards want to switch between credit products at checkout. They already have the products but can’t use them fluidly in one transaction.
Consumers switch providers because of improved credit scores, life changes, or better rewards elsewhere, not because something went wrong. Providers won’t lose customers in a dramatic moment. They’ll lose them gradually, one contextual payment decision at a time, as customers reach for a different card when theirs can’t do what’s needed. With flexible credentials increasingly visible on social feeds, through peers, and at checkout, that moment is coming soon. With a flexible credential, the relationship deepens rather than fragments.
Source link