
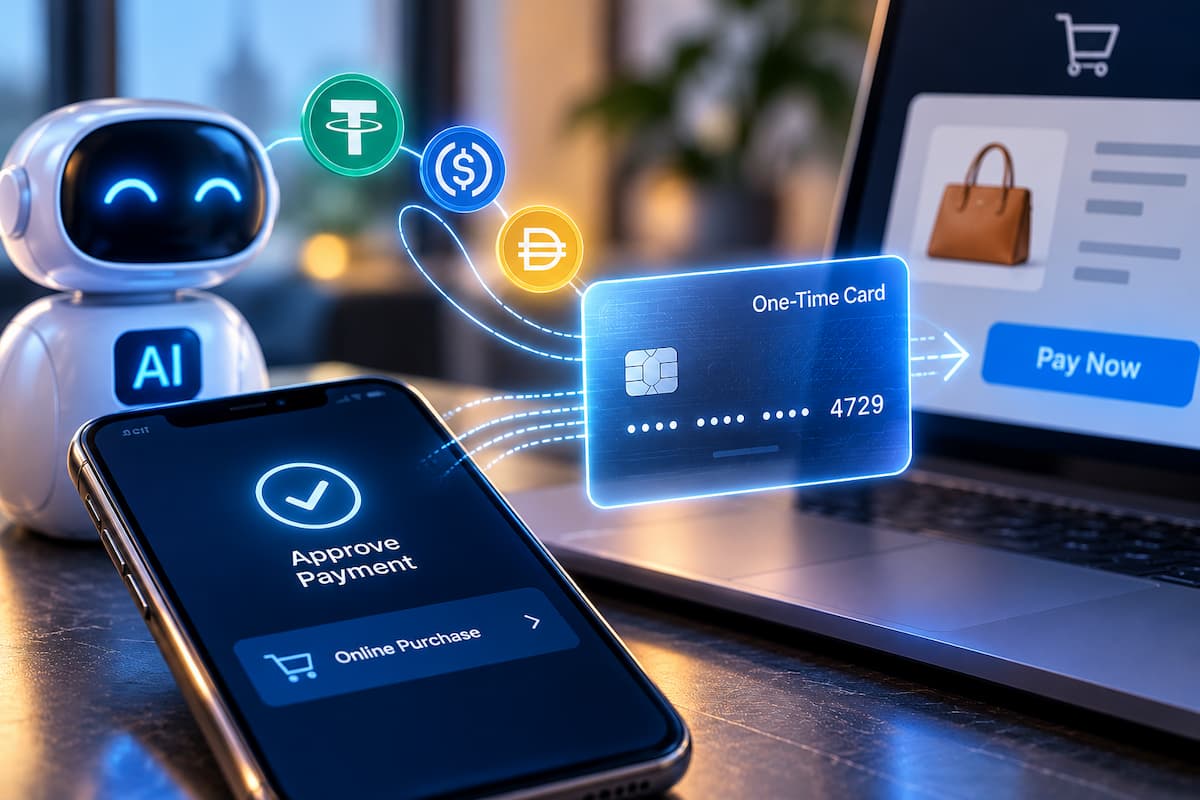
The mechanism works through ephemeral card issuance. When a user asks an AI assistant to book, buy or pay for something, the assistant flags the transaction for approval. Once the user confirms, Oobit generates a one-time virtual card tied exclusively to that transaction. The AI receives the card details it needs to complete checkout; it never holds the user’s wallet credentials or sees the broader account. Oobit then handles identity verification, authorisation and payment execution in the background.
The product supports USDT and other stablecoins. Users in supported markets can also fund their Oobit balance through local payment rails, including bank transfers, mobile money networks and Brazil’s Pix instant payment system. The company says the solution is available across more than 75 countries.
“AI can already understand what you want and figure out how to get it,” said Amram Adar, co-founder and CEO of Oobit. “The missing piece is the ability to pay. That shouldn’t depend on where you live or which bank card you have.”
Oobit’s core design choice, separating permission to pay from access to money, addresses a genuine structural problem in agentic AI commerce. As large language model platforms move from information retrieval into task execution, the question of how an AI agent interacts with financial accounts becomes a live compliance and consumer-protection issue. Unrestricted wallet access creates risks around unauthorised transactions, account takeover and liability attribution that neither banks nor regulators have fully resolved.
The one-time card model is not new in isolation. Virtual card infrastructure has been used in accounts-payable automation, B2B procurement and travel expense management for years.
Source link