NBFCs must shift focus from loan book expansion to risk-adjusted profitability: Industry leaders
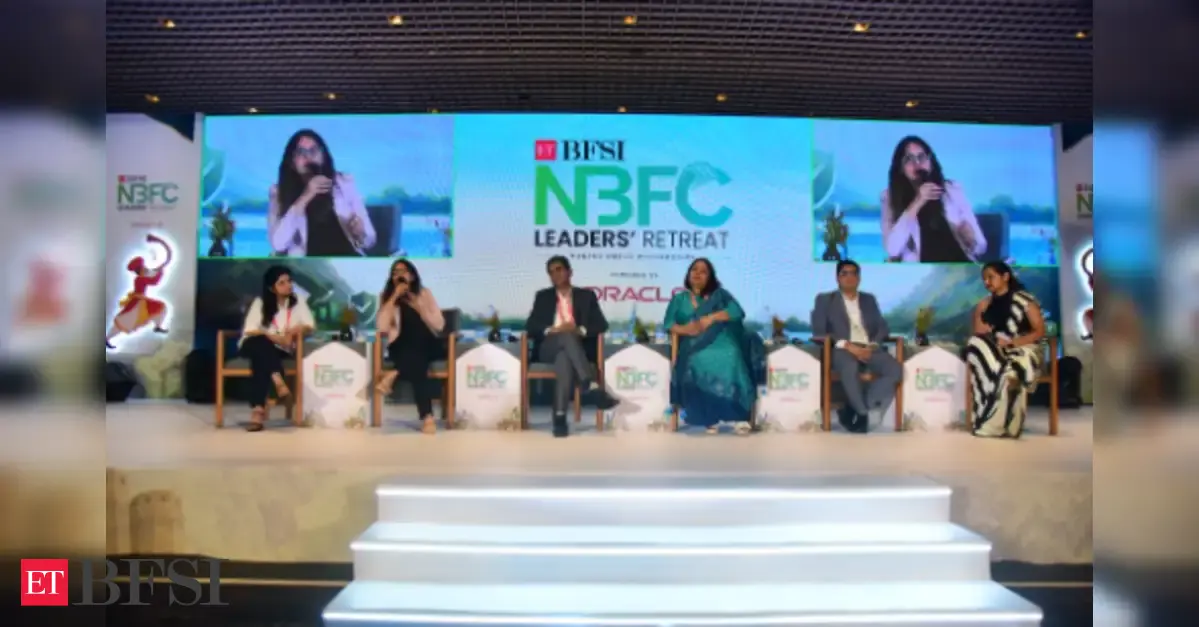
Rising credit costs, delayed defaults, AI-related risks and cybersecurity threats are pushing NBFCs to prioritise portfolio quality, stronger governance and sustainable returns over disbursement growth, risk and compliance leaders said at the ETBFSI NBFC Leaders’ Retreat 2026.
NBFCs must move beyond loan book expansion and assess growth through risk-adjusted returns, portfolio quality and operational resilience as credit and technology risks evolve, industry leaders said. At the ETBFSI NBFC Leaders’ Retreat 2026, Abhishikta Munjal, CRO, Clix Capital; Mallika Mittal, CRO & President, InCred Finance; Ashutosh Tiwary, Head Credit Policy & Risk, Lendingkart Finance; Pinki Jha, Chief Compliance Officer, Oxyzo; and Jimit Shah, CISO, LIC Housing Finance, discussed the changing risk priorities for lenders. Profitability matters more than disbursement growth Munjal said lenders must evaluate growth against expected credit losses, operating expenses and returns rather than AUM alone. Clix Capital has revamped its expected credit loss model and introduced regular portfolio reviews involving business and risk teams to identify segments generating sustainable returns. Advt
Mittal highlighted risk-adjusted return on capital (RAROC) as a more meaningful measure of performance because it accounts for credit costs, operating expenses and capital deployed. She said lenders should assess whether returns can be sustained over a two-to-three-year horizon. Tiwary cautioned that the true cost of lending often emerges with a delay, with losses on some 36-month business loans peaking around 18–20 months into the tenure. “The true cost of growth in the lending business is only known after a time lag,” he said.
Source link