NBFCs brace for rural loan stress as drought and weak monsoon hit farm incomes
Lenders with greater exposure to rural borrowers, vehicles, personal loans and microfinance could face greater asset-quality risks than those focused on urban mortgages and business loans.
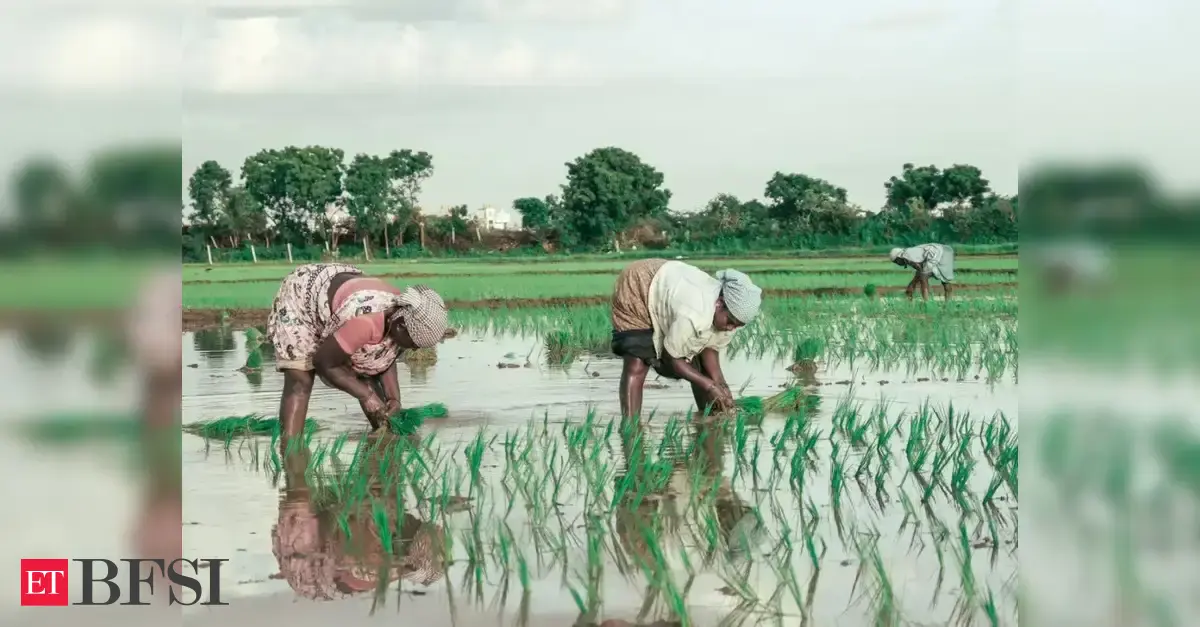
Rural NBFCs face potential asset-quality pressure from weak monsoon conditions, drought, depleted reservoirs and a 37% year-on-year decline in rabi sowing coverage. Food inflation, a prolonged high-interest-rate environment and regulatory changes affecting flexi loans and insurance distribution add to sectoral headwinds. Urban-focused lenders with greater exposure to mortgages and business loans are seen as better placed than rural, vehicle and consumption-focused NBFCs. Nomura's bear-case scenario assumes slower loan growth, higher credit costs and halved insurance fee income from FY28; it prefers Piramal Finance, Tata Capital, Aadhar Housing Finance and Bajaj Finance.
Non-banking financial companies (NBFCs) face pressure from weakening rural incomes, food inflation, a prolonged high-interest-rate environment and regulatory changes, with the impact likely to vary according to their loan portfolios. Lenders with greater exposure to rural borrowers, vehicles, personal loans and microfinance could face greater asset-quality risks than those focused on urban mortgages and business loans. The concerns come amid uneven rainfall, depleted reservoir levels and a slow start to the rabi sowing season. A bear-case scenario for NBFCs factors in slower loan growth, higher credit costs, a 50% reduction in insurance fee income from FY28 and an increase in the risk-free rate assumption to 7.25% from 6.25%, according to a report by Nomura. Advt
The south-west monsoon ended with a 13% deficit at the all-India level, while the South Peninsula and East and North-East regions recorded deficits of up to 27%.
Source link