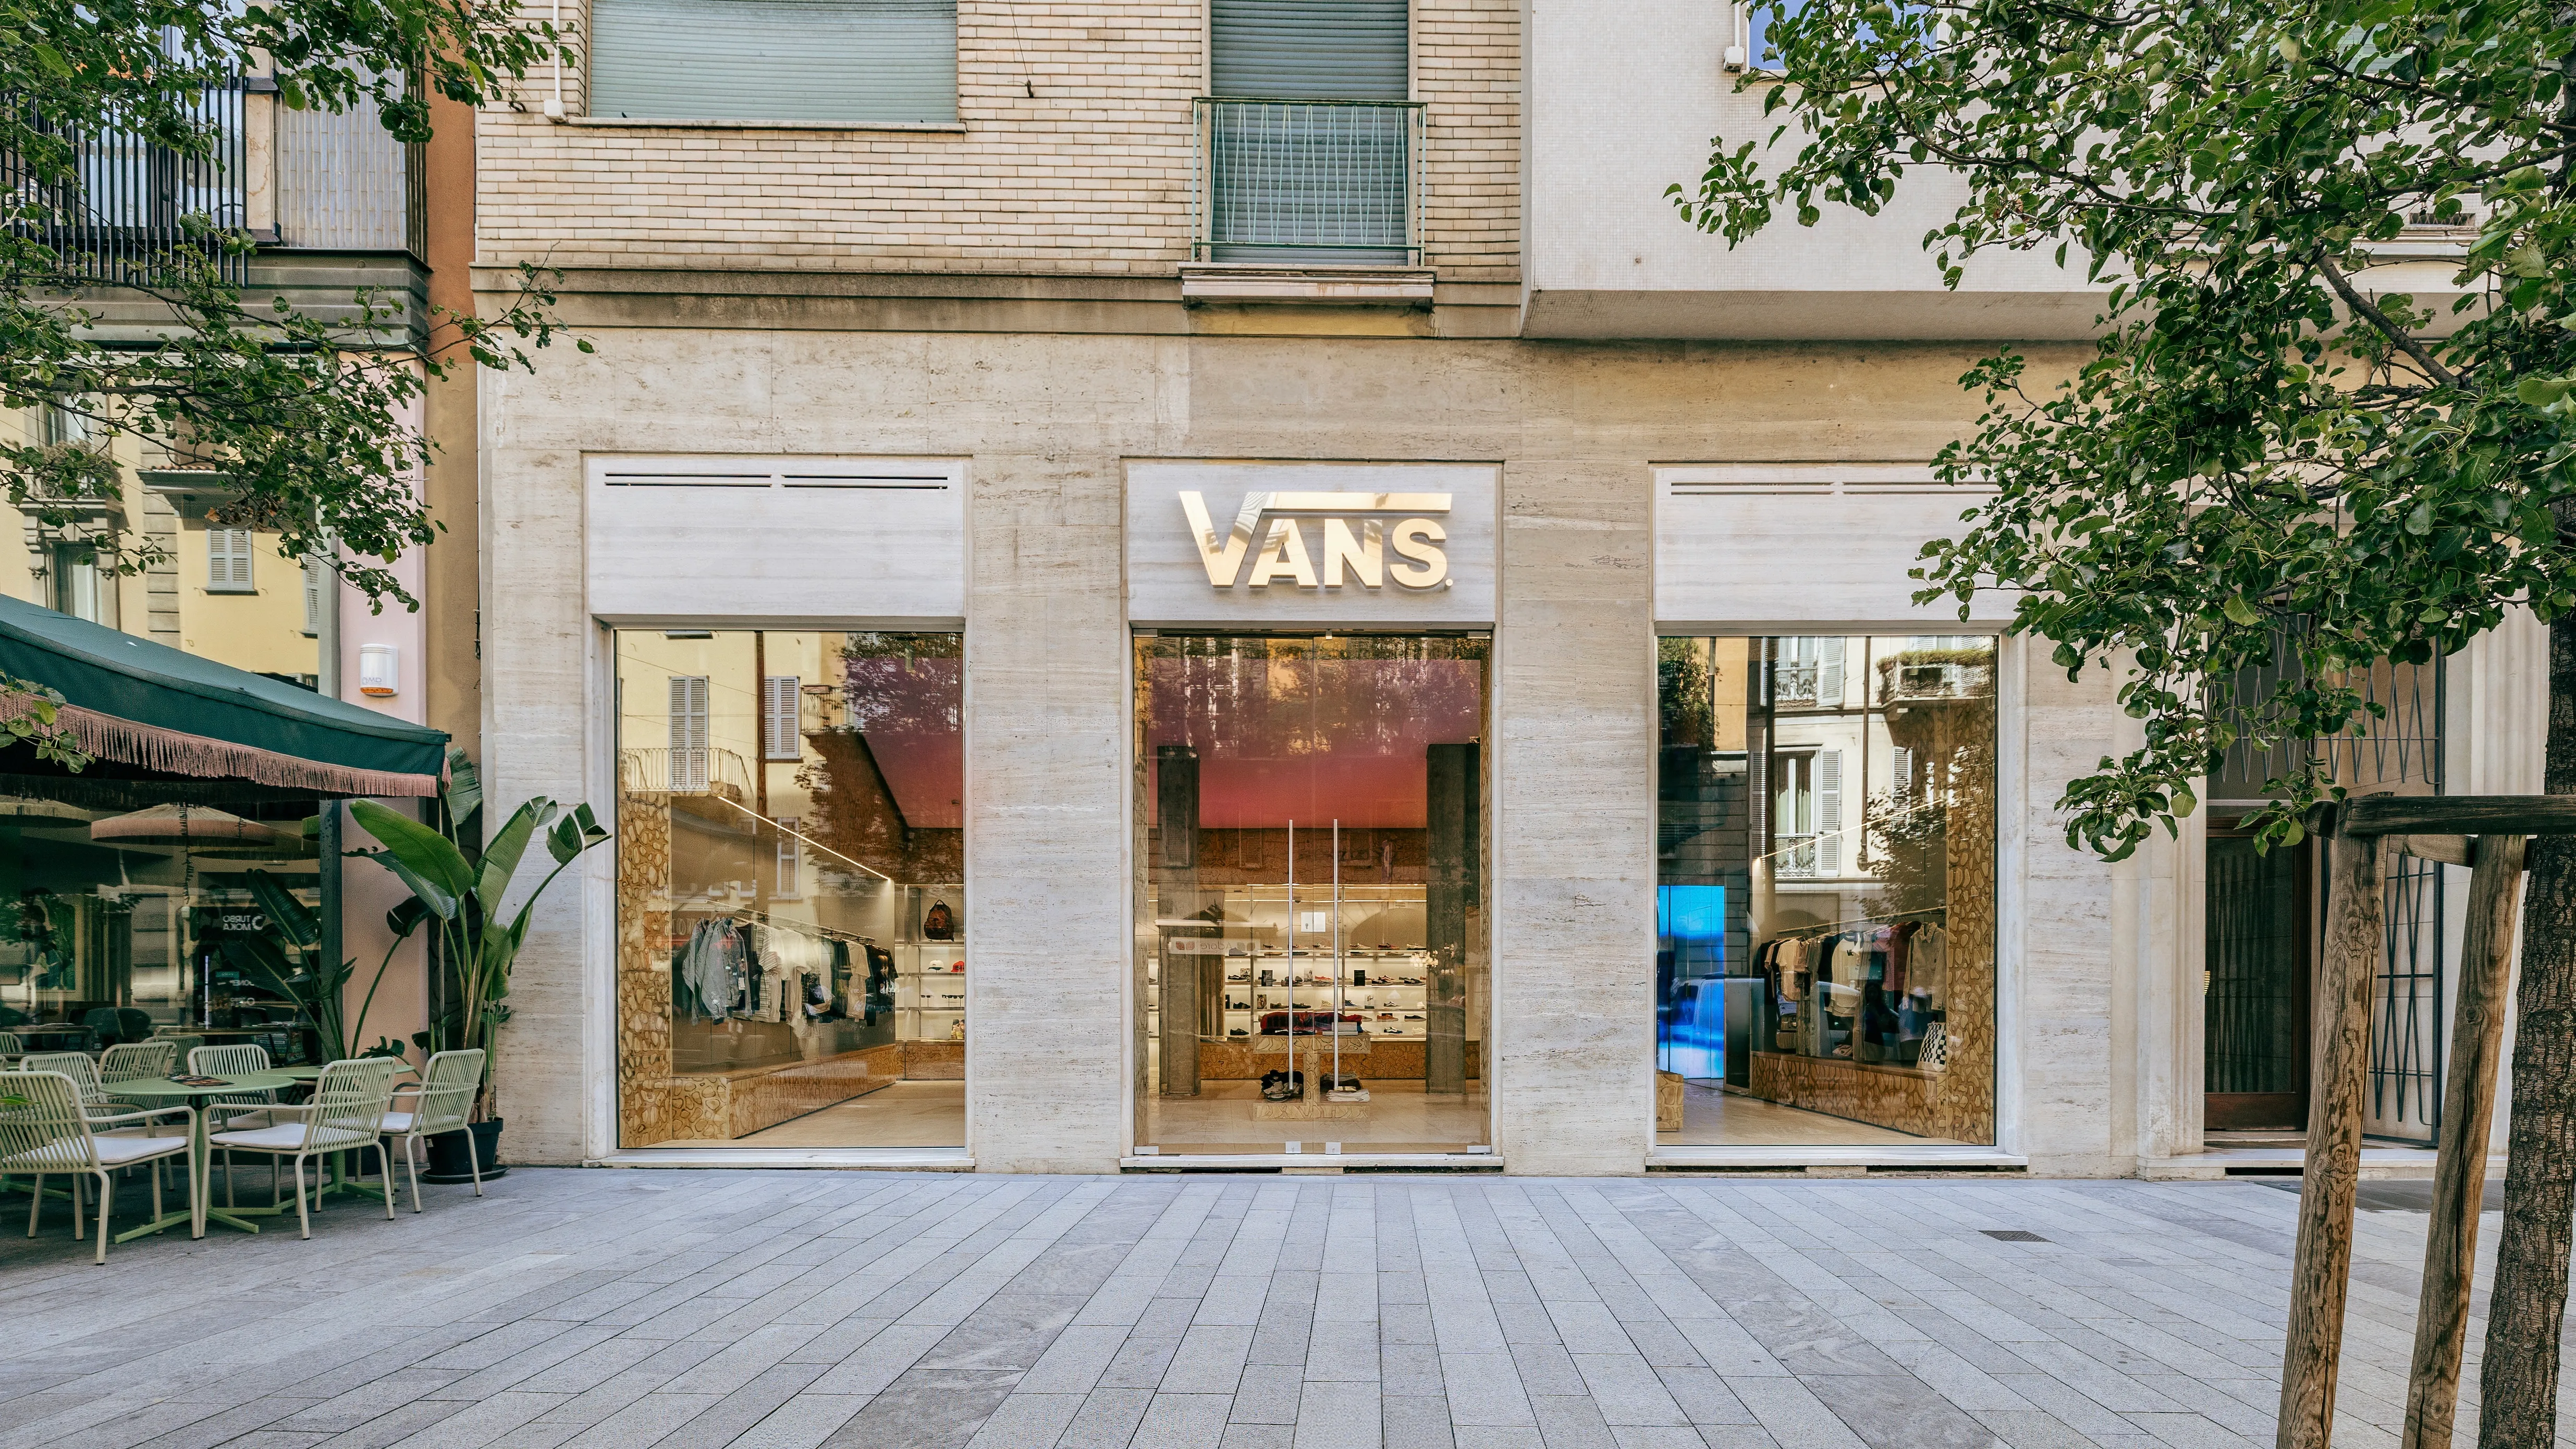
VF Corp.'s looking at outdoor for growth for Timberland, North Face and Altra brands; Vans provides additional upside to the balance sheet.
Vans occupies a unique position in VF Corp.’s portfolio — one where the balance sheet doesn’t require the brand to show growth.
That might be an odd way of looking at Vans’ contribution to the overall portfolio. But that way of thinking makes sense once one understands how VF thinks about healthy growth, and ultimately the “free” benefit that Vans contributes to the balance sheet.
“Obviously, there’s an option to get rid of the brand and actually make the balance sheet work, get to [profitable] growth faster. But we do like the optionality of holding on [to] the brand, really king of tempering it back into the right growth zone,” said VF’s Abhishek Dalmia, vice president, chief financial officer and chief operating officer. He made the comments on Tuesday at J.P. Morgan Chase & Co.’s Global Brands and Luxury Conference in Paris.
According to Dalmia, Vans was a $4 billion business “on the back of just five product silhouettes” that’s now down to $2 billion. It has a very big direct-to-consumer business, strong gross margin, but also a very high fixed cost infrastructure. And now that the business is right-sized, it would give VF the ability to have a “massive flow-through from a profitability standpoint” as soon as the decline is stabilized and “we start to temper into a slow growth mode for Vans. So, it’s a beautiful business,” he told attendees, adding that growth will come from a focus on product with the P&L starting to flow because of its fixed cost structure.
Source link