In 2024, Christine Goulay, founder and CEO of Sustainabelle Advisory Services, wrote that scaling next-gen materials in fashion was all but inevitable—but only if the industry rallied to move from isolated pilots to mainstream use by fixing broken incentives, standardizing metrics and sharing supply chain risk.
Two years later, her updated report found that early commercial relationships have proliferated, but the bar for adoption has also risen: Every brand she surveyed in 2026 rated performance and aesthetics as a very significant obstacle, for example, while every investor said the same of supply chain integration.
Related Stories

Material World: Spider Silk and T-Rex Leather
Lululemon Brings Enzymatically Recycled Polyester to Running Shorts
The biggest challenge facing today’s second wave of materials science startups like Reju and Syre isn’t so much awareness, Goulay said, as it is conversion. The “real energy” she felt around next-gen materials when she conducted her first survey of nearly 160 brands, innovators, suppliers, investors and supporting organizations still crackles. But it’s now tempered by the “realism” of a world economy beset by geopolitical conflict, surging energy costs and whipsawing tariff decisions.
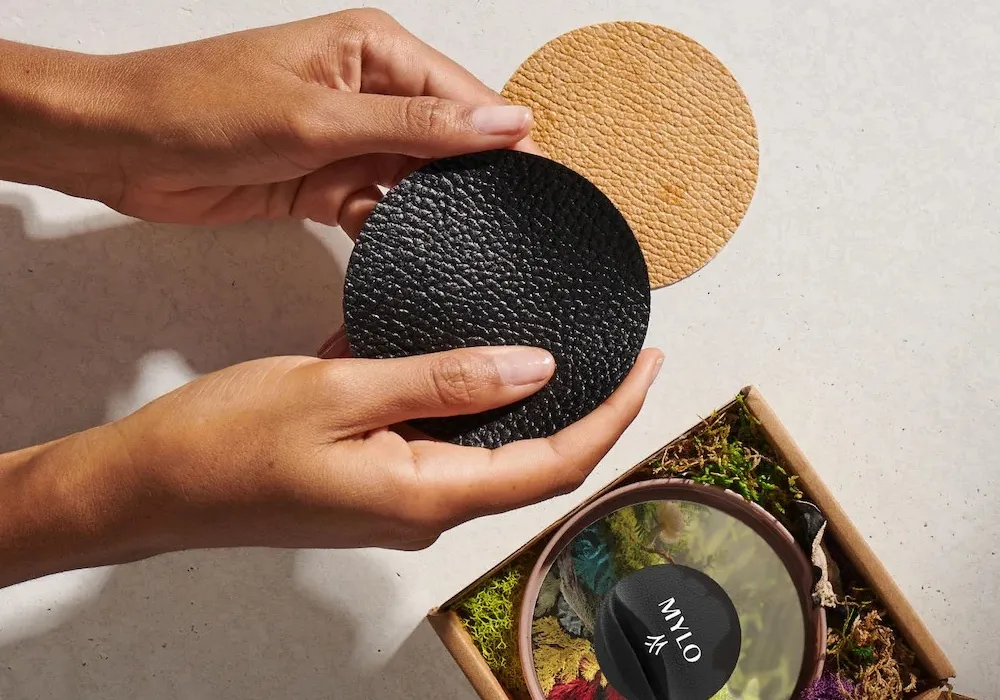
In other words, Goulay said, sustainability is no longer enough for innovators to win the hearts and wallets of brands, as forerunners like Bolt Threads, which stopped producing Mylo, its mycelium-based leather alternative, in 2023, and Renewcell, whose textile-to-textile recycling operations declared bankruptcy in 2024, might have learned the hard way.
“Price parity, equal or better performance and easy implementation are now the starting points,” she said.
Source link