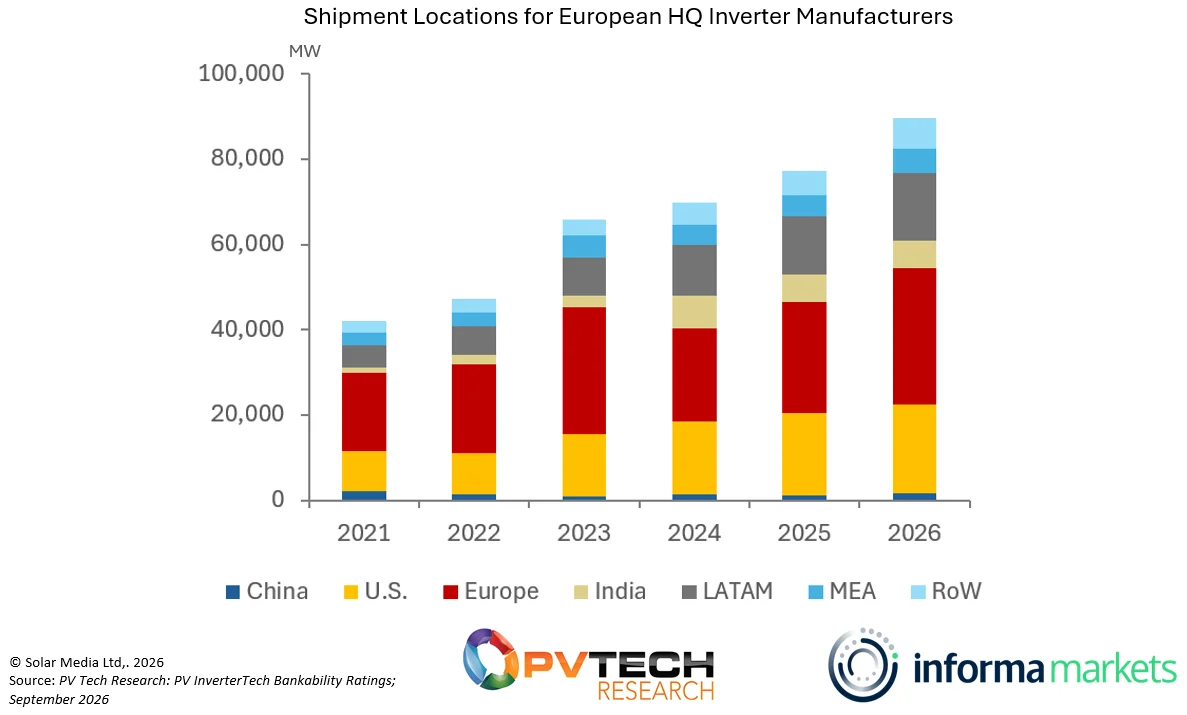
Europe remains the main market for these companies, with nearly one-third of all shipments forecast in 2026 to be supplied in Europe. This is followed by the US—despite the ban on foreign-produced inverters in July this year—and Latin America. The year-on-year growth across the top three markets varies slightly, with Europe seeing the largest increase at almost 6GW, followed by Latin America at 2.2GW and the US at 1.6GW.
The reshoring of inverter manufacturing in Europe has been much more successful than efforts to reshore module production, with the continent surpassing 100GWac of annual solar and energy storage inverter manufacturing earlier this year. The region is the largest inverter manufacturing region outside of China.
Mollie McCorkindale, senior analyst at PV Tech Research, recently wrote about the particularities of Europe’s inverter manufacturing sector, where 90% of Europe’s 100GW annual nameplate manufacturing capacity comes from European-headquartered companies.
Two companies—Germany’s SMA Solar and Spain’s Power Electronics—account for the majority of both the manufacturing capacity and the shipments from European-headquartered companies.
The data shown in this article comes from our in-house market research. Full details on how to subscribe to our PV InverterTech Bankability Ratings Report can be found here.
Source link