

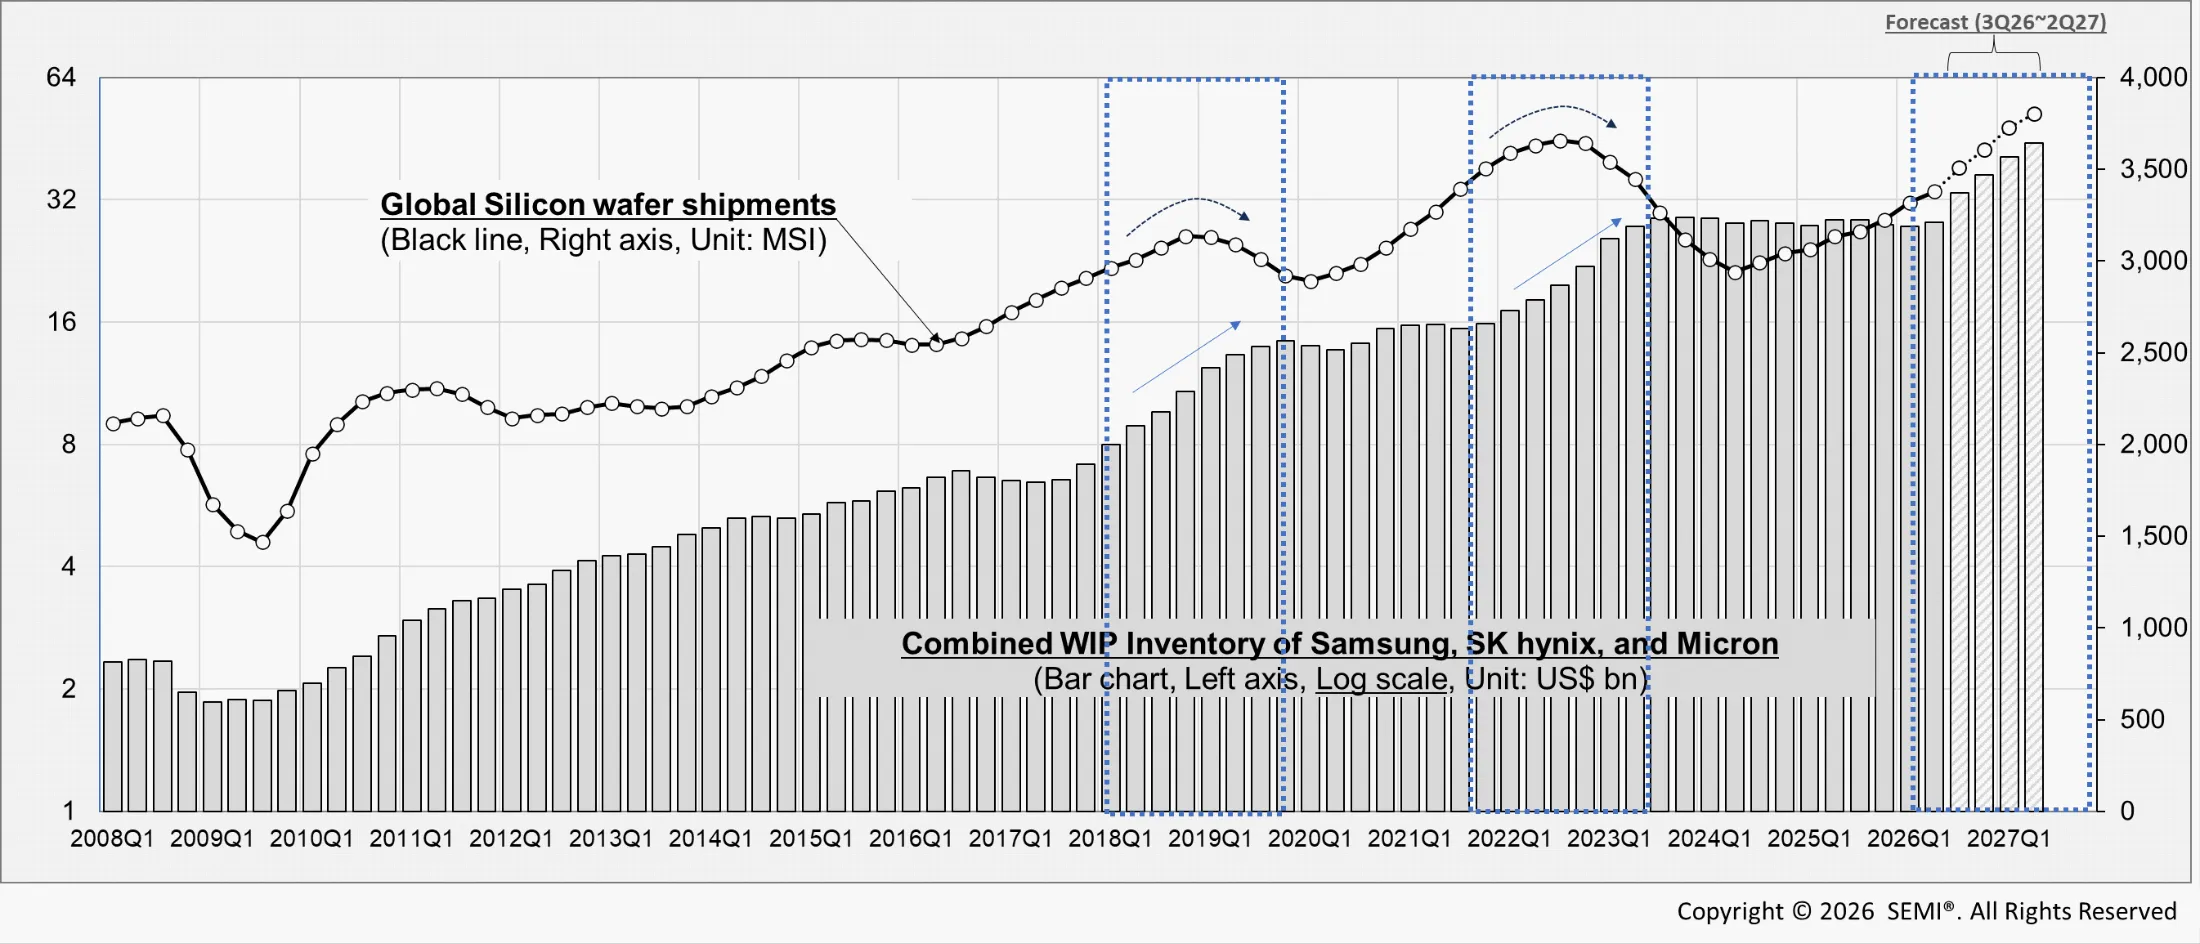
Global silicon wafer shipments are forecast to grow 11.8% in 2026, according to the Q3 2026 SEMI Silicon Wafer Market Monitor. This increase is primarily due to strong demand for AI, which is projected to drive shipments through 2029.
Alongside AI, rising process material sales are also supporting recovery. The positive correlation between material sales and silicon wafer demand not only reflects growth in manufacturing complexity, but it also points to greater material consumption per wafer.
Finally, increases in memory demand, precautionary inventory building, and global fab capacity expansions are boosting silicon wafer shipments as well.
To better understand today’s landscape, it’s helpful to revisit past silicon wafer demand curves. From 2018 to 2019 and from 2022 to 2023, silicon wafer shipments rose ahead of major increases in memory work-in-process (WIP) inventories, or unfinished memory chips undergoing fabrication. However, shipments lagged at the same time WIP inventory peaked. Because fabrication lines were already producing at full capacity, their need for silicon wafers slowed.
While this pattern provides historical context for today’s demand recovery, the high number of new and upcoming production lines is a unique factor influencing this particular cycle.
Silicon Wafer Shipments and Memory WIP: Historical Lead–Lag Pattern. Both series use four-quarter moving averages. Sources: SEMI SMG and financial disclosures from Samsung Electronics, SK hynix, and Micron. Data for 3Q26–2Q27 are forecasts.
SEMI’s fab investment outlook predicts continued growth in planned equipment spending beyond 2026. So long as investment plans remain broadly on track, ongoing equipment installation and capacity ramps are likely to support silicon wafer demand.
Source link





